Commercial Hubs Lead Amid Wider Diversification
Real Estate

Commercial Hubs Lead Amid Wider Diversification

India’s top ten office micro-markets continued to dominate absorption in Q3 2025, accounting for 70 per cent of total demand. However, their share has steadily declined from 82 per cent in Q3 2024 and 80 per cent in Q2 2025, reflecting a clear shift toward broader geographical diversification. Overall, these key markets recorded 13.9 million sq ft of absorption in Q3 2025—down 10 per cent year-on-year and 8 per cent sequentially—despite an increase in pan-India absorption.

The diversification of demand is supported by improved intra-city connectivity, wider availability of Grade-A and sustainable office spaces, competitive rentals aimed at lowering operating costs, and the growth of mature residential clusters across emerging business districts.

India’s real estate sector remained strong, supported by robust GDP growth, moderated inflation, stable monetary policy, healthy employment trends and sustained FDI inflows. Pan-India office absorption rose 6 per cent YoY and 5 per cent QoQ to reach 19.69 million sq ft—marking the second-highest quarterly absorption ever, after the peak of 21.62 million sq ft in Q4 2024. Southern markets continued to drive activity, with Bengaluru, Chennai and Hyderabad together accounting for 50 per cent of national absorption.

Bengaluru topped the charts with 4.63 million sq ft of leasing in Q3 2025, followed by NCR (4.01 million sq ft) and Mumbai (2.98 million sq ft). Kolkata, despite having the lowest absorption at 0.42 million sq ft, saw strong growth of 21 per cent QoQ and 285 per cent YoY, driven by a low base.

Sector-wise, IT-ITeS accounted for 31 per cent of total absorption, a significant drop from nearly 50 per cent in Q2 2025. Meanwhile, demand from the BFSI sector more than doubled, rising from 6 per cent to 15 per cent QoQ. Flexible space operators maintained a steady 14 per cent share.

Rising occupier activity also boosted construction momentum. New completions reached 16.1 million sq ft in Q3 2025—up 10 per cent QoQ and 26 per cent YoY. Pune, Bengaluru and NCR together contributed 63 per cent of the new supply. Pune led with 3.70 million sq ft (23 per cent share), followed by Bengaluru at 3.40 million sq ft (21 per cent). Chennai saw a sharp 320 per cent YoY rise in supply additions, introducing 2.10 million sq ft—its highest in seven quarters.

Shrinivas Rao, FRICS, CEO of Vestian, said, “Q3 2025 recorded the highest absorption of the year, led primarily by GCCs. Strong demand has kept the office market resilient despite global geopolitical and trade uncertainties. Construction activity gained pace, supported by healthy supply across key cities. With robust absorption, consistent supply and a diversified occupier profile, India’s office market is well-positioned for sustained growth. Additionally, emerging H-1B visa restrictions may further accelerate demand for office space as GCCs continue to expand their India presence.”

India’s top ten office micro-markets continued to dominate absorption in Q3 2025, accounting for 70 per cent of total demand. However, their share has steadily declined from 82 per cent in Q3 2024 and 80 per cent in Q2 2025, reflecting a clear shift toward broader geographical diversification. Overall, these key markets recorded 13.9 million sq ft of absorption in Q3 2025—down 10 per cent year-on-year and 8 per cent sequentially—despite an increase in pan-India absorption.The diversification of demand is supported by improved intra-city connectivity, wider availability of Grade-A and sustainable office spaces, competitive rentals aimed at lowering operating costs, and the growth of mature residential clusters across emerging business districts.India’s real estate sector remained strong, supported by robust GDP growth, moderated inflation, stable monetary policy, healthy employment trends and sustained FDI inflows. Pan-India office absorption rose 6 per cent YoY and 5 per cent QoQ to reach 19.69 million sq ft—marking the second-highest quarterly absorption ever, after the peak of 21.62 million sq ft in Q4 2024. Southern markets continued to drive activity, with Bengaluru, Chennai and Hyderabad together accounting for 50 per cent of national absorption.Bengaluru topped the charts with 4.63 million sq ft of leasing in Q3 2025, followed by NCR (4.01 million sq ft) and Mumbai (2.98 million sq ft). Kolkata, despite having the lowest absorption at 0.42 million sq ft, saw strong growth of 21 per cent QoQ and 285 per cent YoY, driven by a low base.Sector-wise, IT-ITeS accounted for 31 per cent of total absorption, a significant drop from nearly 50 per cent in Q2 2025. Meanwhile, demand from the BFSI sector more than doubled, rising from 6 per cent to 15 per cent QoQ. Flexible space operators maintained a steady 14 per cent share.Rising occupier activity also boosted construction momentum. New completions reached 16.1 million sq ft in Q3 2025—up 10 per cent QoQ and 26 per cent YoY. Pune, Bengaluru and NCR together contributed 63 per cent of the new supply. Pune led with 3.70 million sq ft (23 per cent share), followed by Bengaluru at 3.40 million sq ft (21 per cent). Chennai saw a sharp 320 per cent YoY rise in supply additions, introducing 2.10 million sq ft—its highest in seven quarters.Shrinivas Rao, FRICS, CEO of Vestian, said, “Q3 2025 recorded the highest absorption of the year, led primarily by GCCs. Strong demand has kept the office market resilient despite global geopolitical and trade uncertainties. Construction activity gained pace, supported by healthy supply across key cities. With robust absorption, consistent supply and a diversified occupier profile, India’s office market is well-positioned for sustained growth. Additionally, emerging H-1B visa restrictions may further accelerate demand for office space as GCCs continue to expand their India presence.”

Related Stories

Gold Stories
Next Story
Infrastructure Urban

KONE Opens India's First Digital Experience Centre in Pune

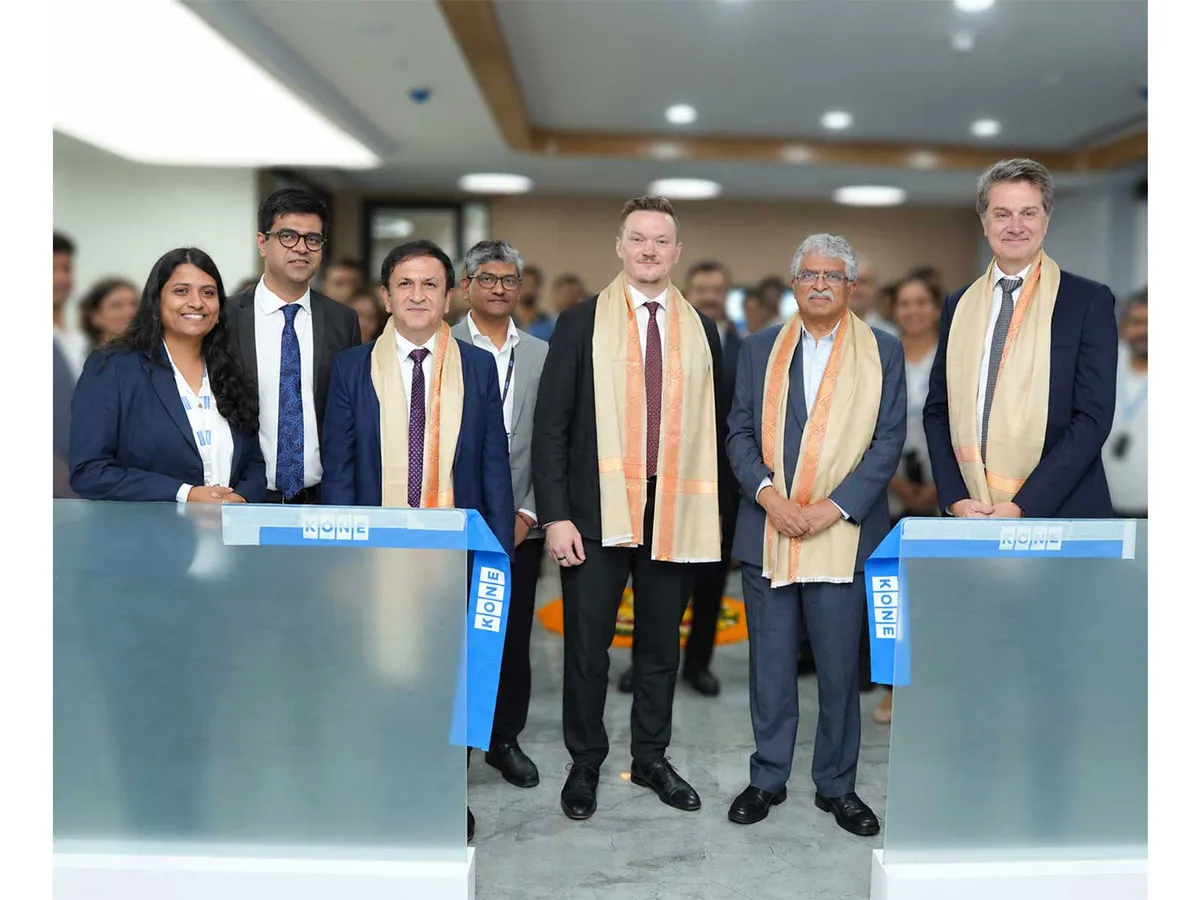
KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

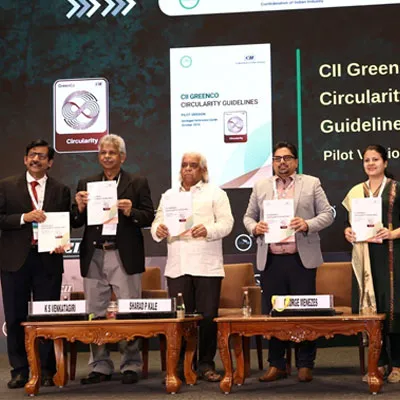
CII GreenCo Launches Circularity Guidelines for Indian Industry

The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

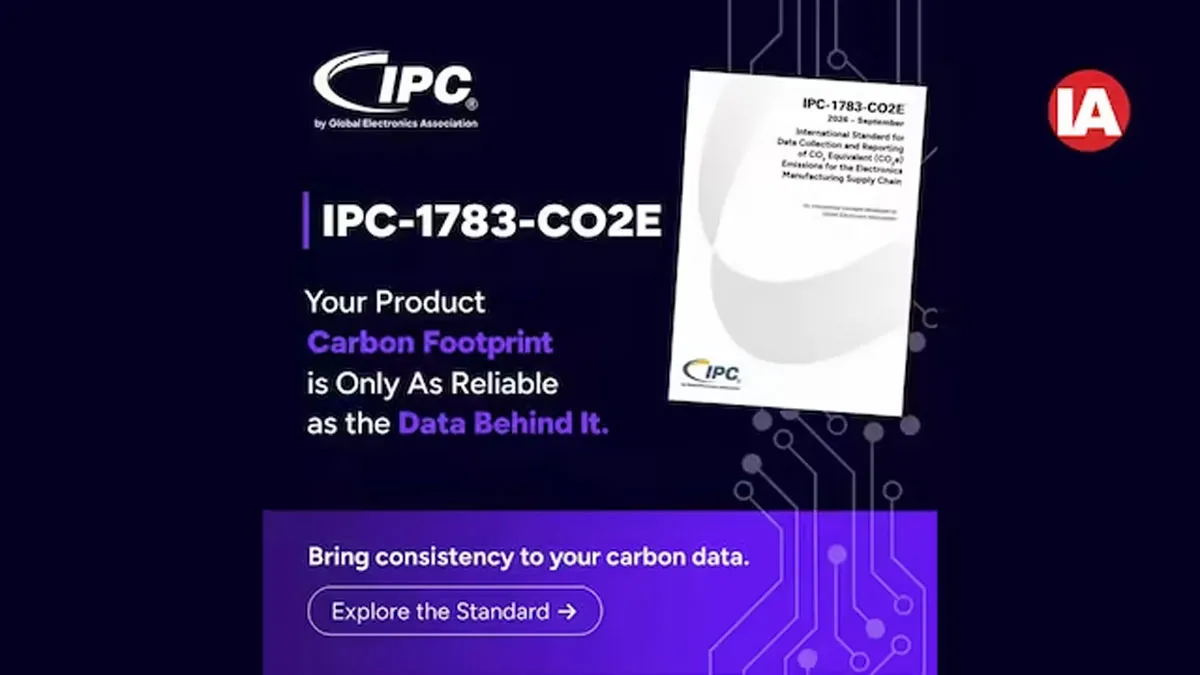
Global Electronics Association Launches IPC-1783-CO2E Standard

The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code