+
Covid-19 second wave: Future realty sentiment takes a dip
Real Estate

Covid-19 second wave: Future realty sentiment takes a dip

The 28th edition of the Knight Frank-FICCI-NAREDCO Real Estate Sentiment Index Q1 2021 (January - March 2021) survey has revealed that the six-month outlook for the real estate sector has weakened across the parameters of demand, supply and pricing in Q1 2021, as the second wave of Covid-19 rages in the country, adversely impacting several industry sectors.

According to the survey, the economy's return to normalcy will depend on the pace of vaccination and the time taken to control the second wave of the pandemic. Apart from the pace of vaccination, government decisions on lockdown restrictions will largely determine the real estate sector's performance in the coming months, the survey said.

In Q1 2021, the future sentiment score saw a decline from 65 in Q4 2020 to 57 in Q1 2021 due to uncertainties resulting from the spread of the second wave of Covid–19 infections. However, it remained in the optimistic zone.

The south zone has seen a marginal decline from 66 in Q4 2020 to 63 in Q1 2021, while the score for the north zone has fallen from 58 in Q4 2020 to 56 in Q1 2021. The Future Sentiment score of the west region witnessed a significant drop from 66 in Q4 2020 to 53 in Q1 2021, while the score for the east zone has fallen from 65 in Q4 2020 to 53 in Q1 2021, it said.

The 'Current Sentiment score' recorded a marginal improvement, inching up from 54 in Q4 2020 to 57 in Q1 2021. This improvement can be attributed to the healthy momentum in the commercial and residential real estate segments during Q4 2020 and during January-February 2021.

A score of above 50 indicates 'Optimism' in sentiments, a score of 50 means the sentiment is 'Same' or 'Neutral', while a score below 50 indicates 'Pessimism'.

Hampered by the second Covid-19 wave concerns, the Future Sentiment score of stakeholders for the next six months has fallen across regions, even while it remains in the optimistic zone. Similarly, the Q1 2021 outlook of supply-side stakeholders reflects caution on the future of the real estate for the next six months, even if their scores remain in the optimistic zone.

With the substantial increase in Covid cases since March 2021, the outlook for residential launches and sales has softened in Q1 2021.

Similarly, the second wave and the resultant mobility restrictions and possible lockdowns in some cities have adversely impacted office occupancy levels. This has resulted in the weakening of the office market outlook for the next six months. On the macroeconomic front, the pace of economic revival seems to have slowed down, with some key economic indicators showing weakening over the last two months. Influenced by the change in macroeconomic developments, stakeholder outlook on the overall economic momentum and on credit availability has turned cautious in Q1 2021, the survey said.

Stakeholder outlook, on the credit availability front, has shifted from positive to observant as 81% of the Q1 2021 survey respondents, down from the 87% of Q4 2020 expect the funding scenario to either improve or remain the same in the coming six months.

Image Source


Also Read: Govt, realty sector help workers cope with second Covid wave

Also Read: CREDAI Pune writes to Maha govt


The 28th edition of the Knight Frank-FICCI-NAREDCO Real Estate Sentiment Index Q1 2021 (January - March 2021) survey has revealed that the six-month outlook for the real estate sector has weakened across the parameters of demand, supply and pricing in Q1 2021, as the second wave of Covid-19 rages in the country, adversely impacting several industry sectors. According to the survey, the economy's return to normalcy will depend on the pace of vaccination and the time taken to control the second wave of the pandemic. Apart from the pace of vaccination, government decisions on lockdown restrictions will largely determine the real estate sector's performance in the coming months, the survey said. In Q1 2021, the future sentiment score saw a decline from 65 in Q4 2020 to 57 in Q1 2021 due to uncertainties resulting from the spread of the second wave of Covid–19 infections. However, it remained in the optimistic zone. The south zone has seen a marginal decline from 66 in Q4 2020 to 63 in Q1 2021, while the score for the north zone has fallen from 58 in Q4 2020 to 56 in Q1 2021. The Future Sentiment score of the west region witnessed a significant drop from 66 in Q4 2020 to 53 in Q1 2021, while the score for the east zone has fallen from 65 in Q4 2020 to 53 in Q1 2021, it said. The 'Current Sentiment score' recorded a marginal improvement, inching up from 54 in Q4 2020 to 57 in Q1 2021. This improvement can be attributed to the healthy momentum in the commercial and residential real estate segments during Q4 2020 and during January-February 2021. A score of above 50 indicates 'Optimism' in sentiments, a score of 50 means the sentiment is 'Same' or 'Neutral', while a score below 50 indicates 'Pessimism'. Hampered by the second Covid-19 wave concerns, the Future Sentiment score of stakeholders for the next six months has fallen across regions, even while it remains in the optimistic zone. Similarly, the Q1 2021 outlook of supply-side stakeholders reflects caution on the future of the real estate for the next six months, even if their scores remain in the optimistic zone. With the substantial increase in Covid cases since March 2021, the outlook for residential launches and sales has softened in Q1 2021. Similarly, the second wave and the resultant mobility restrictions and possible lockdowns in some cities have adversely impacted office occupancy levels. This has resulted in the weakening of the office market outlook for the next six months. On the macroeconomic front, the pace of economic revival seems to have slowed down, with some key economic indicators showing weakening over the last two months. Influenced by the change in macroeconomic developments, stakeholder outlook on the overall economic momentum and on credit availability has turned cautious in Q1 2021, the survey said. Stakeholder outlook, on the credit availability front, has shifted from positive to observant as 81% of the Q1 2021 survey respondents, down from the 87% of Q4 2020 expect the funding scenario to either improve or remain the same in the coming six months. Image Source Also Read: Govt, realty sector help workers cope with second Covid waveAlso Read: CREDAI Pune writes to Maha govt

Related Stories

Gold Stories

Next Story
Real Estate

Peninsula Land launches 19 luxury villas in Pune

Pune’s residential landscape is witnessing a shift as premium homebuyers increasingly seek larger spaces, privacy and independent living options beyond high-rise apartments. Addressing this demand, Peninsula Land Limited, part of the Ashok Piramal Group, has launched AshokVillas, an exclusive collection of 19 premium furnished villas in Gahunje, Pune.The development combines the independence of a standalone home with the convenience and security of a managed residential community. Designed around low-density horizontal living, AshokVillas offers residents private spaces while providing acces..
Next Story
Infrastructure Urban

MyBranch Expands South India Network with 16 Workspace Centres

MyBranch has expanded its South India presence with a 50,000 sq ft flexible workspace network comprising 16 centres across 14 cities in Andhra Pradesh, Karnataka, Tamil Nadu and Telangana.The expansion reflects growing demand for flexible office infrastructure as businesses establish regional teams, satellite offices and operations beyond traditional metropolitan markets. MyBranch’s network spans Bengaluru, Coimbatore, Guntur, Hanamkonda, Hubballi, Hyderabad, Madurai, Mangaluru, Rajahmundry, Salem, Tirupati, Vellore, Vijayawada and Visakhapatnam, with a large office space in Chennai also und..
Next Story
Building Material

Walplast Launches Moisture-Resistant Gypsum Plaster Solutions

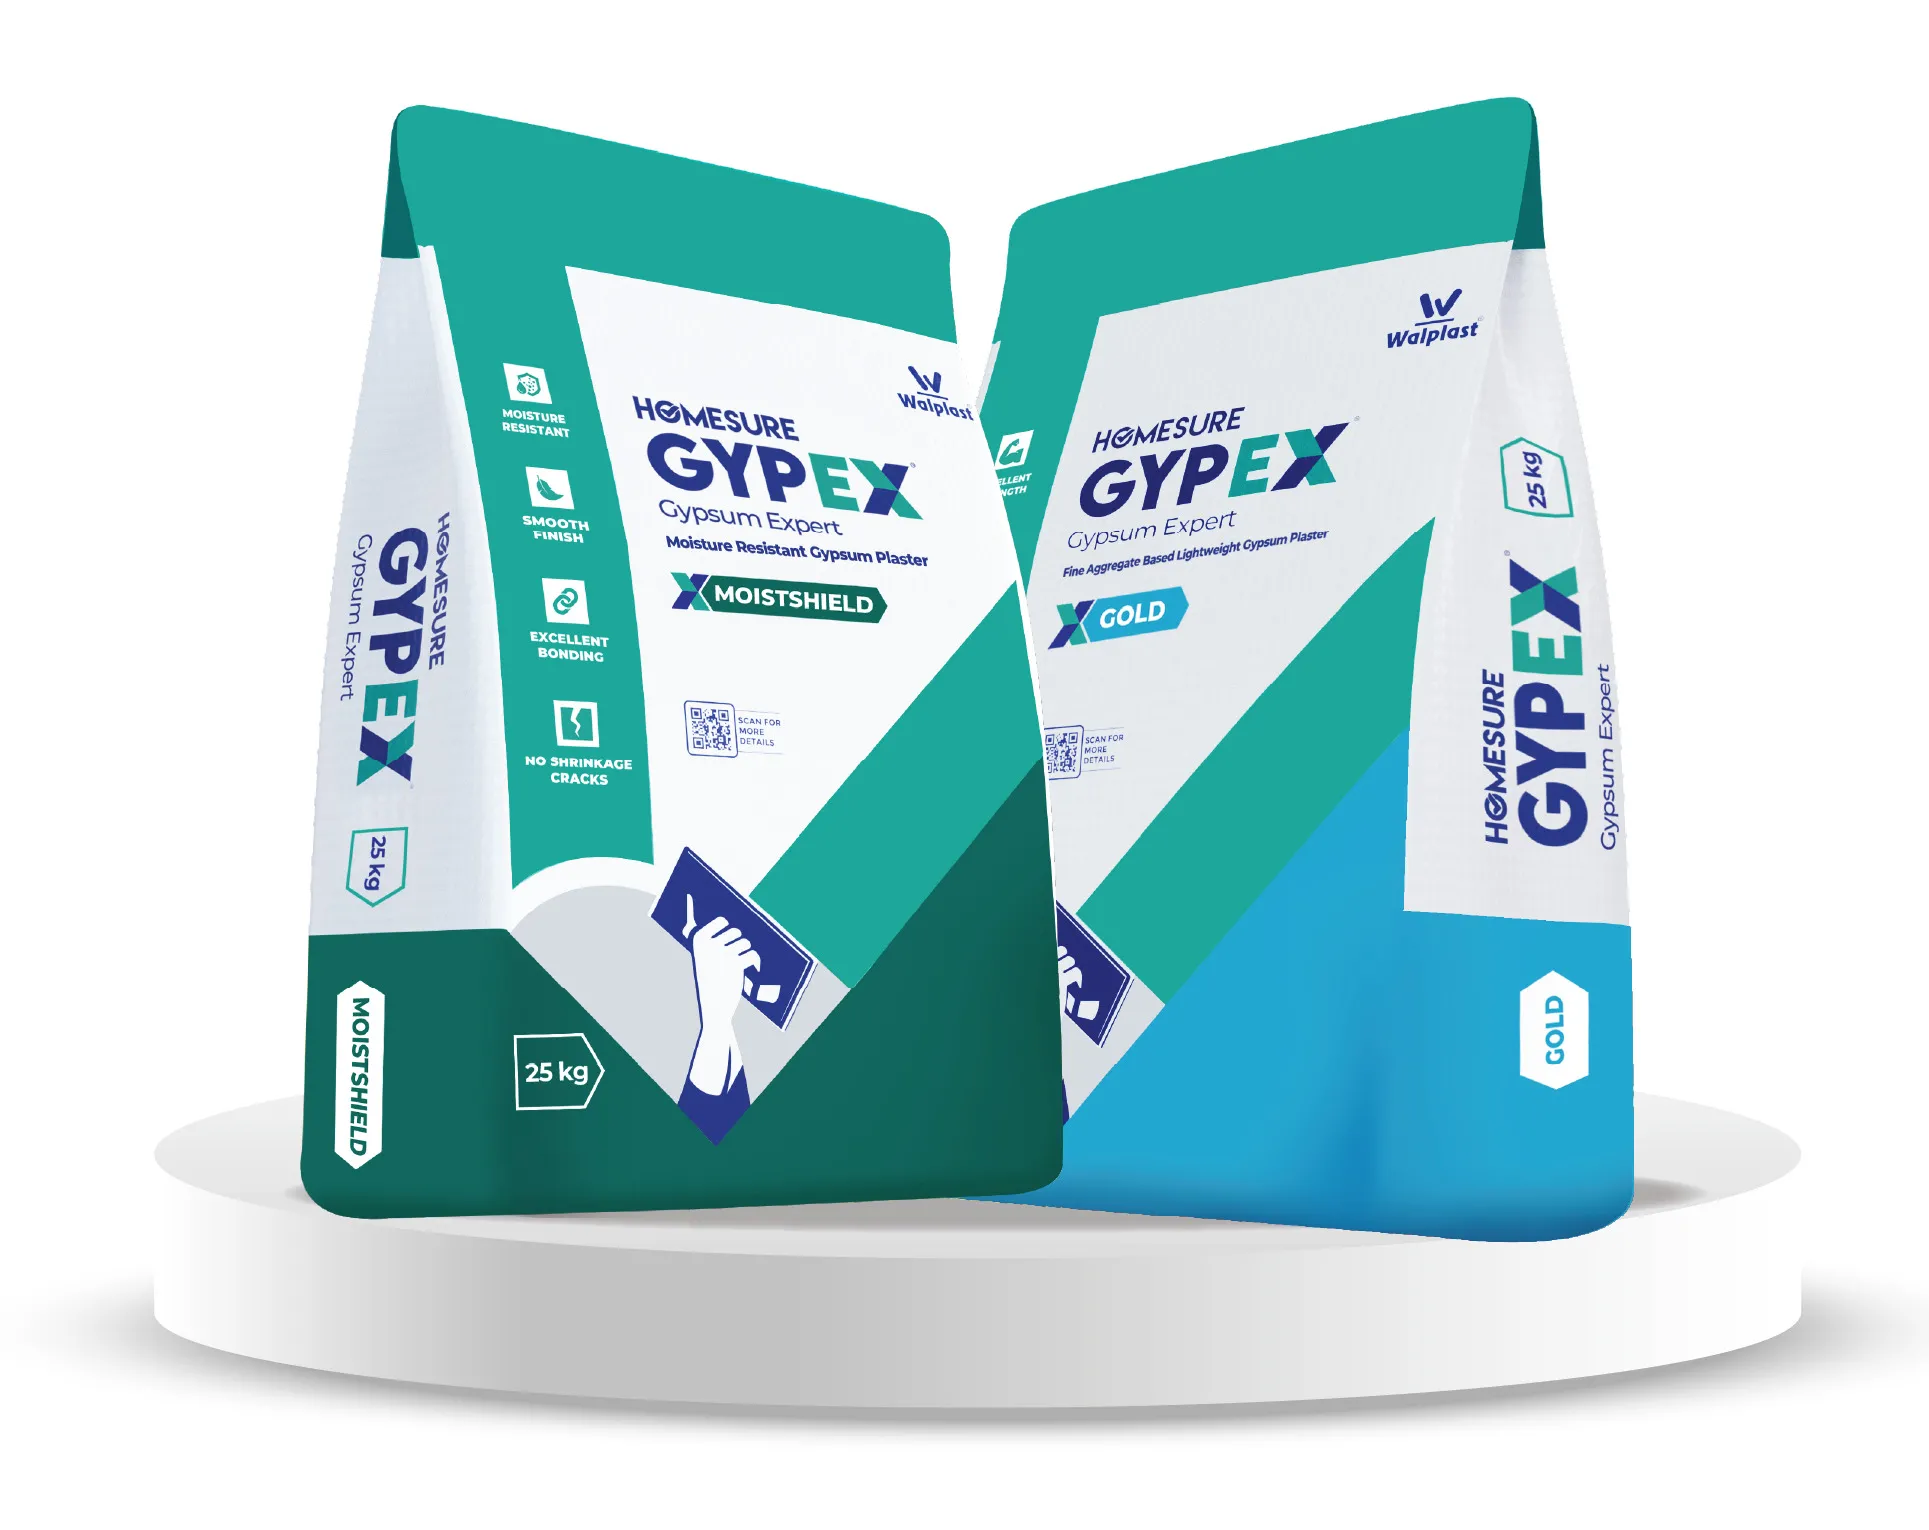
Walplast Products Pvt. Ltd. has expanded its HomeSure GypEx portfolio with the launch of GypEx MoistShield and GypEx Gold, two gypsum plaster solutions designed to address moisture-prone applications and improve plastering efficiency.The new products have been developed in response to the growing demand for faster construction processes, improved material performance and consistent surface quality. The solutions aim to simplify interior plastering while addressing specific application requirements across construction environments.“Through HomeSure GypEx MoistShield and GypEx Gold, we are exp..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code