+
Cement Sector Growth Slows Down
Cement

Cement Sector Growth Slows Down

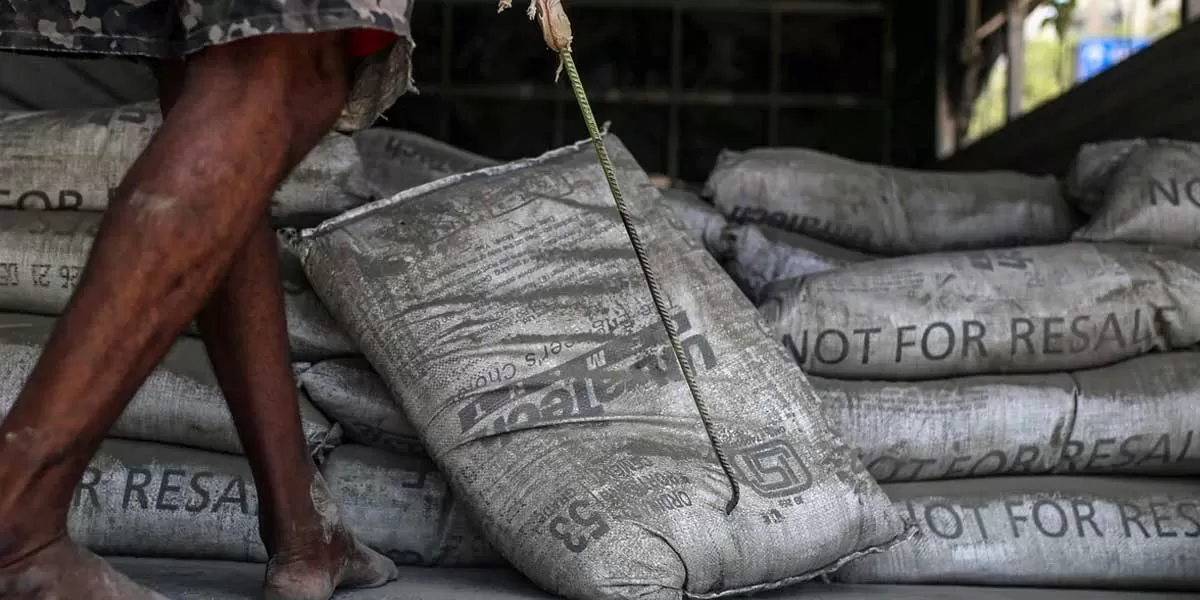
The Indian cement industry's growth forecast for FY25 has been revised down to 4-5% (445-450 MT), primarily due to sluggish construction activity in the housing and infrastructure sectors, according to ICRA. The initial estimate in July was 7-8%, expecting demand to rise in H2, but a slower-than-expected post-election recovery has affected projections.

Key Drivers and Challenges

Muted Volumes: Cement volumes grew just 2% YoY to 212 MT in H1 FY25, impacted by election-related slowdowns and heavy monsoon rains. Rural Demand: A robust rabi season backed by healthy monsoons and strong farm cash flows is expected to improve rural housing demand in H2. Urban and Infrastructure Boost: Urban housing demand remains strong, while increased government capital spending in H2 FY25 (from ?4 lakh crore in H1 to meet a full-year target of ?11.1 lakh crore) should spur infrastructure activity and cement demand. Pricing and Margins

Cement prices fell 10% YoY to ?330 per bag in H1 FY25 due to oversupply and subdued demand, affecting revenue realisation. Operating profit margins dropped to 12% in Q2 FY25, a 375 bps decline YoY, despite reduced coal and pet coke costs (down 38% and 13% YoY, respectively). Capacity Expansion

The industry is expected to add 70-75 MT capacity during FY25-26, with 33-37 MT as clinker capacity. Regional Growth: Eastern and southern regions will lead capacity additions, contributing 38-40 MT evenly split over two years. Utilisation: Capacity utilisation is projected to rise slightly to 71% in FY25 from 70% in FY24. Outlook The cement sector is poised for a recovery in H2 FY25, driven by rural and urban housing demand and higher government spending. However, pricing pressures and oversupply remain challenges. Total installed capacity stands at 690 MT, with moderate utilisation rates indicating room for demand-driven growth.

The Indian cement industry's growth forecast for FY25 has been revised down to 4-5% (445-450 MT), primarily due to sluggish construction activity in the housing and infrastructure sectors, according to ICRA. The initial estimate in July was 7-8%, expecting demand to rise in H2, but a slower-than-expected post-election recovery has affected projections. Key Drivers and Challenges Muted Volumes: Cement volumes grew just 2% YoY to 212 MT in H1 FY25, impacted by election-related slowdowns and heavy monsoon rains. Rural Demand: A robust rabi season backed by healthy monsoons and strong farm cash flows is expected to improve rural housing demand in H2. Urban and Infrastructure Boost: Urban housing demand remains strong, while increased government capital spending in H2 FY25 (from ?4 lakh crore in H1 to meet a full-year target of ?11.1 lakh crore) should spur infrastructure activity and cement demand. Pricing and Margins Cement prices fell 10% YoY to ?330 per bag in H1 FY25 due to oversupply and subdued demand, affecting revenue realisation. Operating profit margins dropped to 12% in Q2 FY25, a 375 bps decline YoY, despite reduced coal and pet coke costs (down 38% and 13% YoY, respectively). Capacity Expansion The industry is expected to add 70-75 MT capacity during FY25-26, with 33-37 MT as clinker capacity. Regional Growth: Eastern and southern regions will lead capacity additions, contributing 38-40 MT evenly split over two years. Utilisation: Capacity utilisation is projected to rise slightly to 71% in FY25 from 70% in FY24. Outlook The cement sector is poised for a recovery in H2 FY25, driven by rural and urban housing demand and higher government spending. However, pricing pressures and oversupply remain challenges. Total installed capacity stands at 690 MT, with moderate utilisation rates indicating room for demand-driven growth.

Related Stories

Gold Stories
Next Story
Infrastructure Transport

Mumbai-Ahmedabad Bullet Train’s Surat-Vapi Section Set for 2027

The first section of the Mumbai-Ahmedabad Bullet Train corridor, linking Surat and Vapi, is targeted to begin services in 2027. Construction is expected to be completed by December 2026, while Railway Minister Ashwini Vaishnaw has indicated that an inauguration could take place around the middle of 2027. The National High Speed Rail Corporation (NHSRCL) said the train being manufactured in India is expected to reach the tracks around April or May 2027. The train will undergo extensive testing before the section is opened for passenger services. The project began construction in 2021 and includ..
Next Story
Infrastructure Transport

Indian Railways Approves Four Projects Worth Rs. 7.36 bn Across Four States

Indian Railways has approved four projects with a combined value of Rs. 7.36 bn across Uttar Pradesh, Maharashtra, Andhra Pradesh and Gujarat. The programme covers train protection, signalling, electric traction supply and a road overbridge, with each project assigned to a different railway zone. In Uttar Pradesh, Rs. 2.52 bn has been approved to extend the Kavach 4.0 automatic train protection system across 607.7 km in the Lucknow Division of North Eastern Railway. The system monitors train movements and can apply the brakes if a driver fails to observe a signal or exceeds a safe speed. The w..
Next Story
Infrastructure Urban

Chandru Raheja Sells 1.49% Stake in Mindspace REIT for Rs. 5 bn

Billionaire Chandru Lachmandas Raheja has sold a 1.49 per cent holding in Mindspace Business Parks REIT for Rs. 5 bn through a bulk deal on the BSE. The transaction involved 9.9 mn units and was executed at an average price of Rs. 505 per unit, according to exchange data. Following the sale, units of Mindspace Business Parks REIT were trading 0.18 per cent lower at Rs. 504.05 on Tuesday. Exchange data did not identify the buyers involved in the transaction. Raheja is the chairman of real estate company K Raheja Corp. The sale involved 99,00,990 units, representing 1.49 per cent of the Mumbai-b..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code