Shishir Baijal: RBI’s 50 bps Rate Cut Boost the Real Estate Sector
ECONOMY & POLICY

Shishir Baijal: RBI’s 50 bps Rate Cut Boost the Real Estate Sector

The RBI’s 50 bps rate cut marks a strong and proactive stance aimed at lifting the low and mid-value housing segments. Over the last few years, the strong housing market momentum was increasingly concentrating in the premium end, even as there were signals of weakening demand in the lower segments. With this cumulative 100 bps cut in the repo rate, we expect a rekindling of demand in these underserved categories, as affordability will witness a meaningful improvement for such homebuyers. 

This move is especially timely, as it comes amid rising concerns about the uneven recovery within the housing sector. A broader recovery across income segments is essential not only to strengthen the residential real estate cycle but also to deepen the socio-economic impact of housing. We hope that the developer community, particularly those focused on mass housing, renews its focus in a big way to give longer legs to this housing market upcycle, which is now in its 5th year.

Liquidity conditions, meanwhile, continue to remain favourable. As of the latest data, the liquidity in the banking system is at Rs 3.7 trn. The RBI’s calibrated liquidity operations through variable rate reverse repos (VRRRs) and open market operations (OMOs) in the last few months have ensured that the system remains sufficiently liquid while avoiding excessive volatility. Furthermore, upcoming gradual reduction of cash reserve ratio (CRR) by 100 bps will bring in consistent liquidity surplus in the system. With liquidity conditions stabilizing, there is now greater scope for commercial banks to accelerate the pass-through of policy easing to borrowers. This would create an enabling environment for lending institutions extend affordable credit to first-time home buyers and middle-income households. 

Further, with stable inflation and relatively contained fiscal risks, the macroeconomic backdrop allows room for policy continuity. As interest rates decline and disposable incomes gradually rise, we expect a broader revival in consumption, of which housing is a cornerstone. A coordinated push from policymakers, lenders, and developers can help ensure that the benefits of this rate cycle reach the households that need it the most.

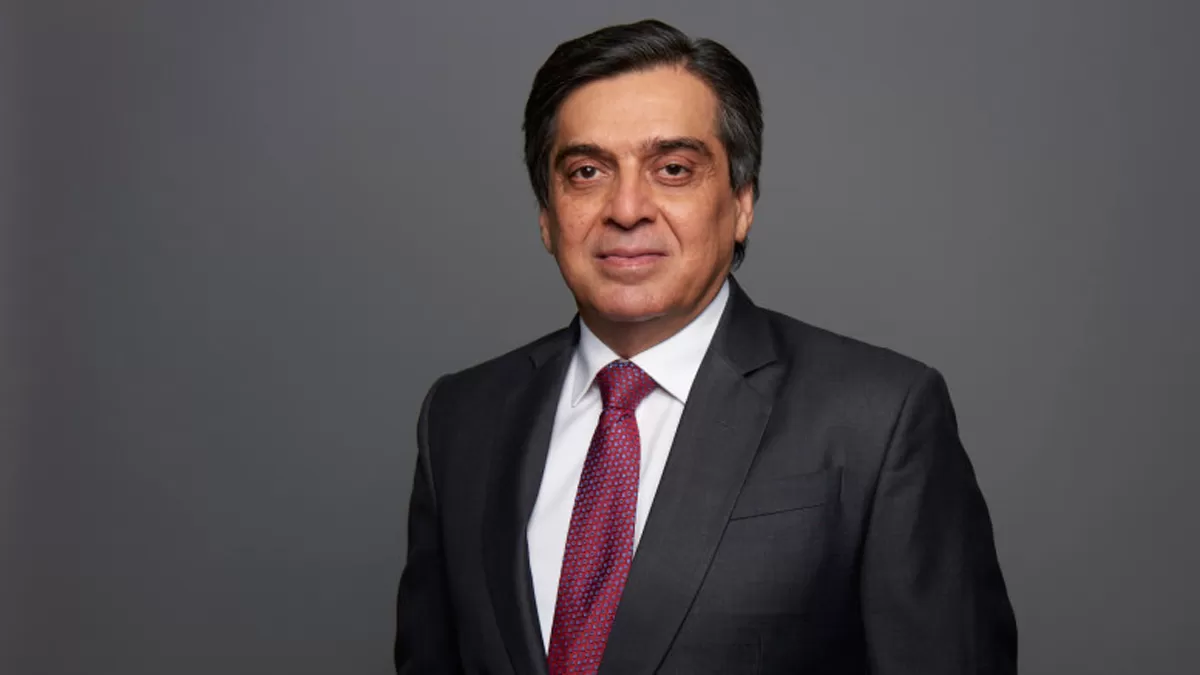
The view is presented by Shishir Baijal, Chairman and Managing Director, Knight Frank India

The RBI’s 50 bps rate cut marks a strong and proactive stance aimed at lifting the low and mid-value housing segments. Over the last few years, the strong housing market momentum was increasingly concentrating in the premium end, even as there were signals of weakening demand in the lower segments. With this cumulative 100 bps cut in the repo rate, we expect a rekindling of demand in these underserved categories, as affordability will witness a meaningful improvement for such homebuyers. This move is especially timely, as it comes amid rising concerns about the uneven recovery within the housing sector. A broader recovery across income segments is essential not only to strengthen the residential real estate cycle but also to deepen the socio-economic impact of housing. We hope that the developer community, particularly those focused on mass housing, renews its focus in a big way to give longer legs to this housing market upcycle, which is now in its 5th year.Liquidity conditions, meanwhile, continue to remain favourable. As of the latest data, the liquidity in the banking system is at Rs 3.7 trn. The RBI’s calibrated liquidity operations through variable rate reverse repos (VRRRs) and open market operations (OMOs) in the last few months have ensured that the system remains sufficiently liquid while avoiding excessive volatility. Furthermore, upcoming gradual reduction of cash reserve ratio (CRR) by 100 bps will bring in consistent liquidity surplus in the system. With liquidity conditions stabilizing, there is now greater scope for commercial banks to accelerate the pass-through of policy easing to borrowers. This would create an enabling environment for lending institutions extend affordable credit to first-time home buyers and middle-income households. Further, with stable inflation and relatively contained fiscal risks, the macroeconomic backdrop allows room for policy continuity. As interest rates decline and disposable incomes gradually rise, we expect a broader revival in consumption, of which housing is a cornerstone. A coordinated push from policymakers, lenders, and developers can help ensure that the benefits of this rate cycle reach the households that need it the most.The view is presented by Shishir Baijal, Chairman and Managing Director, Knight Frank India

Related Stories

Gold Stories

Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code