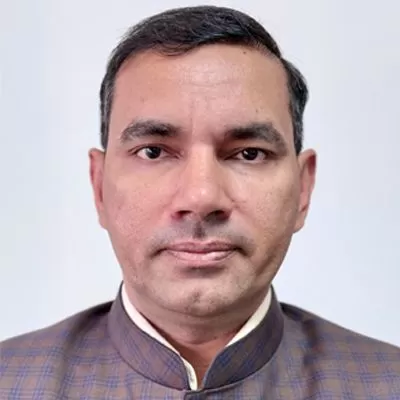
Municipal bonds is gaining traction these days, says Ashish Sable, SBI Capital Markets
SMART CITIES

Municipal bonds is gaining traction these days, says Ashish Sable, SBI Capital Markets

The CW team recently met <span style="font-weight: bold;">Ashish Sable, Senior Vice President &amp; Group Head, Debt Capital Markets, SBI Capital Markets,</span> at the Smart Urbanation Summit held in Hyderabad, organised by Smart Cities Council India. In an exclusive conversation with <span style="font-weight: bold;">SHRIYAL SETHUMADHAVAN and RAHUL KAMAT,</span> Sable talks about the fund-raising scenario in smart cities and how ULBs can strengthen their position. Excerpts:&nbsp; <br /> <br /> <span style="font-weight: bold;">How are the selected smart cities likely to mitigate funding issues? What are the various sources that these smart cities can explore?</span><br /> There are many sources to fund projects envisaged by selected smart cities. One of the important means is grants by governments: Central and state. In fact, the smart cities can structure themselves to monetise some of the assets under their possession and identify revenue-generating projects. However, an area of interest that is gaining traction these days is municipal bonds, which are issued by urban local bodies (ULBs). <br /> <br /> For funding, these smart cities must look beyond Central and state grants and opt for market borrowings. That said, it is a slow process and a number of regulations are stipulated by the Security Exchange Board of India (SEBI) and others. To streamline the initial process, SEBI has created a new set of guidelines other than that of disclosure. We have already tasted the success of these guidelines when we partnered with Pune Municipal Corporation and Greater Hyderabad Municipal Corporation for raising municipal bonds.&nbsp; <br /> <br /> <span style="font-weight: bold;">Will fund-raising make ULBs more accountable and transparent? </span><br /> The process of raising funds through municipal bonds will make ULBs accountable for being transparent. This is because with bonds being listed, investors in the capital market are looking for transparency. This will compel the ULBs to meet the investors' requirement in terms of disclosure, discipline, etc. This financial instrument will also push ULBs for audited finance on a regular basis. <br /> I think the success of both Pune and Hyderabad will be repeated not only by the other ULBs, but by themselves in the coming future.<br /> <br /> <span style="font-weight: bold;">Over the years, how can change in rating parameters help ULBs strengthen their position?&nbsp;</span> <br /> Earlier, most state-level borrowings were through a guaranteed structure. The bonds were guaranteed by the state government. Over time, when rating agencies started rating the state, it came to notice that the ratings were below AA. This was a big setback for ULBs, because if a state is rated below AA, on what basis would the ULB match AA+ or a minimum of AA? <br /> <br /> Now the rating parameters have changed and are based on the cash flow of the state or ULBs. As many of the ULBs have a fixed cash flow from sources, including property tax, water tax, etc, their complete reliance on state or Central grants or funding is averted. A case in point is Pune. Almost 90 per cent of the funds are from its own sources. Importantly, Pune has the ability to collect taxes from citizens and can generate revenues on its own. Commercial entities do not have this kind of fixed source of income, as they are prone to the business cycle.<br /> &nbsp;<br /> By receiving ratings of AA+ and AA respectively, Pune and Hyderabad show that they are creditworthy today.<br />

The CW team recently met <span style="font-weight: bold;">Ashish Sable, Senior Vice President &amp; Group Head, Debt Capital Markets, SBI Capital Markets,</span> at the Smart Urbanation Summit held in Hyderabad, organised by Smart Cities Council India. In an exclusive conversation with <span style="font-weight: bold;">SHRIYAL SETHUMADHAVAN and RAHUL KAMAT,</span> Sable talks about the fund-raising scenario in smart cities and how ULBs can strengthen their position. Excerpts:&nbsp; <br /> <br /> <span style="font-weight: bold;">How are the selected smart cities likely to mitigate funding issues? What are the various sources that these smart cities can explore?</span><br /> There are many sources to fund projects envisaged by selected smart cities. One of the important means is grants by governments: Central and state. In fact, the smart cities can structure themselves to monetise some of the assets under their possession and identify revenue-generating projects. However, an area of interest that is gaining traction these days is municipal bonds, which are issued by urban local bodies (ULBs). <br /> <br /> For funding, these smart cities must look beyond Central and state grants and opt for market borrowings. That said, it is a slow process and a number of regulations are stipulated by the Security Exchange Board of India (SEBI) and others. To streamline the initial process, SEBI has created a new set of guidelines other than that of disclosure. We have already tasted the success of these guidelines when we partnered with Pune Municipal Corporation and Greater Hyderabad Municipal Corporation for raising municipal bonds.&nbsp; <br /> <br /> <span style="font-weight: bold;">Will fund-raising make ULBs more accountable and transparent? </span><br /> The process of raising funds through municipal bonds will make ULBs accountable for being transparent. This is because with bonds being listed, investors in the capital market are looking for transparency. This will compel the ULBs to meet the investors' requirement in terms of disclosure, discipline, etc. This financial instrument will also push ULBs for audited finance on a regular basis. <br /> I think the success of both Pune and Hyderabad will be repeated not only by the other ULBs, but by themselves in the coming future.<br /> <br /> <span style="font-weight: bold;">Over the years, how can change in rating parameters help ULBs strengthen their position?&nbsp;</span> <br /> Earlier, most state-level borrowings were through a guaranteed structure. The bonds were guaranteed by the state government. Over time, when rating agencies started rating the state, it came to notice that the ratings were below AA. This was a big setback for ULBs, because if a state is rated below AA, on what basis would the ULB match AA+ or a minimum of AA? <br /> <br /> Now the rating parameters have changed and are based on the cash flow of the state or ULBs. As many of the ULBs have a fixed cash flow from sources, including property tax, water tax, etc, their complete reliance on state or Central grants or funding is averted. A case in point is Pune. Almost 90 per cent of the funds are from its own sources. Importantly, Pune has the ability to collect taxes from citizens and can generate revenues on its own. Commercial entities do not have this kind of fixed source of income, as they are prone to the business cycle.<br /> &nbsp;<br /> By receiving ratings of AA+ and AA respectively, Pune and Hyderabad show that they are creditworthy today.<br />

Related Stories

Gold Stories

Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..

Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..

Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code