+
Affordability, Credit Growth and Infra Boost India’s Housing Market
Real Estate

Affordability, Credit Growth and Infra Boost India’s Housing Market

India’s residential market has navigated multiple policy shifts and economic events over the past decades—from PMAY and RERA to the GST rollout, demonetisation, the NBFC crisis and the SWAMIH fund. Despite these fluctuations, housing sales across major markets have remained resilient, with post-pandemic demand rising to 0.3–0.4 million units annually. This growth has been supported by infrastructure development, improved affordability, favourable monetary policy and rising incomes.
Income growth has been a key pillar of affordability. Since 2010, average incomes have increased more than fourfold, rising at a CAGR of around 10 per cent, while average housing prices have grown at a slower 5–7 per cent. As a result, affordability levels—measured through the Price-to-Income (P/I) ratio—have strengthened significantly from 88.5 in 2010 to 45.3 in 2025. However, affordability varies across cities and micro markets depending on demand-supply conditions, pricing dynamics and the financial profiles of target buyers. Developers continue to position projects at multiple price points to address the Indian market’s price sensitivity.
Badal Yagnik, Chief Executive Officer and Managing Director, Colliers India, said housing sales remain strong, supported by favourable interest rates and rising incomes. He added that continued income growth and the likelihood of softer interest rates amidst low inflation will further improve affordability in the near term.
Affordability has improved across all eight major residential markets since 2010, with notable declines in P/I ratios. Ahmedabad and Hyderabad have emerged as relatively more affordable markets. Regulatory reforms and monetary measures have strengthened affordability across Tier I cities. Interest rates, which dropped to historic lows after the pandemic, have eased again following the recent cycle of repo rate increases. With the benchmark lending rate now at 5.5 per cent and inflation remaining low, there is scope for further reductions. Concurrently, GST rationalisation on key construction materials is expected to uplift buyer sentiment, particularly in the affordable and mid-income categories.
Credit deployment has also expanded in tandem with demand. Outstanding home loans have increased more than ten-fold from Rs 3 trillion in 2010 to over Rs 30 trillion in 2025. Housing loans now account for about 17 per cent of total bank credit, compared with around 10 per cent in 2010, reflecting sustained demand and stronger credit quality.
Vimal Nadar, National Director and Head of Research, Colliers India, said the steady rise in housing credit demonstrates the sector’s resilience, aided by income growth, improving affordability and greater lender confidence.
Infrastructure development is reshaping residential catchment areas across Tier I cities, expanding demand to central, suburban and peripheral locations. As offices adopt decentralised models beyond traditional CBDs, demand is increasing in well-connected residential clusters near emerging work hubs. Price differentials between central and peripheral areas remain substantial in cities such as Delhi NCR, Mumbai and Chennai, even though improved connectivity has driven strong price growth in peripheral zones. Balanced urban expansion in cities like Ahmedabad, Bengaluru and Hyderabad has resulted in less pronounced price gaps.

India’s residential market has navigated multiple policy shifts and economic events over the past decades—from PMAY and RERA to the GST rollout, demonetisation, the NBFC crisis and the SWAMIH fund. Despite these fluctuations, housing sales across major markets have remained resilient, with post-pandemic demand rising to 0.3–0.4 million units annually. This growth has been supported by infrastructure development, improved affordability, favourable monetary policy and rising incomes.Income growth has been a key pillar of affordability. Since 2010, average incomes have increased more than fourfold, rising at a CAGR of around 10 per cent, while average housing prices have grown at a slower 5–7 per cent. As a result, affordability levels—measured through the Price-to-Income (P/I) ratio—have strengthened significantly from 88.5 in 2010 to 45.3 in 2025. However, affordability varies across cities and micro markets depending on demand-supply conditions, pricing dynamics and the financial profiles of target buyers. Developers continue to position projects at multiple price points to address the Indian market’s price sensitivity.Badal Yagnik, Chief Executive Officer and Managing Director, Colliers India, said housing sales remain strong, supported by favourable interest rates and rising incomes. He added that continued income growth and the likelihood of softer interest rates amidst low inflation will further improve affordability in the near term.Affordability has improved across all eight major residential markets since 2010, with notable declines in P/I ratios. Ahmedabad and Hyderabad have emerged as relatively more affordable markets. Regulatory reforms and monetary measures have strengthened affordability across Tier I cities. Interest rates, which dropped to historic lows after the pandemic, have eased again following the recent cycle of repo rate increases. With the benchmark lending rate now at 5.5 per cent and inflation remaining low, there is scope for further reductions. Concurrently, GST rationalisation on key construction materials is expected to uplift buyer sentiment, particularly in the affordable and mid-income categories.Credit deployment has also expanded in tandem with demand. Outstanding home loans have increased more than ten-fold from Rs 3 trillion in 2010 to over Rs 30 trillion in 2025. Housing loans now account for about 17 per cent of total bank credit, compared with around 10 per cent in 2010, reflecting sustained demand and stronger credit quality.Vimal Nadar, National Director and Head of Research, Colliers India, said the steady rise in housing credit demonstrates the sector’s resilience, aided by income growth, improving affordability and greater lender confidence.Infrastructure development is reshaping residential catchment areas across Tier I cities, expanding demand to central, suburban and peripheral locations. As offices adopt decentralised models beyond traditional CBDs, demand is increasing in well-connected residential clusters near emerging work hubs. Price differentials between central and peripheral areas remain substantial in cities such as Delhi NCR, Mumbai and Chennai, even though improved connectivity has driven strong price growth in peripheral zones. Balanced urban expansion in cities like Ahmedabad, Bengaluru and Hyderabad has resulted in less pronounced price gaps.

Related Stories

Gold Stories

Next Story
Infrastructure Urban

KONE Opens India's First Digital Experience Centre in Pune

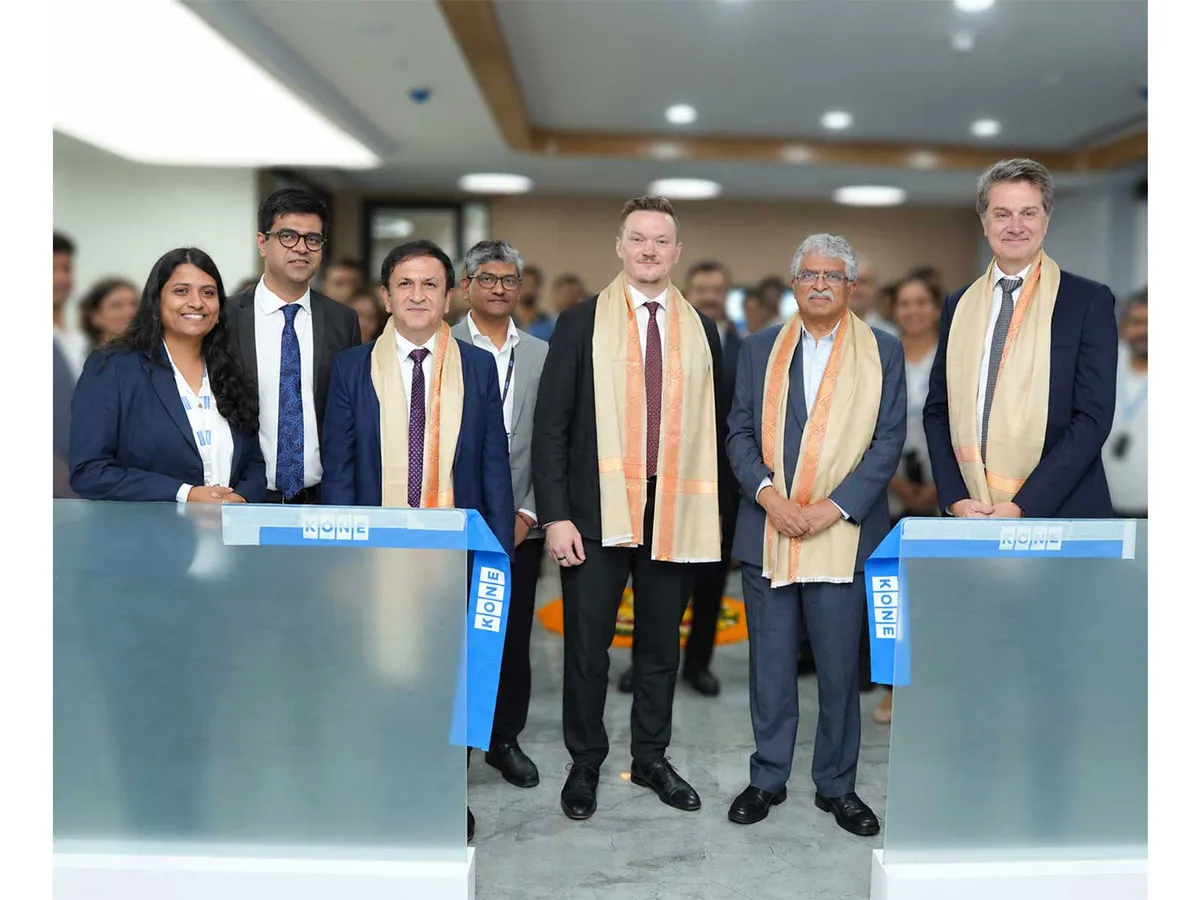
KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

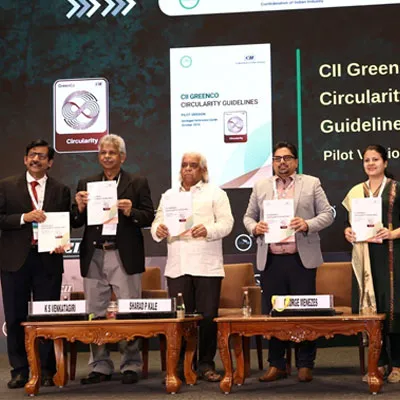
CII GreenCo Launches Circularity Guidelines for Indian Industry

The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

Global Electronics Association Launches IPC-1783-CO2E Standard

The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code