+
New pure-play affordable housing financiers to grow at 40 per cent CAGR
ECONOMY & POLICY

New pure-play affordable housing financiers to grow at 40 per cent CAGR

Plethora of facilitations spurs fast growth, says CRISIL.

As loan facilitations go, the affordable housing segment is getting the best deal in town because government support and tax incentives together mean interest paid could be significantly low for a home loan taken.

Under the credit linked subsidy scheme of the Pradhan Mantri Awas Yojana (PMAY), home loan EMIs could reduce by up to 45 per cent for the economically weaker section and the low income group.

No surprise, then, that new pure-play affordable housing finance companies (AFHCs) have been on a tear, with their assets under management (AUM) rocketing ~50 per cent in the past fiscal to ~Rs 23,000 crore as on March 31, 2017, compared with ~Rs 15,000 crore as on March 31, 2016.

The high growth has also led to increase in market share of these new pure-play players in the overall affordable housing finance sector from ~10 per cent as on March 31, 2016 to ~15 per cent as on March 31, 2017.

CRISIL defines affordable housing loans as those with a ticket size less than Rs 15 lakh.

Says Krishnan Sitaraman, Senior Director, CRISIL Ratings, “We expect AUMs of the new AHFCs to clock ~40 per cent CAGR over the next four years, compared with 17-18 per cent expected for the housing finance sector as a whole. A quarter of home loans today are for affordable housing, driven by a plethora of facilitations.”

The facilitations that have spurred growth include the government’s ‘Housing for All by 2022’ and the PMAY initiatives, the grant of infrastructure status to affordable housing, allowing additional investment limits to debt mutual funds to invest in housing finance companies (HFCs), and lower risk weights for smaller-ticket housing loans.

The upshot has been three-pronged: Existing players have seen capital infusions, more new players are entering the fray, and for borrowers, affordability has improved.

Many of the new pure-play AFHCs are backed by private equities or strong promoters. Over Rs 2,000 crore of capital has been infused over past five years into these AHFCs, with the number of PEs investing more than quadrupling from 4 to 18. CRISIL believes that these AHFCs will need another ~Rs 1,500 crore of capital over the next three years to meet the growth estimates.

The underlying borrower profile in the affordable housing finance segment has led to sharply differentiated portfolio characteristics for these players compared with the overall housing loan market. This includes factors such as higher proportion of self-employed borrowers and borrowers with lower income levels. Accordingly, the origination practices adopted are also different with higher reliance on direct sourcing. Also, the average loan-to-value for these players is lower than that seen for the overall home loan segment.

The underlying borrower profile, coupled with limited financial flexibility of the borrowers leads to potentially higher volatility in portfolio performance. This is evident in the two-year lagged gross non-performing assets of ~3 per cent as compared to ~1 per cent for the overall housing finance sector. Nevertheless, higher returns compensate for these risks to a large extent.

Says Malvika Bhotika, Associate Director, CRISIL Ratings: “While government initiatives and huge market opportunity continue to make the segment attractive, institutionalisation of appropriate origination, credit assessment and underwriting practices and human resources will be the defining elements for long-term sustainability in the affordable housing finance space.”

See the detailed CRISIL report on ‘Affordable homes altering mortgage market dynamics’ below.

Click Here

Plethora of facilitations spurs fast growth, says CRISIL. As loan facilitations go, the affordable housing segment is getting the best deal in town because government support and tax incentives together mean interest paid could be significantly low for a home loan taken. Under the credit linked subsidy scheme of the Pradhan Mantri Awas Yojana (PMAY), home loan EMIs could reduce by up to 45 per cent for the economically weaker section and the low income group. No surprise, then, that new pure-play affordable housing finance companies (AFHCs) have been on a tear, with their assets under management (AUM) rocketing ~50 per cent in the past fiscal to ~Rs 23,000 crore as on March 31, 2017, compared with ~Rs 15,000 crore as on March 31, 2016. The high growth has also led to increase in market share of these new pure-play players in the overall affordable housing finance sector from ~10 per cent as on March 31, 2016 to ~15 per cent as on March 31, 2017. CRISIL defines affordable housing loans as those with a ticket size less than Rs 15 lakh. Says Krishnan Sitaraman, Senior Director, CRISIL Ratings, “We expect AUMs of the new AHFCs to clock ~40 per cent CAGR over the next four years, compared with 17-18 per cent expected for the housing finance sector as a whole. A quarter of home loans today are for affordable housing, driven by a plethora of facilitations.” The facilitations that have spurred growth include the government’s ‘Housing for All by 2022’ and the PMAY initiatives, the grant of infrastructure status to affordable housing, allowing additional investment limits to debt mutual funds to invest in housing finance companies (HFCs), and lower risk weights for smaller-ticket housing loans. The upshot has been three-pronged: Existing players have seen capital infusions, more new players are entering the fray, and for borrowers, affordability has improved. Many of the new pure-play AFHCs are backed by private equities or strong promoters. Over Rs 2,000 crore of capital has been infused over past five years into these AHFCs, with the number of PEs investing more than quadrupling from 4 to 18. CRISIL believes that these AHFCs will need another ~Rs 1,500 crore of capital over the next three years to meet the growth estimates. The underlying borrower profile in the affordable housing finance segment has led to sharply differentiated portfolio characteristics for these players compared with the overall housing loan market. This includes factors such as higher proportion of self-employed borrowers and borrowers with lower income levels. Accordingly, the origination practices adopted are also different with higher reliance on direct sourcing. Also, the average loan-to-value for these players is lower than that seen for the overall home loan segment. The underlying borrower profile, coupled with limited financial flexibility of the borrowers leads to potentially higher volatility in portfolio performance. This is evident in the two-year lagged gross non-performing assets of ~3 per cent as compared to ~1 per cent for the overall housing finance sector. Nevertheless, higher returns compensate for these risks to a large extent. Says Malvika Bhotika, Associate Director, CRISIL Ratings: “While government initiatives and huge market opportunity continue to make the segment attractive, institutionalisation of appropriate origination, credit assessment and underwriting practices and human resources will be the defining elements for long-term sustainability in the affordable housing finance space.” See the detailed CRISIL report on ‘Affordable homes altering mortgage market dynamics’ below. Click Here

Related Stories

Gold Stories
Next Story
Real Estate

Peninsula Land launches 19 luxury villas in Pune

Pune’s residential landscape is witnessing a shift as premium homebuyers increasingly seek larger spaces, privacy and independent living options beyond high-rise apartments. Addressing this demand, Peninsula Land Limited, part of the Ashok Piramal Group, has launched AshokVillas, an exclusive collection of 19 premium furnished villas in Gahunje, Pune.The development combines the independence of a standalone home with the convenience and security of a managed residential community. Designed around low-density horizontal living, AshokVillas offers residents private spaces while providing acces..
Next Story
Infrastructure Urban

MyBranch Expands South India Network with 16 Workspace Centres

MyBranch has expanded its South India presence with a 50,000 sq ft flexible workspace network comprising 16 centres across 14 cities in Andhra Pradesh, Karnataka, Tamil Nadu and Telangana.The expansion reflects growing demand for flexible office infrastructure as businesses establish regional teams, satellite offices and operations beyond traditional metropolitan markets. MyBranch’s network spans Bengaluru, Coimbatore, Guntur, Hanamkonda, Hubballi, Hyderabad, Madurai, Mangaluru, Rajahmundry, Salem, Tirupati, Vellore, Vijayawada and Visakhapatnam, with a large office space in Chennai also und..
Next Story
Building Material

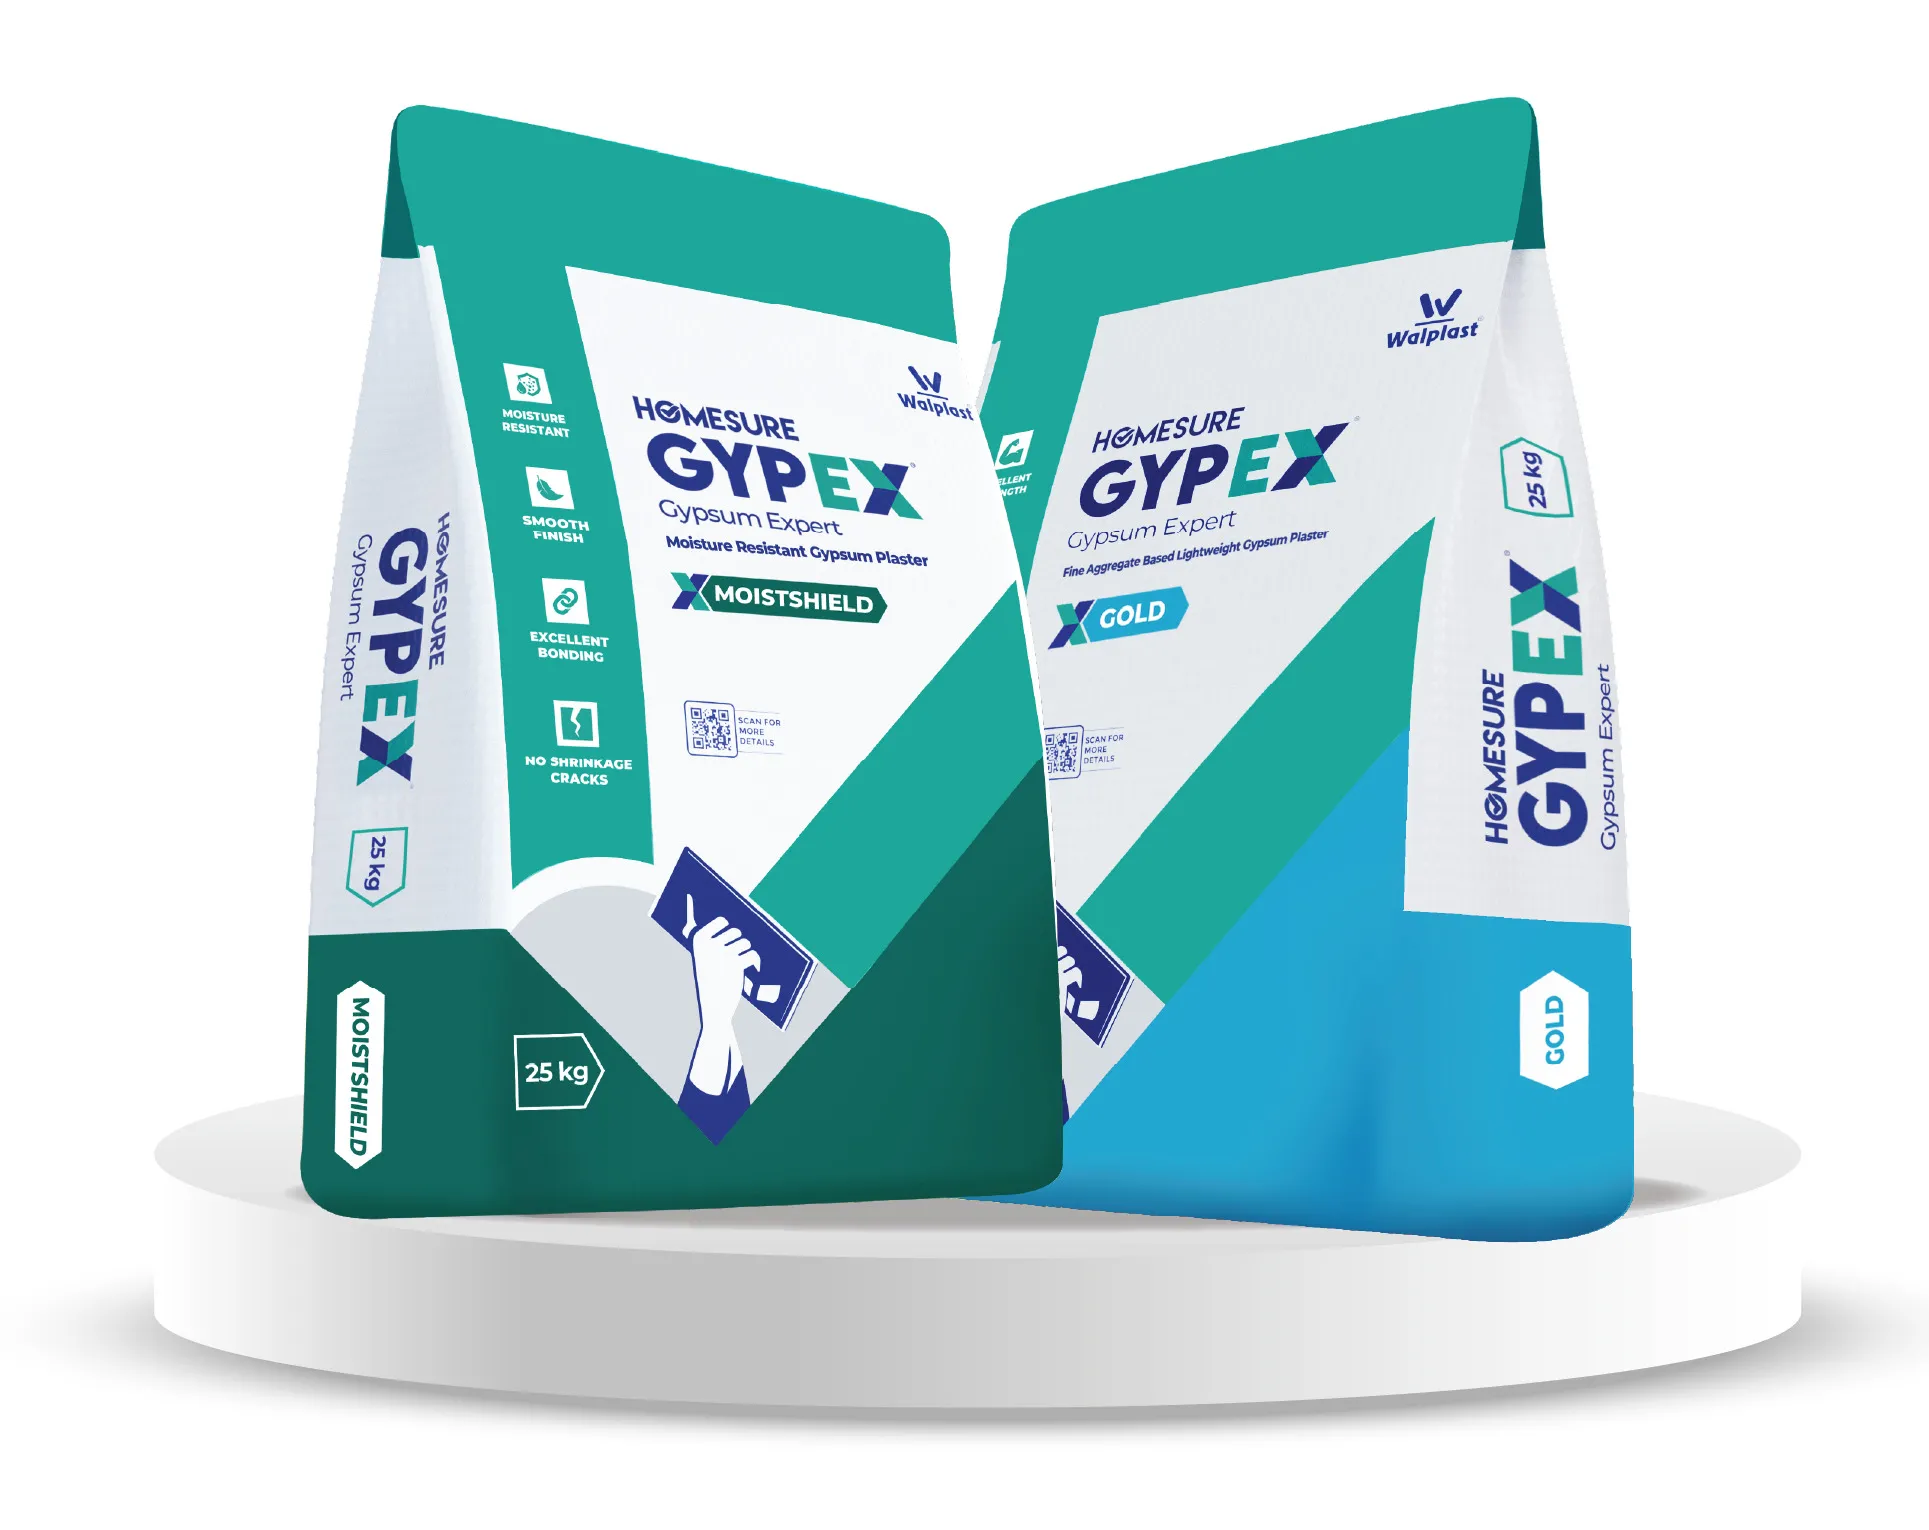
Walplast Launches Moisture-Resistant Gypsum Plaster Solutions

Walplast Products Pvt. Ltd. has expanded its HomeSure GypEx portfolio with the launch of GypEx MoistShield and GypEx Gold, two gypsum plaster solutions designed to address moisture-prone applications and improve plastering efficiency.The new products have been developed in response to the growing demand for faster construction processes, improved material performance and consistent surface quality. The solutions aim to simplify interior plastering while addressing specific application requirements across construction environments.“Through HomeSure GypEx MoistShield and GypEx Gold, we are exp..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code