Taxpayer co-owning more than one home can claim benefit
ECONOMY & POLICY

Taxpayer co-owning more than one home can claim benefit

According to the Mumbai branch of the Income-tax Appellate Tribunal (ITAT), co-ownership of more than one residential property does not prevent a taxpayer from requesting a tax exemption on long- term capital gains. As investments are usually made in joint names in large families, this judgement, made within the ambit of Section 54F of the Income-tax (I-T) Act, will be advantageous to several taxpayers.

When selling capital assets (other than a home), such as jewellery or stocks, the taxpayer may be eligible for a tax exemption under Section 54F on the resulting "long-term" capital gains. There is no tax obligation if the entire net sale consideration is used to fund the purchase or building of a residential property within the allotted time frame. The tax exemption is granted proportionately when only a portion of the sale consideration is put towards real estate.

The requirement that the taxpayer not hold more than one residential property as of the date of sale of the long-term capital asset is one of the eligibility requirements outlined in Section 54F. In other words, the only home that can be possessed is the one that was built or brought into existence for the purpose of claiming the exemption.

According to the Mumbai branch of the Income-tax Appellate Tribunal (ITAT), co-ownership of more than one residential property does not prevent a taxpayer from requesting a tax exemption on long- term capital gains. As investments are usually made in joint names in large families, this judgement, made within the ambit of Section 54F of the Income-tax (I-T) Act, will be advantageous to several taxpayers. When selling capital assets (other than a home), such as jewellery or stocks, the taxpayer may be eligible for a tax exemption under Section 54F on the resulting long-term capital gains. There is no tax obligation if the entire net sale consideration is used to fund the purchase or building of a residential property within the allotted time frame. The tax exemption is granted proportionately when only a portion of the sale consideration is put towards real estate. The requirement that the taxpayer not hold more than one residential property as of the date of sale of the long-term capital asset is one of the eligibility requirements outlined in Section 54F. In other words, the only home that can be possessed is the one that was built or brought into existence for the purpose of claiming the exemption.

Related Stories

Gold Stories

Next Story
Infrastructure Urban

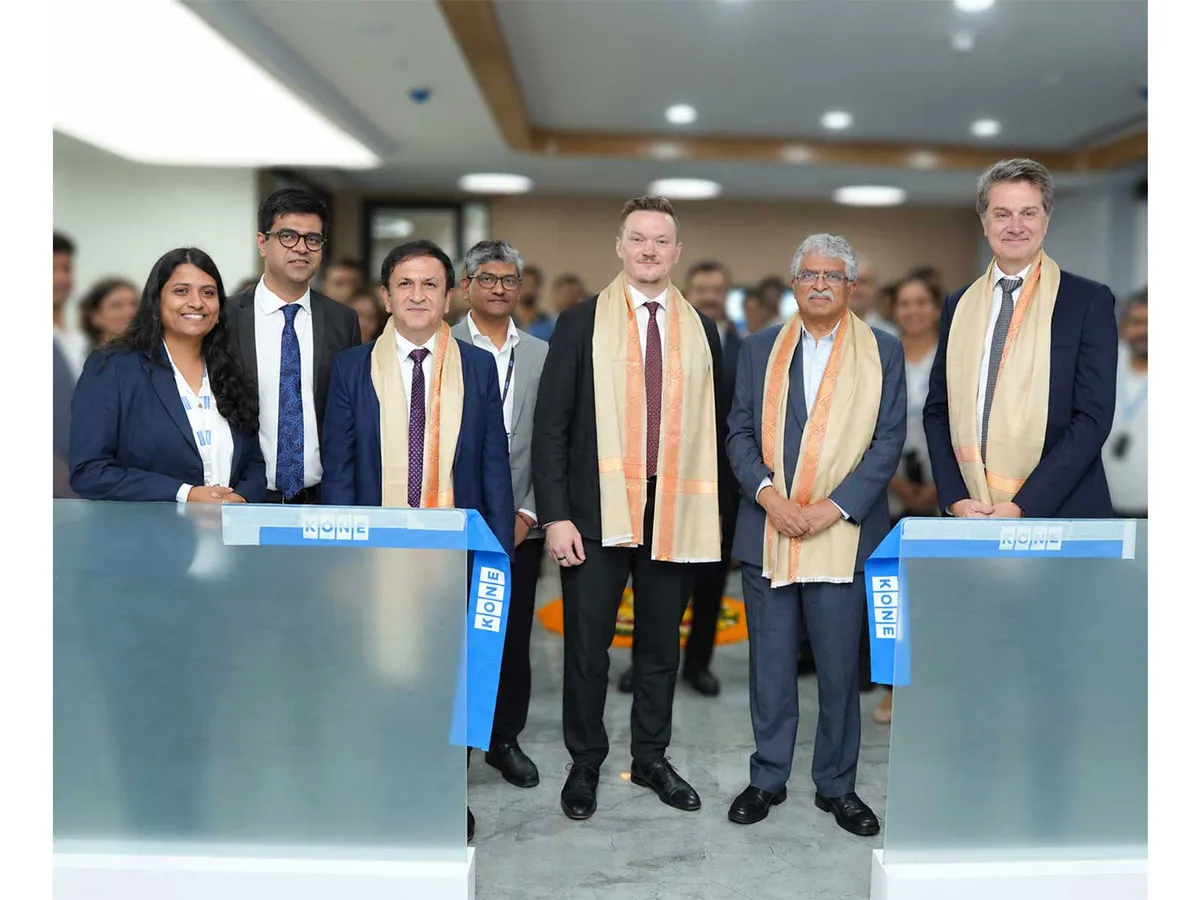
KONE Opens India's First Digital Experience Centre in Pune

KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

CII GreenCo Launches Circularity Guidelines for Indian Industry

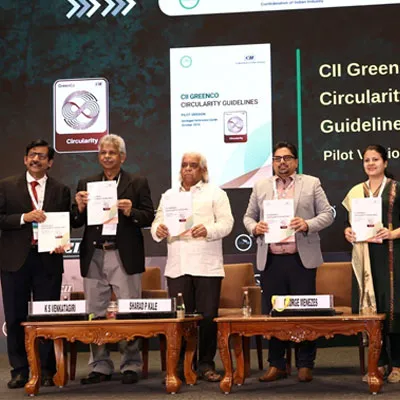
The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

Global Electronics Association Launches IPC-1783-CO2E Standard

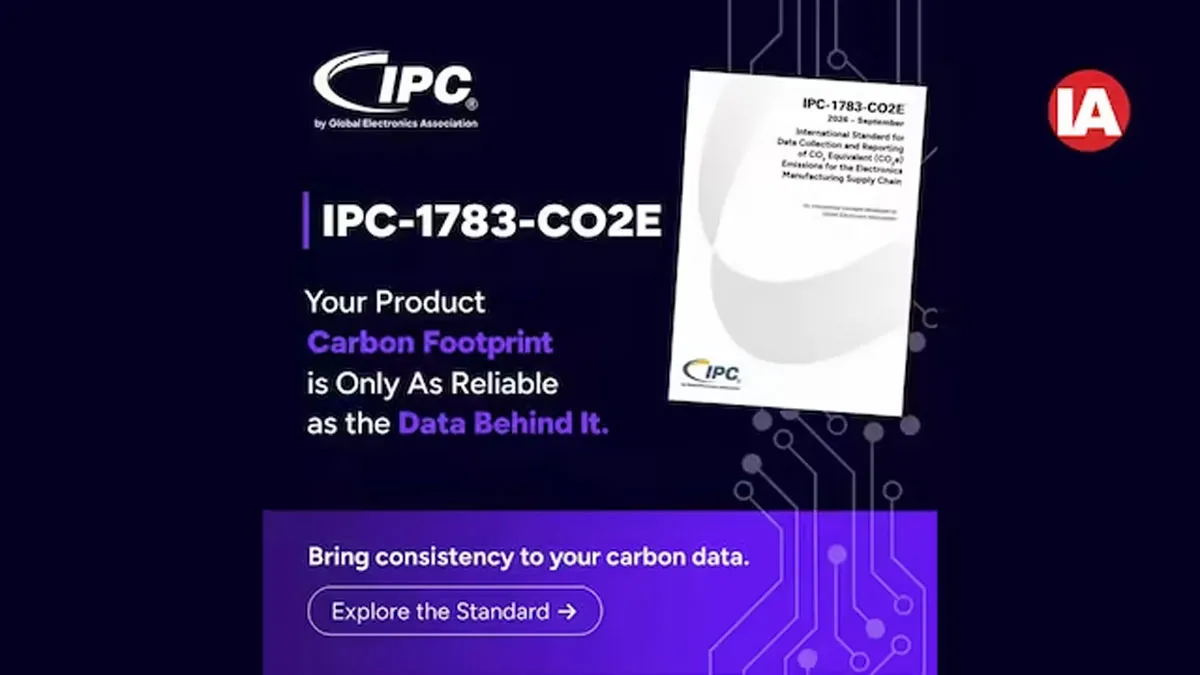
The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code