USA Mortgage Rates Reach 6.95%
ECONOMY & POLICY

USA Mortgage Rates Reach 6.95%

In July 2024, the average mortgage rate in the USA rose to 6.95%, marking a significant increase and impacting homebuyers nationwide. This upward trend in mortgage rates is attributed to several economic factors, including inflationary pressures, shifts in the Federal Reserve?s monetary policy, and broader market dynamics.

The rise in mortgage rates presents challenges for potential homebuyers, making borrowing more expensive and potentially slowing down the housing market. Higher rates can lead to increased monthly payments for homeowners, reducing affordability and potentially deterring new buyers from entering the market. This shift can also affect existing homeowners looking to refinance their mortgages, as higher rates may negate the benefits of refinancing.

Economic analysts link the rate hike to ongoing inflation concerns and the Federal Reserve's efforts to combat rising prices. As the central bank raises interest rates to curb inflation, mortgage rates tend to follow suit, leading to higher borrowing costs across various sectors, including housing. This dynamic underscores the interconnectedness of monetary policy and the housing market, highlighting how macroeconomic strategies impact individual financial decisions.

The increase in mortgage rates also reflects broader trends in the financial markets. Bond yields, which heavily influence mortgage rates, have risen due to investor expectations of continued monetary tightening. As bond yields climb, mortgage rates typically rise in tandem, reflecting the higher cost of borrowing in the broader economy.

For homebuyers, the increased rates necessitate a reassessment of purchasing power and affordability. Prospective buyers may need to adjust their budgets or consider different financing options to navigate the higher cost of borrowing. Additionally, the housing market could experience a slowdown in sales activity as higher rates deter some buyers from entering the market.

In conclusion, the rise in the average mortgage rate to 6.95% in July 2024 signals a notable shift in the housing finance landscape. This development underscores the importance of monitoring economic indicators and their influence on housing affordability and market dynamics. Homebuyers and industry stakeholders must stay informed and adapt to these changes to navigate the evolving financial environment effectively.

In July 2024, the average mortgage rate in the USA rose to 6.95%, marking a significant increase and impacting homebuyers nationwide. This upward trend in mortgage rates is attributed to several economic factors, including inflationary pressures, shifts in the Federal Reserve?s monetary policy, and broader market dynamics. The rise in mortgage rates presents challenges for potential homebuyers, making borrowing more expensive and potentially slowing down the housing market. Higher rates can lead to increased monthly payments for homeowners, reducing affordability and potentially deterring new buyers from entering the market. This shift can also affect existing homeowners looking to refinance their mortgages, as higher rates may negate the benefits of refinancing. Economic analysts link the rate hike to ongoing inflation concerns and the Federal Reserve's efforts to combat rising prices. As the central bank raises interest rates to curb inflation, mortgage rates tend to follow suit, leading to higher borrowing costs across various sectors, including housing. This dynamic underscores the interconnectedness of monetary policy and the housing market, highlighting how macroeconomic strategies impact individual financial decisions. The increase in mortgage rates also reflects broader trends in the financial markets. Bond yields, which heavily influence mortgage rates, have risen due to investor expectations of continued monetary tightening. As bond yields climb, mortgage rates typically rise in tandem, reflecting the higher cost of borrowing in the broader economy. For homebuyers, the increased rates necessitate a reassessment of purchasing power and affordability. Prospective buyers may need to adjust their budgets or consider different financing options to navigate the higher cost of borrowing. Additionally, the housing market could experience a slowdown in sales activity as higher rates deter some buyers from entering the market. In conclusion, the rise in the average mortgage rate to 6.95% in July 2024 signals a notable shift in the housing finance landscape. This development underscores the importance of monitoring economic indicators and their influence on housing affordability and market dynamics. Homebuyers and industry stakeholders must stay informed and adapt to these changes to navigate the evolving financial environment effectively.

Related Stories

Gold Stories
Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
Next Story
Infrastructure Urban

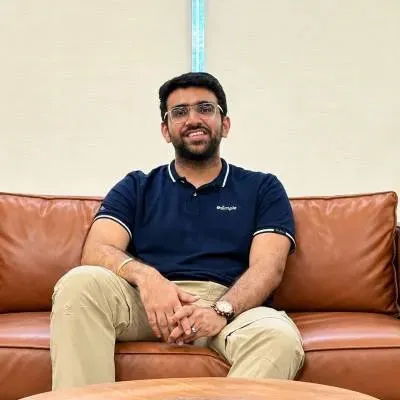
India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code