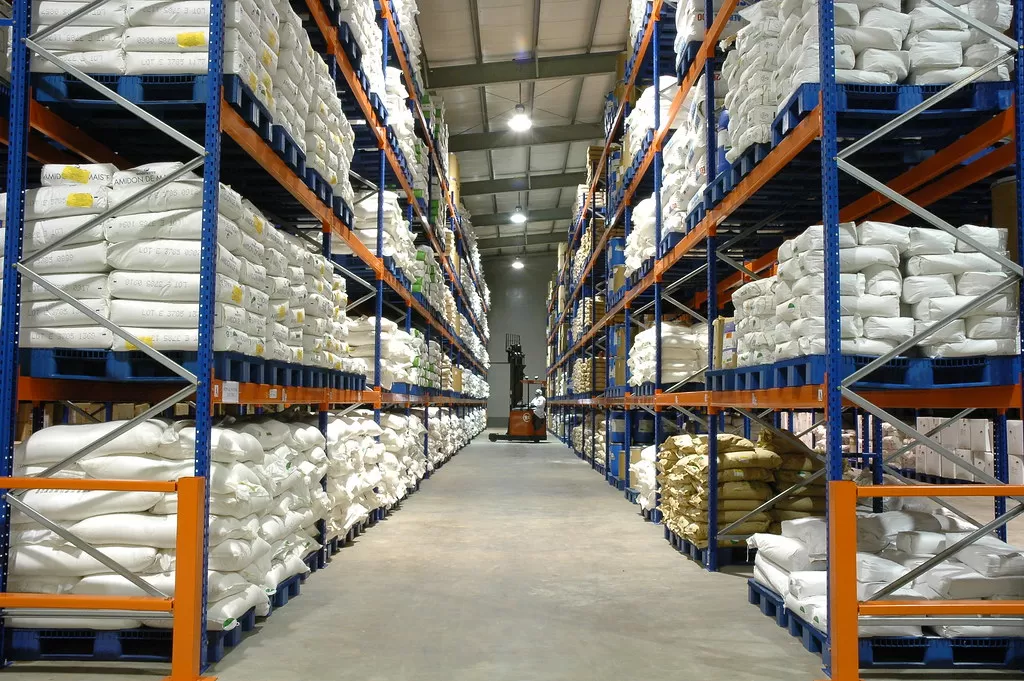
Industrial & warehousing supply in Q1 2024 inches towards 7 mn sq ft
WAREHOUSING & LOGISTICS

Industrial & warehousing supply in Q1 2024 inches towards 7 mn sq ft

Amidst steady leasing, new supply inched towards 7 million sq ft during Q1 2024, the highest in last two years. Around 33% of the new Grade A developments in the first quarter was concentrated in Delhi NCR. Industrial and warehousing leasing activity across the top five cities remained buoyant during Q1 2024 at 7 million sq ft. Mumbai and Chennai led the demand with about 55% share. Interestingly, leasing in Chennai, especially remained robust, with industrial & warehousing space take-up in Q1 2024 almost twice the leasing activity in corresponding period of last year. Across the top five cities, Bhiwandi in Mumbai with 1.7 million sq ft of Grade A demand, was the most active market for Q1 2024. Bhiwandi was followed by Oragadam in Chennai, which surpassed leasing activity of Chakan Talegoan in Pune for the first time in a while.

Third-party logistics players (3PL) continued to be the top occupiers of industrial and warehousing space, contributing to over 40% in the total warehousing demand. 3PL space uptake was driven by healthy activity in Chennai particularly. The city accounted for about 43% of the overall 3PL activity in the top five cities. Interestingly, at the Pan-India level, retail players accounted for 16% of the demand during the quarter, followed by engineering and automobile players with 12% share each. ?While 3PL players continued to drive industrial & warehousing leasing activity, demand from Retail, Engineering and Automobile players too accounted for a significant share in Q1 2024. It is noteworthy to see that the cumulative share of these three sectors have risen from 26% in Q1 2023 to 40% in Q1 2024. This signifies changing consumption patterns and hints at opportunities emerging in the sector from the steady demand diversification.? says Vijay Ganesh, Managing Director, Industrial & Logistics Services, Colliers India.

Both retail and E-commerce segment witness over 2X surge in leasing

E-commerce segment has seen robust growth post Covid-19 and witnessed 2.3X times leasing during Q1 2024 compared to the same period in 2023. With increased focus on digital infrastructure and changing consumption patterns, E-commerce segment is further likely to warm up and create more demand for warehouses. Moreover, the rise of Q-commerce players is also likely to catalyze demand for bigger hub-warehouses.

Warehousing space uptake by retail players also witnessed heightened traction in Q1 2024 and witnessed more than twice the demand a year ago. The expansionary activity is being driven by strong retail activity across cities, especially in large department stores. Favorable consumption pattern has the potential to translate into healthy demand for warehousing space in the upcoming quarters.

Large sized deals account for over 50% of the industrial & warehousing space demand

During Q1 2024, large deals (>200,000 sq ft) accounted for 51% of the demand, a significant rise from about 40% share during 2023. Amongst these larger deals, 3PL companies continued to account for the bulk of share. However, the rise in share of large deals was driven by large space uptake, particularly by retail and E-commerce players during the quarter. Chennai followed by Mumbai dominated the proportion of large-sized deals across the top five cities.

?While the average quarterly industrial and warehousing space demand in the last two years has been at around 6 mn sq ft, average incremental supply has been comparatively lower. With continued healthy leasing activity in last few quarters, developer confidence seems to have significantly improved. With a Grade A supply pipeline of about 23-25 mn sq ft for the year 2024, supply is likely to closely follow demand trend across the top five cities of the country. Overall, an upbeat start to the year holds potential to translate into a healthy performance by the industrial & warehousing sector in 2024.? says Vimal Nadar, Senior Director & Head of Research, Colliers India.

Amidst steady leasing, new supply inched towards 7 million sq ft during Q1 2024, the highest in last two years. Around 33% of the new Grade A developments in the first quarter was concentrated in Delhi NCR. Industrial and warehousing leasing activity across the top five cities remained buoyant during Q1 2024 at 7 million sq ft. Mumbai and Chennai led the demand with about 55% share. Interestingly, leasing in Chennai, especially remained robust, with industrial & warehousing space take-up in Q1 2024 almost twice the leasing activity in corresponding period of last year. Across the top five cities, Bhiwandi in Mumbai with 1.7 million sq ft of Grade A demand, was the most active market for Q1 2024. Bhiwandi was followed by Oragadam in Chennai, which surpassed leasing activity of Chakan Talegoan in Pune for the first time in a while. Third-party logistics players (3PL) continued to be the top occupiers of industrial and warehousing space, contributing to over 40% in the total warehousing demand. 3PL space uptake was driven by healthy activity in Chennai particularly. The city accounted for about 43% of the overall 3PL activity in the top five cities. Interestingly, at the Pan-India level, retail players accounted for 16% of the demand during the quarter, followed by engineering and automobile players with 12% share each. ?While 3PL players continued to drive industrial & warehousing leasing activity, demand from Retail, Engineering and Automobile players too accounted for a significant share in Q1 2024. It is noteworthy to see that the cumulative share of these three sectors have risen from 26% in Q1 2023 to 40% in Q1 2024. This signifies changing consumption patterns and hints at opportunities emerging in the sector from the steady demand diversification.? says Vijay Ganesh, Managing Director, Industrial & Logistics Services, Colliers India. Both retail and E-commerce segment witness over 2X surge in leasing E-commerce segment has seen robust growth post Covid-19 and witnessed 2.3X times leasing during Q1 2024 compared to the same period in 2023. With increased focus on digital infrastructure and changing consumption patterns, E-commerce segment is further likely to warm up and create more demand for warehouses. Moreover, the rise of Q-commerce players is also likely to catalyze demand for bigger hub-warehouses. Warehousing space uptake by retail players also witnessed heightened traction in Q1 2024 and witnessed more than twice the demand a year ago. The expansionary activity is being driven by strong retail activity across cities, especially in large department stores. Favorable consumption pattern has the potential to translate into healthy demand for warehousing space in the upcoming quarters. Large sized deals account for over 50% of the industrial & warehousing space demand During Q1 2024, large deals (>200,000 sq ft) accounted for 51% of the demand, a significant rise from about 40% share during 2023. Amongst these larger deals, 3PL companies continued to account for the bulk of share. However, the rise in share of large deals was driven by large space uptake, particularly by retail and E-commerce players during the quarter. Chennai followed by Mumbai dominated the proportion of large-sized deals across the top five cities. ?While the average quarterly industrial and warehousing space demand in the last two years has been at around 6 mn sq ft, average incremental supply has been comparatively lower. With continued healthy leasing activity in last few quarters, developer confidence seems to have significantly improved. With a Grade A supply pipeline of about 23-25 mn sq ft for the year 2024, supply is likely to closely follow demand trend across the top five cities of the country. Overall, an upbeat start to the year holds potential to translate into a healthy performance by the industrial & warehousing sector in 2024.? says Vimal Nadar, Senior Director & Head of Research, Colliers India.

Related Stories

Gold Stories

Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..

Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..

Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code