+
Q1 2025 Industrial & Warehousing Demand up 15% YoY to 9 Mn sq ft
WAREHOUSING & LOGISTICS

Q1 2025 Industrial & Warehousing Demand up 15% YoY to 9 Mn sq ft

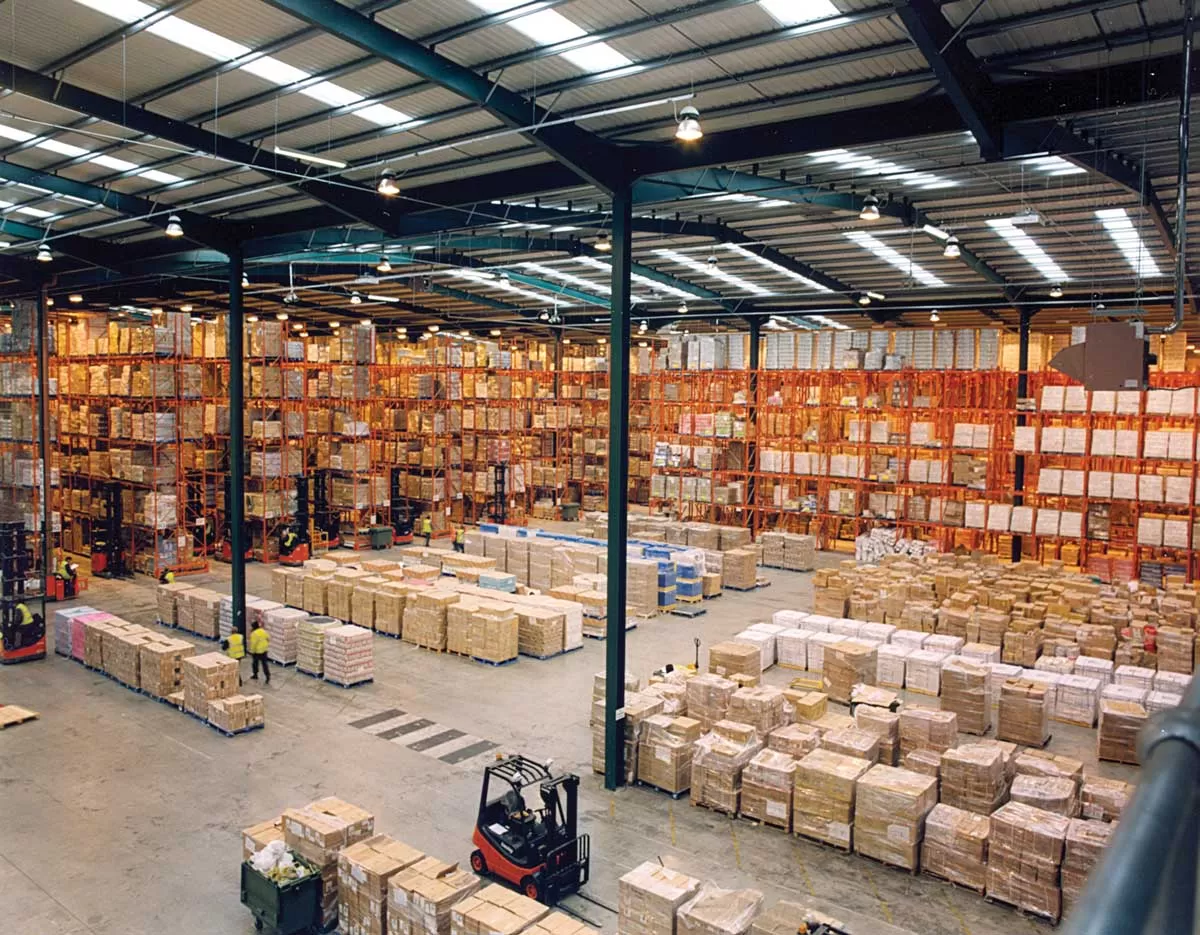
With 9 million sq ft of leasing in Q1 2025 at a 15 per cent Y-o-Y growth, industrial & warehousing demand across the top eight cities remained robust. Delhi NCR and Chennai led the demand, cumulatively accounting for around 57 per cent of the overall leasing in Q1 2025. The demand for Grade A industrial & warehousing space was particularly impressive in Delhi NCR; the city has already witnessed about half of the leasing activity of 2024 in the first quarter of 2025 alone. Interestingly, across the top eight cities, engineering sector drove demand this quarter, contributing to about 25 per cent of the overall industrial & warehousing space uptake, followed by e-commerce with 21 per cent share. Both these sectors have surpassed the demand from Third Party Logistics (3PL) players, the usual frontrunner. While Chennai and Bengaluru saw strong traction from occupiers in the engineering space, demand from e-commerce players remained significant in Delhi NCR and Mumbai.

At a micro market level, Bhiwandi in Mumbai led leasing activity in the first quarter with about 1.0 million sq ft of demand, followed by Luhari (0.9 mn sq ft) in Delhi NCR and NH-16 (0.7 mn sq ft) in Chennai. These three micro markets accounted for significant leasing share in their respective cities during the quarter.

Engineering and e-commerce players drove the bulk of leasing during the quarter, together accounting for about 46 per cent of the demand. With about 2.2 million sq ft of leasing, engineering firms alone accounted for about one-fourth of the Grade A industrial & warehousing demand in Q1 2025. The sector saw over 2X times growth in leasing activity on an annual basis, led by robust demand in Chennai and Bengaluru. E-commerce also saw close to 2 million sq ft of leasing, led by Delhi NCR and Mumbai. Bolstered by institutional capital deployment, improved last-mile delivery, and increasing consumer trust, e-commerce in India is expected to maintain a strong upward trajectory in the coming years. This would further fuel demand for warehousing spaces across Tier I and II markets in the country.

“The strong industrial & warehousing space uptake in the first quarter of 2025 was marked by robust demand across diverse occupier sectors. Engineering and e-commerce sectors emerged as key demand drivers, followed by 3PL, with each recording close to 2 million sq ft of quarterly demand or more. Automobile players also picked up significant Grade A industrial & warehousing space at 1.3 million sq ft. These are healthy signs of overall growth, reflecting broad-based demand which aligns with domestic macro-economic indicators.” says Vijay Ganesh, Managing Director, Industrial & Logistics Services, Colliers India.

With 9 million sq ft of leasing in Q1 2025 at a 15 per cent Y-o-Y growth, industrial & warehousing demand across the top eight cities remained robust. Delhi NCR and Chennai led the demand, cumulatively accounting for around 57 per cent of the overall leasing in Q1 2025. The demand for Grade A industrial & warehousing space was particularly impressive in Delhi NCR; the city has already witnessed about half of the leasing activity of 2024 in the first quarter of 2025 alone. Interestingly, across the top eight cities, engineering sector drove demand this quarter, contributing to about 25 per cent of the overall industrial & warehousing space uptake, followed by e-commerce with 21 per cent share. Both these sectors have surpassed the demand from Third Party Logistics (3PL) players, the usual frontrunner. While Chennai and Bengaluru saw strong traction from occupiers in the engineering space, demand from e-commerce players remained significant in Delhi NCR and Mumbai. At a micro market level, Bhiwandi in Mumbai led leasing activity in the first quarter with about 1.0 million sq ft of demand, followed by Luhari (0.9 mn sq ft) in Delhi NCR and NH-16 (0.7 mn sq ft) in Chennai. These three micro markets accounted for significant leasing share in their respective cities during the quarter. Engineering and e-commerce players drove the bulk of leasing during the quarter, together accounting for about 46 per cent of the demand. With about 2.2 million sq ft of leasing, engineering firms alone accounted for about one-fourth of the Grade A industrial & warehousing demand in Q1 2025. The sector saw over 2X times growth in leasing activity on an annual basis, led by robust demand in Chennai and Bengaluru. E-commerce also saw close to 2 million sq ft of leasing, led by Delhi NCR and Mumbai. Bolstered by institutional capital deployment, improved last-mile delivery, and increasing consumer trust, e-commerce in India is expected to maintain a strong upward trajectory in the coming years. This would further fuel demand for warehousing spaces across Tier I and II markets in the country. “The strong industrial & warehousing space uptake in the first quarter of 2025 was marked by robust demand across diverse occupier sectors. Engineering and e-commerce sectors emerged as key demand drivers, followed by 3PL, with each recording close to 2 million sq ft of quarterly demand or more. Automobile players also picked up significant Grade A industrial & warehousing space at 1.3 million sq ft. These are healthy signs of overall growth, reflecting broad-based demand which aligns with domestic macro-economic indicators.” says Vijay Ganesh, Managing Director, Industrial & Logistics Services, Colliers India.

Related Stories

Gold Stories

Next Story
Infrastructure Urban

Infrastructure Opportunity Outlook by IMPACCT.Info

India’s infrastructure pipeline is witnessing dynamic activity across stages — from immediate bidding to future planning. IMPACCT segments these into three categories: Immediate, 3–6 Month, and Future Opportunities, enabling businesses to identify, prepare, and participate in high-value tenders and projects across sectors.To read full article Click Here ..
Next Story
Real Estate

Glass, Reframed!

Glass façades, quintessential aesthetic building envelopes globally, have been widely adopted in India as well. But when the focus is high-performance building systems that deliver energy efficiency, comfort and architectural identity, glass isn’t the only preference. Combination solutions, involving glass and some other material, improve façade outcomes. Some combinations come at comparable prices, some at a higher price. Here is a selection of performance-oriented solutions...To read the full story Click Here ..
Next Story
Infrastructure Urban

Beyond Building Faster

India’s cities are expanding at an unprecedented pace, bringing new infrastructure and development opportunities while also intensifying challenges around mobility, public spaces, liveability and supporting infrastructure. The question, therefore, is not simply whether India can build faster, but whether it can build cities that work better.At a CW webinar, Are We Designing Better Cities – or Just Building Faster?, moderator Ar. Samir Shaikh, Founding Principal, AR&UD Studio, brought together perspectives from design, development, master planning and technology...To read the full artic..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code