- Home
- Real Estate
- Mezzanine capital typically targets an IRR return from 18% to 24%
Mezzanine capital typically targets an IRR return from 18% to 24%
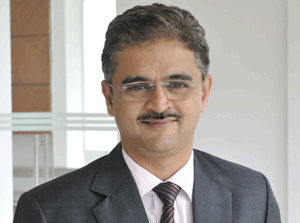
Here´s an investment bank that thrives on crucial decision-making, accelerated timelines, transactions of significant complexities and colossal stakes. With key partners, Ambit Corporate Finance has created a niche for itself as one of the top investment banks in India. With a distinguished client portfolio that constitutes the who's who of Indian business groups, varied sectoral expertise and a strong knowledge of the legal and regulatory framework in India, Ambit Corporate Finance´s investment banking services provides insightful solutions to clients in mergers and acquisitions (M&A), equity capital markets and alternate capital raising. Chetas Desai, CEO, Ambit Corporate Finance, shares more on the current scenario in conversation with SHRIYAL SETHUMADHAVAN.
Tell us about Ambit Corporate Finance´s contribution to the infrastructure and real-estate sectors. What support have you offered to important projects?
Ambit Corporate Finance has played the role of being a sell-side advisor to several large owners of real estate in the Greater Metropolitan area. We advised Borosil and multinationals such as Bayer CropScience and, most recently, Clariant Chemicals for divestment of their real-estate assets. These transactions altogether aggregate to 200 plus acre of real estate, which are now at various stages of being developed into large township projects with their own self-sustained infrastructure.
What are the various channels available for raising funds through Ambit Corporate Finance?
The company can help real estate or infrastructure companies raise equity and mezzanine capital from private equity (PE) players. Mezzanine capital is a mode of financing that is linked only to projects and is easy for people to define. One raises money at a different price where the thought is that the return is better or the risk is not that significant to bear that cost. So, this becomes a bit expensive at times and this is not equity in nature as the project itself is supposed to deliver the cash flow; whereas in equity, it is difficult to derive the money from the project itself. Hence, mezzanine capital is many times the right path in real-estate development projects. However, the equity capital markets practice can help listed real-estate or infrastructure players raise capital from the public markets via initial public offerings (IPOs) and QIPs.
How suitable is the current market for IPOs? What are the prospects for fresh IPOs in the infrastructure sector?
The IPO market has been muted for the past few years. However, the recent Wonderla Holidays Rs 180-crore IPO has been a positive development. And, a stable government and favourable long-term economic policies are the keys to boost the sentiment in the IPO market. With the elections just conducted, a stable government with a long-term focus will definitely augur well for the sector. We are looking at much more positive times, especially with the mandate the BJP and its allies have got. This should turn the investment cycle very positively in the next couple of years.
Speaking of M&As and divestitures, Ambit is adept with hands-on experience in managing complex transactions. Are you sharing any expertise with the Government of India?
Ambit is a Tier-I merchant banker regulated by SEBI. Typically, before enactment of new regulation or modification to the existing framework, SEBI may release a discussion paper on the subject, seeking comments from several market intermediaries. Accordingly, Ambit may comment on these aspects, considering our past experience in managing complex transactions.
What is happening at present in the M&A deals scenario?
In terms of real estate, the M&A really happens in the context of the real-estate asset, which is land. This is fundamentally a capital asset for the seller, but a working capital asset for the buyer. Slowly and steadily, people realise that they are not really in the position to themselves realise that asset. But this requires different business and financial capabilities, and when one wants to realise the asset, that´s when the M&A opportunity arises.
As the industry continues to complain about lack of funding, is there an alternative source for funding? That said, how do you view mezzanine funds as an alternative for infra or real-estate financing?
Real-estate financing from the banking sector is largely restricted to construction finance for funding under construction projects. Over the years, NBFC players have filled in the gap of funding projects that are at a pre-approval stage. Ambit also has a separate NBFC arm that provides debt and undertakes debt syndication for promoters of listed and unlisted entities across all sectors including infrastructure. Currently, most PE players offer mezzanine capital to the real-estate or infrastructure projects at the special purpose vehicle (SPV) level. Depending on the project and the type of collateral offered, mezzanine capital typically targets an IRR return ranging from 18 per cent to 24 per cent.
Many real-estate companies are raising capital from NBFCs and PE funds to refinance previous loans, repay banks or pave the way for exits by investors.
What is your assessment of the performance of PE funds? What is your outlook for them?
Private equity capital in the real-estate space is available mostly in the form of mezzanine capital. PE investors are seeking to invest in project SPVs, considering an IRR-based return structure. Given the nature of the projects and the regulatory regime, NBFCs and PE funds are the most appropriate to channel funds to the sector. We believe that as both parties gain experience, this channel will only grow. These funds typically earn a return ranging from 18 per cent to 24 per cent, depending on the type of project, promoter and the collateral offered. Going forward, we expect more deals to be structured on similar lines rather than plain vanilla equity.
In times of difficulties like the infrastructure sector is facing in the present day, what does a finance corporation do? What are the measures taken at your end?
On account of the regulatory bottlenecks faced by the infrastructure sector, this sector has been through one of the worst cycles during the past two to three years. There is a clear recognition that this cannot continue as the sector itself is too huge and important to be ignored. After elections, we expect the cycle to reverse. Already a couple of big-ticket M&A deals $104 million Greenko-Lanco and $1.6 billion TAQA-JP Hydro have been announced in the past three months signalling a revival in the sector and a change in sentiment. We believe this sector holds high potential from an M&A and capital raising perspective over the next five years. We, at Ambit, are watching this space closely and will increase focus on this sector.
Ambit Corporate Finance:
Services Offered
M&As and Divestitures
Ambit is adept with hands-on experience in managing complex transactions including business mergers of listed entities, global inbound and outbound acquisitions, corporate acquisitions and mergers, domestic consolidations, friendly and hostile takeovers, bid defense, shareholder reorganisation of Indian business groups, and global conglomerates operating in India.
Alternate Capital Raising
The company has pioneered strong relationships with private capital providers: global PE funds, India focused PE funds, real estate funds, FIIs, mezzanine funds, hedge funds and global banks. It identifies the right capital for the clients across products and addresses the clients´ capital needs such as acquisition financing, buyouts, leverage buyouts, growth capital, distressed assets financing, recapitalisation, pre-IPO placements, shareholder financing, etc.
Equity Capital Markets
The company supports its client´s acquisitions and growth by raising capital through its access to public markets. Furthermore, Ambit leverages its acclaimed regulatory and procedural know-how to create innovative structures aligned to specific business plans. It also provides advisory and merchant banking services related to IPOs, qualified institutional placements, FCCBs, right issues, open offers under the SEBI takeover code, delisting offers, buy-back offers and equity placements.
To share your lending experience, write in at feedback@ASAPPmedia.com

Chetas Desai, CEO, Ambit Corporate Finance Here´s an investment bank that thrives on crucial decision-making, accelerated timelines, transactions of significant complexities and colossal stakes. With key partners, Ambit Corporate Finance has created a niche for itself as one of the top investment banks in India. With a distinguished client portfolio that constitutes the who's who of Indian business groups, varied sectoral expertise and a strong knowledge of the legal and regulatory framework in India, Ambit Corporate Finance´s investment banking services provides insightful solutions to clients in mergers and acquisitions (M&A), equity capital markets and alternate capital raising. Chetas Desai, CEO, Ambit Corporate Finance, shares more on the current scenario in conversation with SHRIYAL SETHUMADHAVAN. Tell us about Ambit Corporate Finance´s contribution to the infrastructure and real-estate sectors. What support have you offered to important projects? Ambit Corporate Finance has played the role of being a sell-side advisor to several large owners of real estate in the Greater Metropolitan area. We advised Borosil and multinationals such as Bayer CropScience and, most recently, Clariant Chemicals for divestment of their real-estate assets. These transactions altogether aggregate to 200 plus acre of real estate, which are now at various stages of being developed into large township projects with their own self-sustained infrastructure. What are the various channels available for raising funds through Ambit Corporate Finance? The company can help real estate or infrastructure companies raise equity and mezzanine capital from private equity (PE) players. Mezzanine capital is a mode of financing that is linked only to projects and is easy for people to define. One raises money at a different price where the thought is that the return is better or the risk is not that significant to bear that cost. So, this becomes a bit expensive at times and this is not equity in nature as the project itself is supposed to deliver the cash flow; whereas in equity, it is difficult to derive the money from the project itself. Hence, mezzanine capital is many times the right path in real-estate development projects. However, the equity capital markets practice can help listed real-estate or infrastructure players raise capital from the public markets via initial public offerings (IPOs) and QIPs. How suitable is the current market for IPOs? What are the prospects for fresh IPOs in the infrastructure sector? The IPO market has been muted for the past few years. However, the recent Wonderla Holidays Rs 180-crore IPO has been a positive development. And, a stable government and favourable long-term economic policies are the keys to boost the sentiment in the IPO market. With the elections just conducted, a stable government with a long-term focus will definitely augur well for the sector. We are looking at much more positive times, especially with the mandate the BJP and its allies have got. This should turn the investment cycle very positively in the next couple of years. Speaking of M&As and divestitures, Ambit is adept with hands-on experience in managing complex transactions. Are you sharing any expertise with the Government of India? Ambit is a Tier-I merchant banker regulated by SEBI. Typically, before enactment of new regulation or modification to the existing framework, SEBI may release a discussion paper on the subject, seeking comments from several market intermediaries. Accordingly, Ambit may comment on these aspects, considering our past experience in managing complex transactions. What is happening at present in the M&A deals scenario? In terms of real estate, the M&A really happens in the context of the real-estate asset, which is land. This is fundamentally a capital asset for the seller, but a working capital asset for the buyer. Slowly and steadily, people realise that they are not really in the position to themselves realise that asset. But this requires different business and financial capabilities, and when one wants to realise the asset, that´s when the M&A opportunity arises. As the industry continues to complain about lack of funding, is there an alternative source for funding? That said, how do you view mezzanine funds as an alternative for infra or real-estate financing? Real-estate financing from the banking sector is largely restricted to construction finance for funding under construction projects. Over the years, NBFC players have filled in the gap of funding projects that are at a pre-approval stage. Ambit also has a separate NBFC arm that provides debt and undertakes debt syndication for promoters of listed and unlisted entities across all sectors including infrastructure. Currently, most PE players offer mezzanine capital to the real-estate or infrastructure projects at the special purpose vehicle (SPV) level. Depending on the project and the type of collateral offered, mezzanine capital typically targets an IRR return ranging from 18 per cent to 24 per cent. Many real-estate companies are raising capital from NBFCs and PE funds to refinance previous loans, repay banks or pave the way for exits by investors. What is your assessment of the performance of PE funds? What is your outlook for them? Private equity capital in the real-estate space is available mostly in the form of mezzanine capital. PE investors are seeking to invest in project SPVs, considering an IRR-based return structure. Given the nature of the projects and the regulatory regime, NBFCs and PE funds are the most appropriate to channel funds to the sector. We believe that as both parties gain experience, this channel will only grow. These funds typically earn a return ranging from 18 per cent to 24 per cent, depending on the type of project, promoter and the collateral offered. Going forward, we expect more deals to be structured on similar lines rather than plain vanilla equity. In times of difficulties like the infrastructure sector is facing in the present day, what does a finance corporation do? What are the measures taken at your end? On account of the regulatory bottlenecks faced by the infrastructure sector, this sector has been through one of the worst cycles during the past two to three years. There is a clear recognition that this cannot continue as the sector itself is too huge and important to be ignored. After elections, we expect the cycle to reverse. Already a couple of big-ticket M&A deals $104 million Greenko-Lanco and $1.6 billion TAQA-JP Hydro have been announced in the past three months signalling a revival in the sector and a change in sentiment. We believe this sector holds high potential from an M&A and capital raising perspective over the next five years. We, at Ambit, are watching this space closely and will increase focus on this sector. Ambit Corporate Finance: Services Offered M&As and Divestitures Ambit is adept with hands-on experience in managing complex transactions including business mergers of listed entities, global inbound and outbound acquisitions, corporate acquisitions and mergers, domestic consolidations, friendly and hostile takeovers, bid defense, shareholder reorganisation of Indian business groups, and global conglomerates operating in India. Alternate Capital Raising The company has pioneered strong relationships with private capital providers: global PE funds, India focused PE funds, real estate funds, FIIs, mezzanine funds, hedge funds and global banks. It identifies the right capital for the clients across products and addresses the clients´ capital needs such as acquisition financing, buyouts, leverage buyouts, growth capital, distressed assets financing, recapitalisation, pre-IPO placements, shareholder financing, etc. Equity Capital Markets The company supports its client´s acquisitions and growth by raising capital through its access to public markets. Furthermore, Ambit leverages its acclaimed regulatory and procedural know-how to create innovative structures aligned to specific business plans. It also provides advisory and merchant banking services related to IPOs, qualified institutional placements, FCCBs, right issues, open offers under the SEBI takeover code, delisting offers, buy-back offers and equity placements. To share your lending experience, write in at feedback@ASAPPmedia.com

Related Stories
Gold Stories
Embraer to Acquire 51 Per Cent Stake in Mahindra Aerospace Arm
Brazilian aerospace major Embraer will acquire a 51 per cent equity stake in Novavayu Aerospace, a step-down subsidiary of Mahindra and Mahindra, under an Investment Agreement notified by the automobile company in an exchange filing. The transaction will give Embraer control of the aerospace business. Following completion of the acquisition, Novavayu Aerospace will cease to be a wholly owned subsidiary and become an associate of Mahindra Defence Systems, which is a step-down wholly owned subsidiary of Mahindra and Mahindra. The agreement is expected to be completed on or before December 1. Mah..
RBI Opens Special Dollar Window for Three State-Run OMCs
The Reserve Bank of India (RBI) has opened a special facility to meet the entire daily US dollar requirements of three public sector oil marketing companies (OMCs), in a move aimed at easing pressure on the Indian rupee. The facility will take effect on October 12, 2026, and remain available until further notice. Indian Oil Corporation, Hindustan Petroleum Corporation and Bharat Petroleum Corporation are eligible to use the arrangement. Under the facility, the RBI will sell US dollars to the three companies through designated banks, allowing them to meet their oil-import payments without sourc..
Cement Prices Likely to Rise Rs. 10-15 per Bag from Mid-October
Cement manufacturers in India are likely to raise prices by Rs. 10-15 per bag from mid-October, as they seek to offset persistent increases in power and fuel costs. Emkay Research said its channel checks indicated a high probability of an increase from October 12, supported by the start of the busy construction season and favourable demand-supply conditions. The sector had implemented similar rate adjustments of Rs. 10-15 per bag during the first quarter, but the increases were insufficient to cover higher operating costs. Prices also softened during July and August because of the monsoon, wid..
Related Articles
Latest Updates
Recommended for you
Advertisement
Subscribe to Our Newsletter
Get daily newsletters around different themes from Construction world.
subscribe to the newsletter
Don't miss out on valuable insights and opportunities
to connect with like minded professionals