Indian cement industry to add 80 mt cement capacity through FY24
Cement

Indian cement industry to add 80 mt cement capacity through FY24

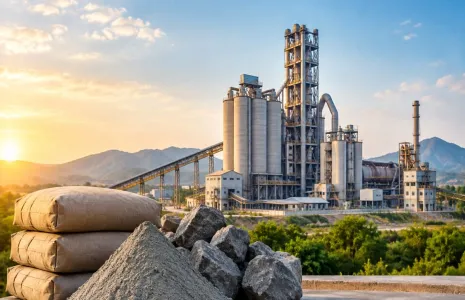
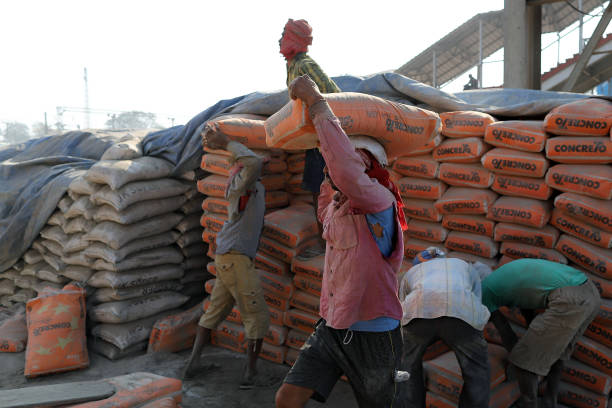
With a healthy growth outlook, the cement industry is stepping up capacity additions, with 80 mt expected over the next three fiscal years, a quarter more than in the previous three fiscals 64 mt.

The top ten players will gain market share as they add 70% of new capacity. In addition, lower project risks and funding of this capital expenditure through internal accruals will help them maintain a strong credit profile.

Due to a resurgence in infrastructure and housing spending, cement demand is expected to increase by over 10% this fiscal year, after remaining flat the previous fiscal year. The government's increased focus on roads and railways, as well as the resumption of housing construction, will drive cement consumption higher this fiscal year.

Given the government's continued focus on infrastructure, the medium-term demand outlook is also positive (through the building of roads, metros and railways).

Nearly 68% of the 19.5 million affordable housing units targeted under PMAY-R have yet to be built (as of this fiscal year), and cement demand is expected to rise as these units are built over the next two to three fiscal years.

The capacity addition will be skewed, with nearly 45 to 47 mt added in the eastern and central regions, owing to these regions' strong demand scenarios and higher current utilisations of 72%.

In comparison, due to excess supply and lower utilisation levels of 54%, the south is only expected to add 6 to 7 mt.

Nearly 60% of the new capacity will be brownfield, meaning enhancements at the same location, lowering capital costs by 40 to 50% to Rs 4,100 to 4,600 per tonne and overall costs to around Rs 25,000 to 26,000 crore for the top ten players.

This will also result in better absorption of fixed costs such as manpower, common infrastructure, and overheads, as well as a reduction in the risks associated with land acquisition, regulatory approvals, and implementation.

By March 31, nearly Rs 5,500 to 5,600 crore had been spent out of the total budget. Internal cash accruals of at least Rs 50,000 crore are expected to be generated over the next three fiscal years to cover the shortfall.

These companies' Capex plans are also supported by sustained cash liquidity of more than Rs 30,000 crore as of March.

Overall, according to CRISIL, with no material increase in debt, these players' credit profiles will remain strong. Furthermore, by fiscal 2024, six of the top ten players are expected to be debt-free, compared to four at the end of fiscal 2021.

Image Source


Also read: Cement manufacturers eye expansion in eastern India

With a healthy growth outlook, the cement industry is stepping up capacity additions, with 80 mt expected over the next three fiscal years, a quarter more than in the previous three fiscals 64 mt. The top ten players will gain market share as they add 70% of new capacity. In addition, lower project risks and funding of this capital expenditure through internal accruals will help them maintain a strong credit profile. Due to a resurgence in infrastructure and housing spending, cement demand is expected to increase by over 10% this fiscal year, after remaining flat the previous fiscal year. The government's increased focus on roads and railways, as well as the resumption of housing construction, will drive cement consumption higher this fiscal year. Given the government's continued focus on infrastructure, the medium-term demand outlook is also positive (through the building of roads, metros and railways). Nearly 68% of the 19.5 million affordable housing units targeted under PMAY-R have yet to be built (as of this fiscal year), and cement demand is expected to rise as these units are built over the next two to three fiscal years. The capacity addition will be skewed, with nearly 45 to 47 mt added in the eastern and central regions, owing to these regions' strong demand scenarios and higher current utilisations of 72%. In comparison, due to excess supply and lower utilisation levels of 54%, the south is only expected to add 6 to 7 mt. Nearly 60% of the new capacity will be brownfield, meaning enhancements at the same location, lowering capital costs by 40 to 50% to Rs 4,100 to 4,600 per tonne and overall costs to around Rs 25,000 to 26,000 crore for the top ten players. This will also result in better absorption of fixed costs such as manpower, common infrastructure, and overheads, as well as a reduction in the risks associated with land acquisition, regulatory approvals, and implementation. By March 31, nearly Rs 5,500 to 5,600 crore had been spent out of the total budget. Internal cash accruals of at least Rs 50,000 crore are expected to be generated over the next three fiscal years to cover the shortfall. These companies' Capex plans are also supported by sustained cash liquidity of more than Rs 30,000 crore as of March. Overall, according to CRISIL, with no material increase in debt, these players' credit profiles will remain strong. Furthermore, by fiscal 2024, six of the top ten players are expected to be debt-free, compared to four at the end of fiscal 2021. Image Source Also read: Cement manufacturers eye expansion in eastern India

Related Stories

Gold Stories
Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code