Cement demand to grow 7-8% this fiscal, profitability strong: CRISIL
Cement

Cement demand to grow 7-8% this fiscal, profitability strong: CRISIL

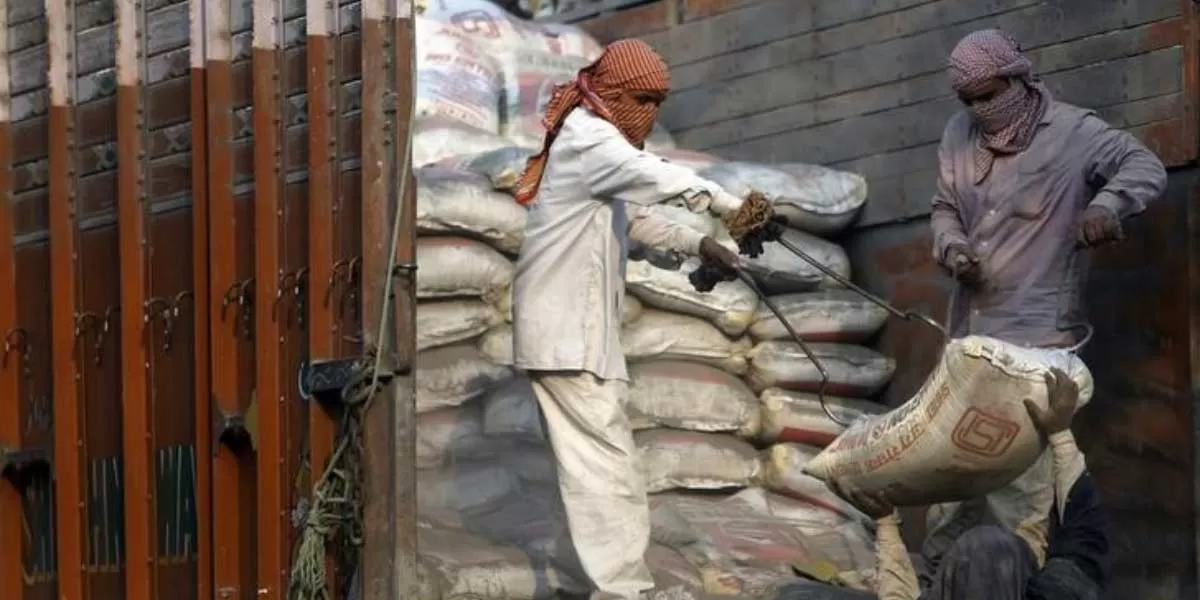
The demand for cement in India is projected to grow by 7-8% this fiscal year, reaching 475 million tons (MT), following a compound annual growth rate (CAGR) of 11% from FY22 to FY24, according to a report by CRISIL. Despite a slow start, the operating profitability of cement companies is expected to remain between Rs 975 and Rs 1,000 per tonne, exceeding the decade average of Rs 963 per tonne. Stable credit profiles and robust balance sheets will further support the industry’s financial health.

In a press release, CRISIL noted that cement demand grew by only 3% in the first quarter of FY24 due to labour shortages during the general elections and the extended heatwave. A similar trend is expected for the second quarter, attributed to seasonal factors. However, demand is likely to rebound in the second half of the fiscal year, which typically accounts for the majority of annual sales.

“Post-monsoon, construction activity across infrastructure and housing is expected to pick up, leading to a 9-11% growth in the second half,” said Sehul Bhatt, Director of CRISIL Market Intelligence and Analytics. He also highlighted that favourable weather, improved labour availability post-festive season, and increased government spending—particularly under the Pradhan Mantri Awas Yojana—will drive this recovery.

Government infrastructure spending, which constitutes around 30% of cement demand, will play a key role in sustaining growth. Although real spending was sluggish until July, capital expenditures are expected to accelerate in the third quarter. The Union Budget’s 6% rise in allocations for infrastructure-related sectors will further support the demand for cement.

Ankit Kedia, Director of CRISIL Ratings, added that production costs are likely to decline, with power and fuel costs—nearly 30% of the total cost—expected to drop by Rs 135-145 per tonne due to stable coal and pet coke prices. Additionally, operating leverage benefits of approximately Rs 30 per tonne are anticipated as volume growth aligns with new capacity additions, maintaining strong utilisation levels.

The report concluded that consistent profitability, volume expansion, and solid liquidity will ensure cash flows remain robust. Financial leverage across the industry is expected to stay below 0.5 times current levels, reflecting sound capital structures. As a result, credit profiles of cement manufacturers are projected to remain stable throughout the fiscal year.

The demand for cement in India is projected to grow by 7-8% this fiscal year, reaching 475 million tons (MT), following a compound annual growth rate (CAGR) of 11% from FY22 to FY24, according to a report by CRISIL. Despite a slow start, the operating profitability of cement companies is expected to remain between Rs 975 and Rs 1,000 per tonne, exceeding the decade average of Rs 963 per tonne. Stable credit profiles and robust balance sheets will further support the industry’s financial health. In a press release, CRISIL noted that cement demand grew by only 3% in the first quarter of FY24 due to labour shortages during the general elections and the extended heatwave. A similar trend is expected for the second quarter, attributed to seasonal factors. However, demand is likely to rebound in the second half of the fiscal year, which typically accounts for the majority of annual sales. “Post-monsoon, construction activity across infrastructure and housing is expected to pick up, leading to a 9-11% growth in the second half,” said Sehul Bhatt, Director of CRISIL Market Intelligence and Analytics. He also highlighted that favourable weather, improved labour availability post-festive season, and increased government spending—particularly under the Pradhan Mantri Awas Yojana—will drive this recovery. Government infrastructure spending, which constitutes around 30% of cement demand, will play a key role in sustaining growth. Although real spending was sluggish until July, capital expenditures are expected to accelerate in the third quarter. The Union Budget’s 6% rise in allocations for infrastructure-related sectors will further support the demand for cement. Ankit Kedia, Director of CRISIL Ratings, added that production costs are likely to decline, with power and fuel costs—nearly 30% of the total cost—expected to drop by Rs 135-145 per tonne due to stable coal and pet coke prices. Additionally, operating leverage benefits of approximately Rs 30 per tonne are anticipated as volume growth aligns with new capacity additions, maintaining strong utilisation levels. The report concluded that consistent profitability, volume expansion, and solid liquidity will ensure cash flows remain robust. Financial leverage across the industry is expected to stay below 0.5 times current levels, reflecting sound capital structures. As a result, credit profiles of cement manufacturers are projected to remain stable throughout the fiscal year.

Related Stories

Gold Stories

Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code