+
Resilient demand, moderate capacity addition, tapering costs
Cement

Resilient demand, moderate capacity addition, tapering costs

India Ratings and Research (Ind-Ra) has maintained a stable outlook on the cement sector for FY2020. Cement manufacturers are poised to benefit from the continuing demand push, led by the healthy growth expected across end-markets such as individual home building, affordable housing, roads and irrigation sectors. The agency expects the momentum to continue in FY2020, propelled by government-led spends in roads and affordable housing schemes. Utilisations are likely to rise but not to the extent that producers would see any increase in pricing power. However, cost pressures will reduce because of stabilisations in input costs and currency movements. This coupled with cost-saving measures could lead to a modest improvement in margins in FY2020.
 
Ind-Ra expects cement demand to grow by a modest 6 per cent to 8 per cent over the next year, driven by the diminishing base effect, increased thrust on infrastructure by the Central Government and various state governments, and the affordable housing segment.
Over the past three quarters, the profitability (EBITDA/tonne) of cement companies has been tested by the increasing costs of inputs, especially power, fuel and freight, as the players have not been able to pass on the rise in full to the customers due to the demand-supply imbalance. Consequently, the companies are expected to post poor results in FY2019. However, considering the downtrend in fuel prices since October 2018, Ind-Ra expects the cost headwinds to moderate in FY2020. This would lend further support to the margins.

The credit metrics of cement manufacturers are likely to deteriorate in FY2019 on account of mergers and acquisitions, high capex and increased input cost. For the issuers rated by Ind-Ra, the net leverage positions are expected to improve, given their strong positions in the regions in which they operate and a stable-to-higher EBITDA per tonne due to steady cement prices and tapering input costs.
The agency believes the capacity utilisations of the cement industry would improve gradually over the next two years on account of limited capacity additions amid the turnaround of acquired assets. According to Ind-Ra, the sector will witness capacity addition of around 20 mtpa over FY2019-FY2021 (with higher addition in FY2020), and the capacity utilisation will increase by 120 bps and 200 bps in FY2020 and FY2021, respectively. Between 2008 and 2018, demand increased at 6.15 per cent CAGR, while capacity increased at 9 per cent CAGR. As a result, capacity utilisation rates dropped to 64 per cent in FY2018 from 83 per cent in FY2008, leading to increased competition and pressure on selling prices. Any further demand-supply imbalance at the regional level may impact the profitability of the players.

India Ratings and Research (Ind-Ra) has maintained a stable outlook on the cement sector for FY2020. Cement manufacturers are poised to benefit from the continuing demand push, led by the healthy growth expected across end-markets such as individual home building, affordable housing, roads and irrigation sectors. The agency expects the momentum to continue in FY2020, propelled by government-led spends in roads and affordable housing schemes. Utilisations are likely to rise but not to the extent that producers would see any increase in pricing power. However, cost pressures will reduce because of stabilisations in input costs and currency movements. This coupled with cost-saving measures could lead to a modest improvement in margins in FY2020. Ind-Ra expects cement demand to grow by a modest 6 per cent to 8 per cent over the next year, driven by the diminishing base effect, increased thrust on infrastructure by the Central Government and various state governments, and the affordable housing segment.Over the past three quarters, the profitability (EBITDA/tonne) of cement companies has been tested by the increasing costs of inputs, especially power, fuel and freight, as the players have not been able to pass on the rise in full to the customers due to the demand-supply imbalance. Consequently, the companies are expected to post poor results in FY2019. However, considering the downtrend in fuel prices since October 2018, Ind-Ra expects the cost headwinds to moderate in FY2020. This would lend further support to the margins.The credit metrics of cement manufacturers are likely to deteriorate in FY2019 on account of mergers and acquisitions, high capex and increased input cost. For the issuers rated by Ind-Ra, the net leverage positions are expected to improve, given their strong positions in the regions in which they operate and a stable-to-higher EBITDA per tonne due to steady cement prices and tapering input costs.The agency believes the capacity utilisations of the cement industry would improve gradually over the next two years on account of limited capacity additions amid the turnaround of acquired assets. According to Ind-Ra, the sector will witness capacity addition of around 20 mtpa over FY2019-FY2021 (with higher addition in FY2020), and the capacity utilisation will increase by 120 bps and 200 bps in FY2020 and FY2021, respectively. Between 2008 and 2018, demand increased at 6.15 per cent CAGR, while capacity increased at 9 per cent CAGR. As a result, capacity utilisation rates dropped to 64 per cent in FY2018 from 83 per cent in FY2008, leading to increased competition and pressure on selling prices. Any further demand-supply imbalance at the regional level may impact the profitability of the players.

Related Stories

Gold Stories
Next Story
Infrastructure Urban

Fieldmarshal Targets 10-15 Per Cent Share in Sub-20 HP Tractors

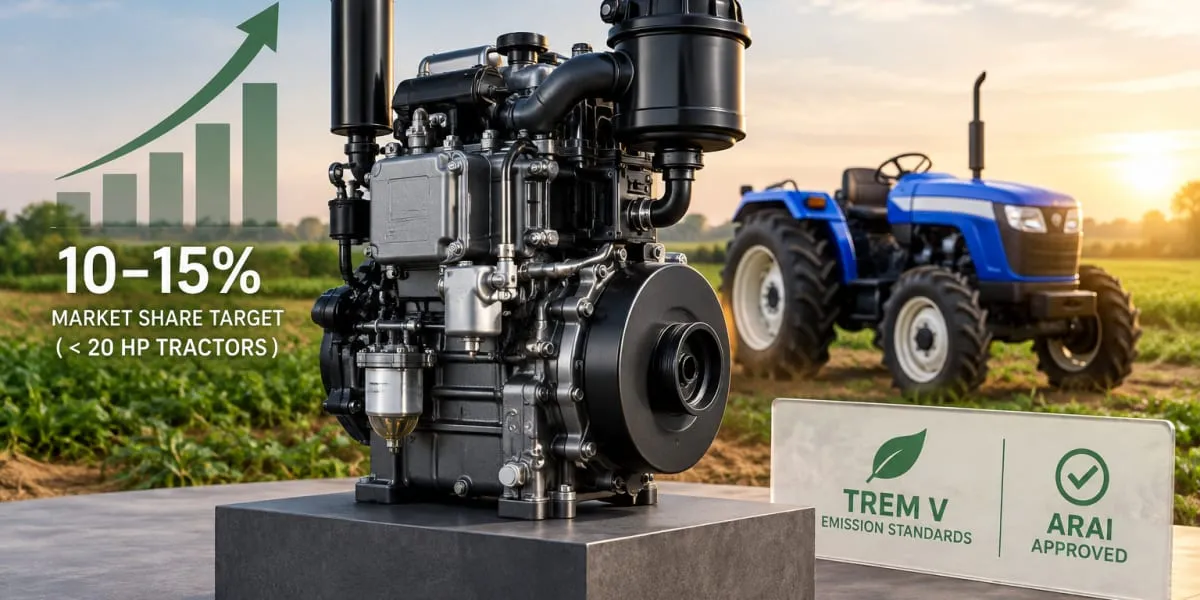
Rajkot-based diesel engine manufacturer Fieldmarshal PM Diesels has launched new single-cylinder diesel engines in the 15 HP and 18 HP categories as it targets a 10 to 15 per cent share of India’s below-20 HP tractor segment within three years. The engines comply with the latest Tractor Emission Stage V (TREM V) norms, which are equivalent to BS VI emission standards for vehicles, and have been approved by the Automotive Research Association of India (ARAI). The company said the products were developed for compact tractors and agricultural machinery, with a focus on fuel efficiency and durab..
Next Story
Infrastructure Energy

Coal India Supply to Power Sector Rises 11 Per Cent in Q2

State-owned Coal India (CIL) increased its supply of dry fuel to power-sector users by 11.01 per cent to 148.20 mn t in the second quarter of the current financial year, from 133.50 mn t in the year-ago period. The rise comes ahead of the festive season, when electricity demand generally increases. The higher supplies enabled CIL to liquidate around 63 mn t of coal stocks at its pitheads during the first six months of the current fiscal. The company had approximately 67 mn t available at its pitheads and said the inventory was adequate to meet power-sector requirements in the coming months. CI..
Next Story
Infrastructure Urban

Veerhealth Care Secures Rs. 45.47 mn Skincare Products Order

Veerhealth Care has received a domestic order from an unnamed fast-moving consumer goods (FMCG) company for the supply of face care products. The accepted value of the order is Rs. 45.47 mn, according to the company’s regulatory filing. The awarding entity was not disclosed because of confidential terms. Veerhealth Care is required to execute the order within 45 days of receiving it, covering the manufacture and supply of the specified face care products. The company said the order represented a significant business opportunity and anticipated that it would support additional growth in turno..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code