+
C&I Renewables To Reach 57 GW By FY28
POWER & RENEWABLE ENERGY

C&I Renewables To Reach 57 GW By FY28

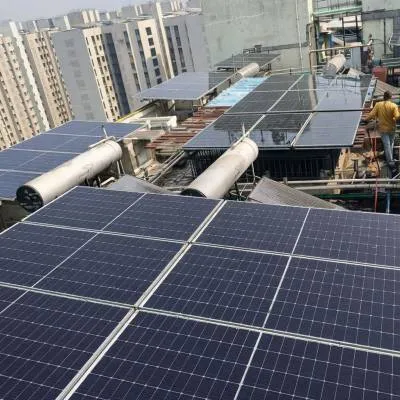
India's commercial and industrial renewable energy capacity is set to rise to 57 gigawatts (GW) by FY28, up from 40 GW expected by the end of FY26, marking a 17 GW addition in two years as corporate decarbonisation and tariff arbitrage drive demand. Crisil Ratings projects the expansion will be anchored by favourable long-term power purchase agreement tariffs vis-à-vis grid tariffs, corporate net-zero commitments, renewable purchase obligations and attractive developer returns. The report also identifies strong counterparty credit profiles as a key enabler of the market.

The Green Energy Open Access Rules, 2022, enabled industrial units and commercial establishments to source renewable power using transmission and distribution infrastructure, accelerating adoption in industrial states. States have announced policies to fast-track open access, offering rebates on cross-subsidy, wheeling and state transmission utility charges for intra-state sourcing, lowering the landed cost of power by 25 to 30 per cent versus on-grid tariffs. Such incentives have made C&I projects more financially attractive relative to utility-scale projects.

Energy-intensive sectors such as steel, cement and data centres are leading the shift as companies align procurement with internal net-zero targets and compliance obligations. Private equity-backed developers are expected to dominate additions, given higher returns on equity in C&I projects supported by better tariffs and counterparties with robust credit profiles. Crisil Ratings notes an average PPA tenure of around 15 years, about 65 per cent of rated capacity tied to counterparties with High Safety credit profiles and a weighted average debt service coverage ratio of 1.4 times over the next two fiscals.

Infrastructure constraints and policy continuity remain key risks, with limited intra-state transmission capacity and right-of-way issues affecting project timelines and costs. States must balance open access incentives against distribution utilities' revenue implications, and any recalibration of incentives could raise landed power costs even though tariffs are expected to remain competitive versus grid supply. With India targeting 500 GW of non-fossil capacity by 2030, the C&I segment is emerging as a pillar in meeting clean energy goals while offering returns to developers and cost savings to corporates.

India's commercial and industrial renewable energy capacity is set to rise to 57 gigawatts (GW) by FY28, up from 40 GW expected by the end of FY26, marking a 17 GW addition in two years as corporate decarbonisation and tariff arbitrage drive demand. Crisil Ratings projects the expansion will be anchored by favourable long-term power purchase agreement tariffs vis-à-vis grid tariffs, corporate net-zero commitments, renewable purchase obligations and attractive developer returns. The report also identifies strong counterparty credit profiles as a key enabler of the market. The Green Energy Open Access Rules, 2022, enabled industrial units and commercial establishments to source renewable power using transmission and distribution infrastructure, accelerating adoption in industrial states. States have announced policies to fast-track open access, offering rebates on cross-subsidy, wheeling and state transmission utility charges for intra-state sourcing, lowering the landed cost of power by 25 to 30 per cent versus on-grid tariffs. Such incentives have made C&I projects more financially attractive relative to utility-scale projects. Energy-intensive sectors such as steel, cement and data centres are leading the shift as companies align procurement with internal net-zero targets and compliance obligations. Private equity-backed developers are expected to dominate additions, given higher returns on equity in C&I projects supported by better tariffs and counterparties with robust credit profiles. Crisil Ratings notes an average PPA tenure of around 15 years, about 65 per cent of rated capacity tied to counterparties with High Safety credit profiles and a weighted average debt service coverage ratio of 1.4 times over the next two fiscals. Infrastructure constraints and policy continuity remain key risks, with limited intra-state transmission capacity and right-of-way issues affecting project timelines and costs. States must balance open access incentives against distribution utilities' revenue implications, and any recalibration of incentives could raise landed power costs even though tariffs are expected to remain competitive versus grid supply. With India targeting 500 GW of non-fossil capacity by 2030, the C&I segment is emerging as a pillar in meeting clean energy goals while offering returns to developers and cost savings to corporates.

Related Stories

Gold Stories
Next Story
Infrastructure Urban

KONE Opens India's First Digital Experience Centre in Pune

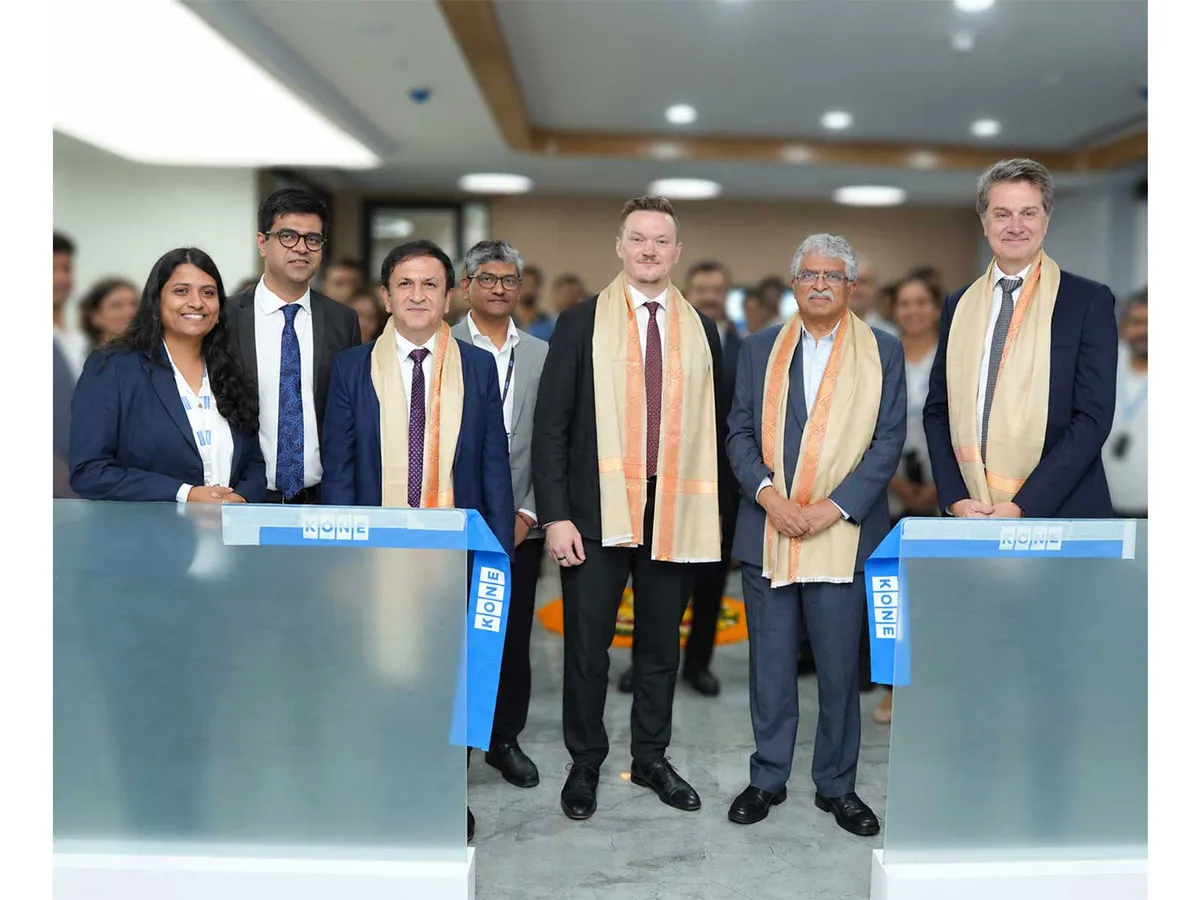
KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

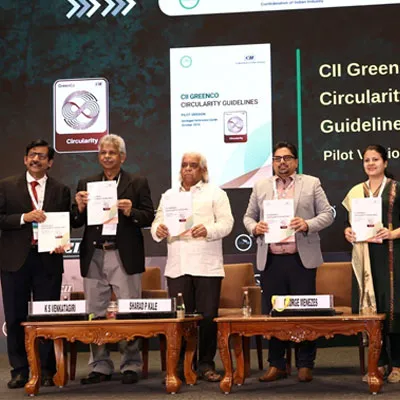
CII GreenCo Launches Circularity Guidelines for Indian Industry

The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

Global Electronics Association Launches IPC-1783-CO2E Standard

The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code