+
Brokerages Bullish on Vedanta’s FY26 Growth Prospects
ECONOMY & POLICY

Brokerages Bullish on Vedanta’s FY26 Growth Prospects

Major Indian and global brokerages remain optimistic about Vedanta Ltd’s performance for FY26, highlighting firm London Metal Exchange (LME) pricing, disciplined cost controls, a strong aluminium business, and deleveraging as the company’s key growth drivers.
Several upcoming growth projects, slated for commissioning over the next few quarters, also support the positive outlook.
JP Morgan reported that Vedanta’s consolidated EBITDA for Q1 was broadly in line with expectations. Segments such as aluminium, oil and gas, and power performed better than anticipated, resulting in a segmental EBITDA beat. The firm expects Vedanta’s ongoing initiatives, including capacity expansion and vertical integration in aluminium, to offer cost advantages and support earnings growth as LME prices trend upwards through FY26 and FY27.
Citi Research echoed similar views, adding that Vedanta Resources’ leverage remains comfortable. It cited medium-term upside in LME aluminium prices, lower costs, and the planned demerger as key positives. Citi also noted limited global aluminium supply growth.
Mumbai-based Nuvama Institutional Equities expects over 10 per cent quarter-on-quarter EBITDA growth in Q2FY26, driven by higher prices and lower aluminium production costs. It noted that major aluminium projects are likely to be commissioned in Q2FY26. Net debt to EBITDA (excluding Hindustan Zinc) is forecast to fall from 2.7x in FY25 to 1.7x by the end of FY26. The demerger is expected to conclude in Q4FY26.
All of Vedanta’s key projects, except its coal blocks, are expected to be commissioned in the current fiscal, offering improved volume and cost efficiency.
UK-based Investec, in its post-earnings note, identified Vedanta as a major beneficiary of the Indian Rupee’s depreciation. Other positives included falling alumina prices and attractive dividend yields. The firm maintained its ‘Buy’ rating on the stock.
Brokerages such as Kotak Institutional Equities and IIFL also highlighted the benefits of operational efficiencies and deleveraging across both Vedanta Ltd and its parent company.
Vedanta’s adjusted profit after tax rose 13 per cent year-on-year to Rs 500 billion. The company reported its highest-ever first-quarter EBITDA at Rs 1.0746 trillion, up 5 per cent from the previous year. 

Major Indian and global brokerages remain optimistic about Vedanta Ltd’s performance for FY26, highlighting firm London Metal Exchange (LME) pricing, disciplined cost controls, a strong aluminium business, and deleveraging as the company’s key growth drivers.Several upcoming growth projects, slated for commissioning over the next few quarters, also support the positive outlook.JP Morgan reported that Vedanta’s consolidated EBITDA for Q1 was broadly in line with expectations. Segments such as aluminium, oil and gas, and power performed better than anticipated, resulting in a segmental EBITDA beat. The firm expects Vedanta’s ongoing initiatives, including capacity expansion and vertical integration in aluminium, to offer cost advantages and support earnings growth as LME prices trend upwards through FY26 and FY27.Citi Research echoed similar views, adding that Vedanta Resources’ leverage remains comfortable. It cited medium-term upside in LME aluminium prices, lower costs, and the planned demerger as key positives. Citi also noted limited global aluminium supply growth.Mumbai-based Nuvama Institutional Equities expects over 10 per cent quarter-on-quarter EBITDA growth in Q2FY26, driven by higher prices and lower aluminium production costs. It noted that major aluminium projects are likely to be commissioned in Q2FY26. Net debt to EBITDA (excluding Hindustan Zinc) is forecast to fall from 2.7x in FY25 to 1.7x by the end of FY26. The demerger is expected to conclude in Q4FY26.All of Vedanta’s key projects, except its coal blocks, are expected to be commissioned in the current fiscal, offering improved volume and cost efficiency.UK-based Investec, in its post-earnings note, identified Vedanta as a major beneficiary of the Indian Rupee’s depreciation. Other positives included falling alumina prices and attractive dividend yields. The firm maintained its ‘Buy’ rating on the stock.Brokerages such as Kotak Institutional Equities and IIFL also highlighted the benefits of operational efficiencies and deleveraging across both Vedanta Ltd and its parent company.Vedanta’s adjusted profit after tax rose 13 per cent year-on-year to Rs 500 billion. The company reported its highest-ever first-quarter EBITDA at Rs 1.0746 trillion, up 5 per cent from the previous year. 

Related Stories

Gold Stories
Next Story
Real Estate

Peninsula Land launches 19 luxury villas in Pune

Pune’s residential landscape is witnessing a shift as premium homebuyers increasingly seek larger spaces, privacy and independent living options beyond high-rise apartments. Addressing this demand, Peninsula Land Limited, part of the Ashok Piramal Group, has launched AshokVillas, an exclusive collection of 19 premium furnished villas in Gahunje, Pune.The development combines the independence of a standalone home with the convenience and security of a managed residential community. Designed around low-density horizontal living, AshokVillas offers residents private spaces while providing acces..
Next Story
Infrastructure Urban

MyBranch Expands South India Network with 16 Workspace Centres

MyBranch has expanded its South India presence with a 50,000 sq ft flexible workspace network comprising 16 centres across 14 cities in Andhra Pradesh, Karnataka, Tamil Nadu and Telangana.The expansion reflects growing demand for flexible office infrastructure as businesses establish regional teams, satellite offices and operations beyond traditional metropolitan markets. MyBranch’s network spans Bengaluru, Coimbatore, Guntur, Hanamkonda, Hubballi, Hyderabad, Madurai, Mangaluru, Rajahmundry, Salem, Tirupati, Vellore, Vijayawada and Visakhapatnam, with a large office space in Chennai also und..
Next Story
Building Material

Walplast Launches Moisture-Resistant Gypsum Plaster Solutions

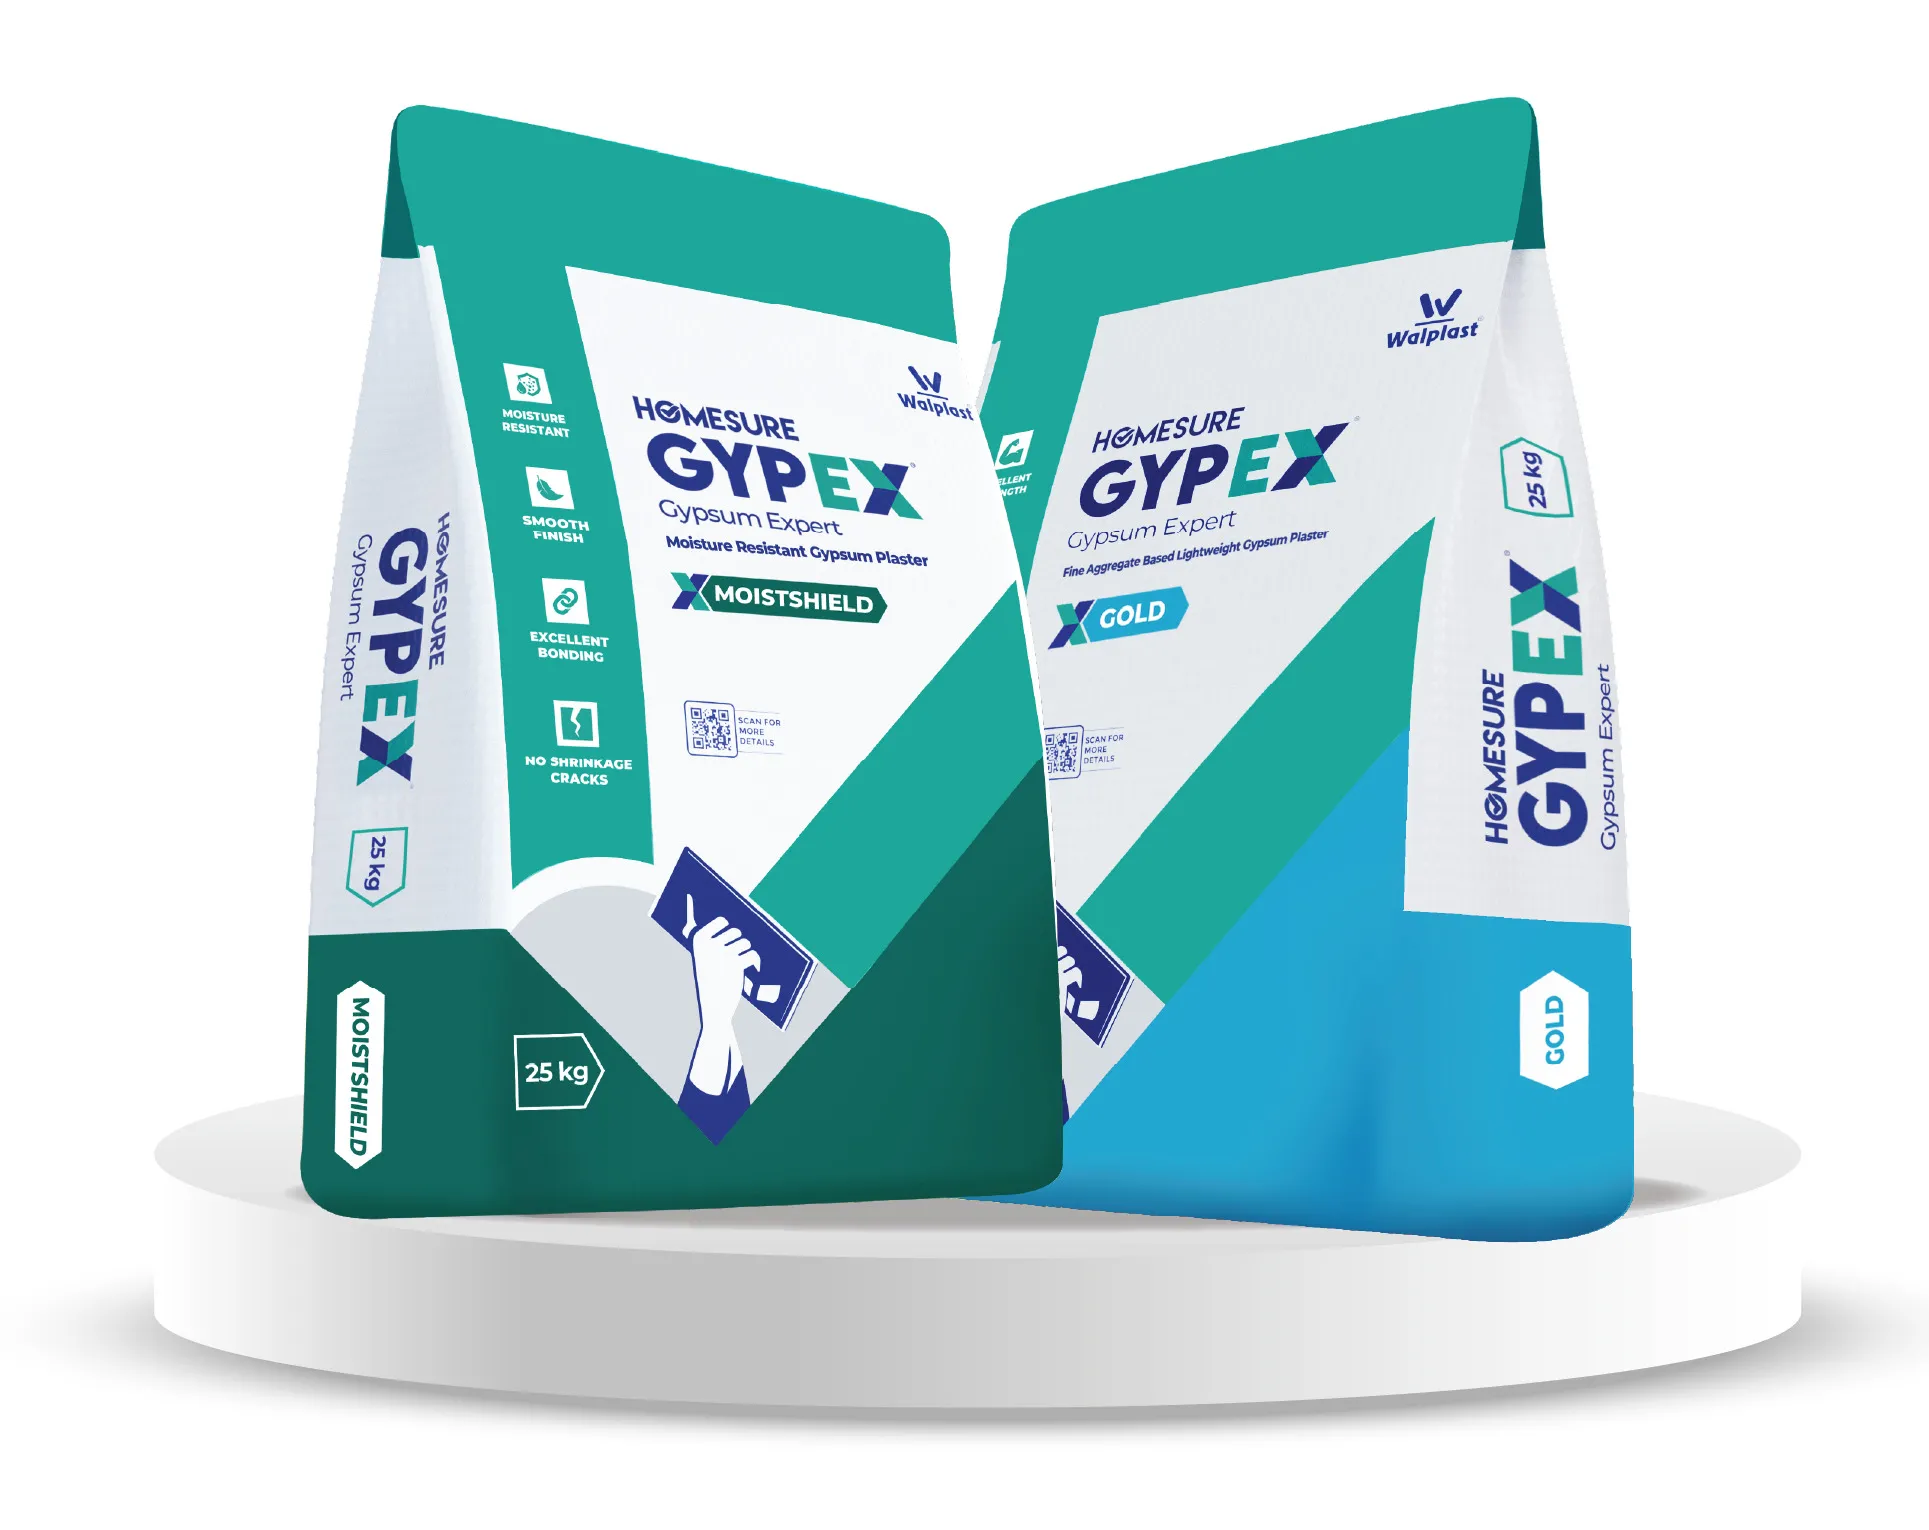
Walplast Products Pvt. Ltd. has expanded its HomeSure GypEx portfolio with the launch of GypEx MoistShield and GypEx Gold, two gypsum plaster solutions designed to address moisture-prone applications and improve plastering efficiency.The new products have been developed in response to the growing demand for faster construction processes, improved material performance and consistent surface quality. The solutions aim to simplify interior plastering while addressing specific application requirements across construction environments.“Through HomeSure GypEx MoistShield and GypEx Gold, we are exp..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code