+
Construction Sector Margins to Stay at 10.5–11% in FY25–26: ICRA
ECONOMY & POLICY

Construction Sector Margins to Stay at 10.5–11% in FY25–26: ICRA

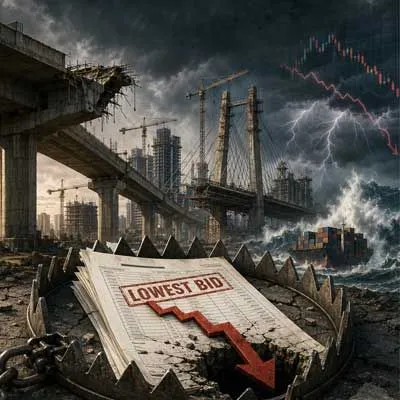
ICRA projects that the Construction industry's operating margins to remain range-bound at 10.5-11.0% in FY2025 and FY2026, supported by relatively stable input prices and benefits from operational leverage. However, this represents a moderation from the 13-14% levels seen in FY2021, as heightened competition across sub-sectors forces contractors to accept tighter margins. 

<p>ICRA notes that while the sector is expected to deliver 8-10% YoY growth in operating income (OI) for FY2026, profitability remains constrained. Road projects awarded by MoRTH/NHAI have seen particularly sharp margin compression, with most contracts being finalized at substantial discounts to base prices. Similar competitive pressures are evident in metro, railways, and water infrastructure segments as new entrants vie for market share. The Model Code of Conduct (MCC) in Q1 FY2025, coupled with an extended monsoon and the transition to milestone-based billing in Q2 FY2025, significantly hampered construction activities, particularly in road projects. Following a modest 1.5% YoY growth in H1 FY2025, execution accelerated in Q3 FY2025 and maintained momentum in Q4 FY2025. Despite this recovery, the overall OI growth for ICRA’s sample set in FY2025 is estimated at a subdued 1-3%, with fresh order inflows remaining modest during the first nine months due to the impact of the General Elections. 

Suprio Banerjee, Vice President and Co-Group Head, Corporate Ratings, ICRA, said, "The aggregate order book/OI for ICRA's sample set of entities is estimated at ~3.5 times as on March 31, 2025, reflecting healthy growth prospects and revenue visibility. Although the order inflows in FY2025 are likely to trail those seen in FY2024, the pick-up in order awarding activity from Q3 FY2025 onwards is expected to result in a satisfactory order book position. The contractors, focused largely on the road segment, are likely to under-perform compared to broader trends owing to slowdown in order-awarding activity from the MoRTH/NHAI. Several mid-sized road construction entities have order book/revenue of less than 2.0 times, indicating imminent stress on their revenue prospects in FY2026. Diversified players, especially those focusing on urban infrastructure, renewable and water-related projects are anticipated to perform relatively better in the current fiscal." 

ICRA highlights that working capital pressures may partially offset margin stability. The expiration of Atmanirbhar Bharat relief measures has already extended the cash conversion cycle in FY2025, requiring higher debt levels to fund operations. 

"The cash conversion cycle is expected to sustain at the current levels, given that the expiry of the Atmanirbhar Bharat relief measures have already elongated the working capital cycle for players in FY2025. While debt levels are likely to increase to support the higher working capital requirements, the corresponding operational leverage benefits are projected to keep the interest cover adequate at 3.6-3.9 times in FY2026e. Given the moderate leverage and satisfactory debt coverage metrics, ICRA maintains a Stable outlook on the construction sector," Banerjee noted. 

The margin outlook remains bifurcated by segment, with road-focused contractors facing greater pressure compared to diversified players in urban infrastructure, renewables and water projects. ICRA's analysis of 19 leading companies (representing ~50% of listed sector revenue) suggests mid-sized road contractors with order book/revenue below 2x are particularly vulnerable to margin erosion in FY2026. 
                                                            

ICRA projects that the Construction industry's operating margins to remain range-bound at 10.5-11.0% in FY2025 and FY2026, supported by relatively stable input prices and benefits from operational leverage. However, this represents a moderation from the 13-14% levels seen in FY2021, as heightened competition across sub-sectors forces contractors to accept tighter margins. <p>ICRA notes that while the sector is expected to deliver 8-10% YoY growth in operating income (OI) for FY2026, profitability remains constrained. Road projects awarded by MoRTH/NHAI have seen particularly sharp margin compression, with most contracts being finalized at substantial discounts to base prices. Similar competitive pressures are evident in metro, railways, and water infrastructure segments as new entrants vie for market share. The Model Code of Conduct (MCC) in Q1 FY2025, coupled with an extended monsoon and the transition to milestone-based billing in Q2 FY2025, significantly hampered construction activities, particularly in road projects. Following a modest 1.5% YoY growth in H1 FY2025, execution accelerated in Q3 FY2025 and maintained momentum in Q4 FY2025. Despite this recovery, the overall OI growth for ICRA’s sample set in FY2025 is estimated at a subdued 1-3%, with fresh order inflows remaining modest during the first nine months due to the impact of the General Elections. Suprio Banerjee, Vice President and Co-Group Head, Corporate Ratings, ICRA, said, The aggregate order book/OI for ICRA's sample set of entities is estimated at ~3.5 times as on March 31, 2025, reflecting healthy growth prospects and revenue visibility. Although the order inflows in FY2025 are likely to trail those seen in FY2024, the pick-up in order awarding activity from Q3 FY2025 onwards is expected to result in a satisfactory order book position. The contractors, focused largely on the road segment, are likely to under-perform compared to broader trends owing to slowdown in order-awarding activity from the MoRTH/NHAI. Several mid-sized road construction entities have order book/revenue of less than 2.0 times, indicating imminent stress on their revenue prospects in FY2026. Diversified players, especially those focusing on urban infrastructure, renewable and water-related projects are anticipated to perform relatively better in the current fiscal. ICRA highlights that working capital pressures may partially offset margin stability. The expiration of Atmanirbhar Bharat relief measures has already extended the cash conversion cycle in FY2025, requiring higher debt levels to fund operations. The cash conversion cycle is expected to sustain at the current levels, given that the expiry of the Atmanirbhar Bharat relief measures have already elongated the working capital cycle for players in FY2025. While debt levels are likely to increase to support the higher working capital requirements, the corresponding operational leverage benefits are projected to keep the interest cover adequate at 3.6-3.9 times in FY2026e. Given the moderate leverage and satisfactory debt coverage metrics, ICRA maintains a Stable outlook on the construction sector, Banerjee noted. The margin outlook remains bifurcated by segment, with road-focused contractors facing greater pressure compared to diversified players in urban infrastructure, renewables and water projects. ICRA's analysis of 19 leading companies (representing ~50% of listed sector revenue) suggests mid-sized road contractors with order book/revenue below 2x are particularly vulnerable to margin erosion in FY2026.                                                             

Related Stories

Gold Stories
Next Story
Real Estate

Peninsula Land launches 19 luxury villas in Pune

Pune’s residential landscape is witnessing a shift as premium homebuyers increasingly seek larger spaces, privacy and independent living options beyond high-rise apartments. Addressing this demand, Peninsula Land Limited, part of the Ashok Piramal Group, has launched AshokVillas, an exclusive collection of 19 premium furnished villas in Gahunje, Pune.The development combines the independence of a standalone home with the convenience and security of a managed residential community. Designed around low-density horizontal living, AshokVillas offers residents private spaces while providing acces..
Next Story
Infrastructure Urban

MyBranch Expands South India Network with 16 Workspace Centres

MyBranch has expanded its South India presence with a 50,000 sq ft flexible workspace network comprising 16 centres across 14 cities in Andhra Pradesh, Karnataka, Tamil Nadu and Telangana.The expansion reflects growing demand for flexible office infrastructure as businesses establish regional teams, satellite offices and operations beyond traditional metropolitan markets. MyBranch’s network spans Bengaluru, Coimbatore, Guntur, Hanamkonda, Hubballi, Hyderabad, Madurai, Mangaluru, Rajahmundry, Salem, Tirupati, Vellore, Vijayawada and Visakhapatnam, with a large office space in Chennai also und..
Next Story
Building Material

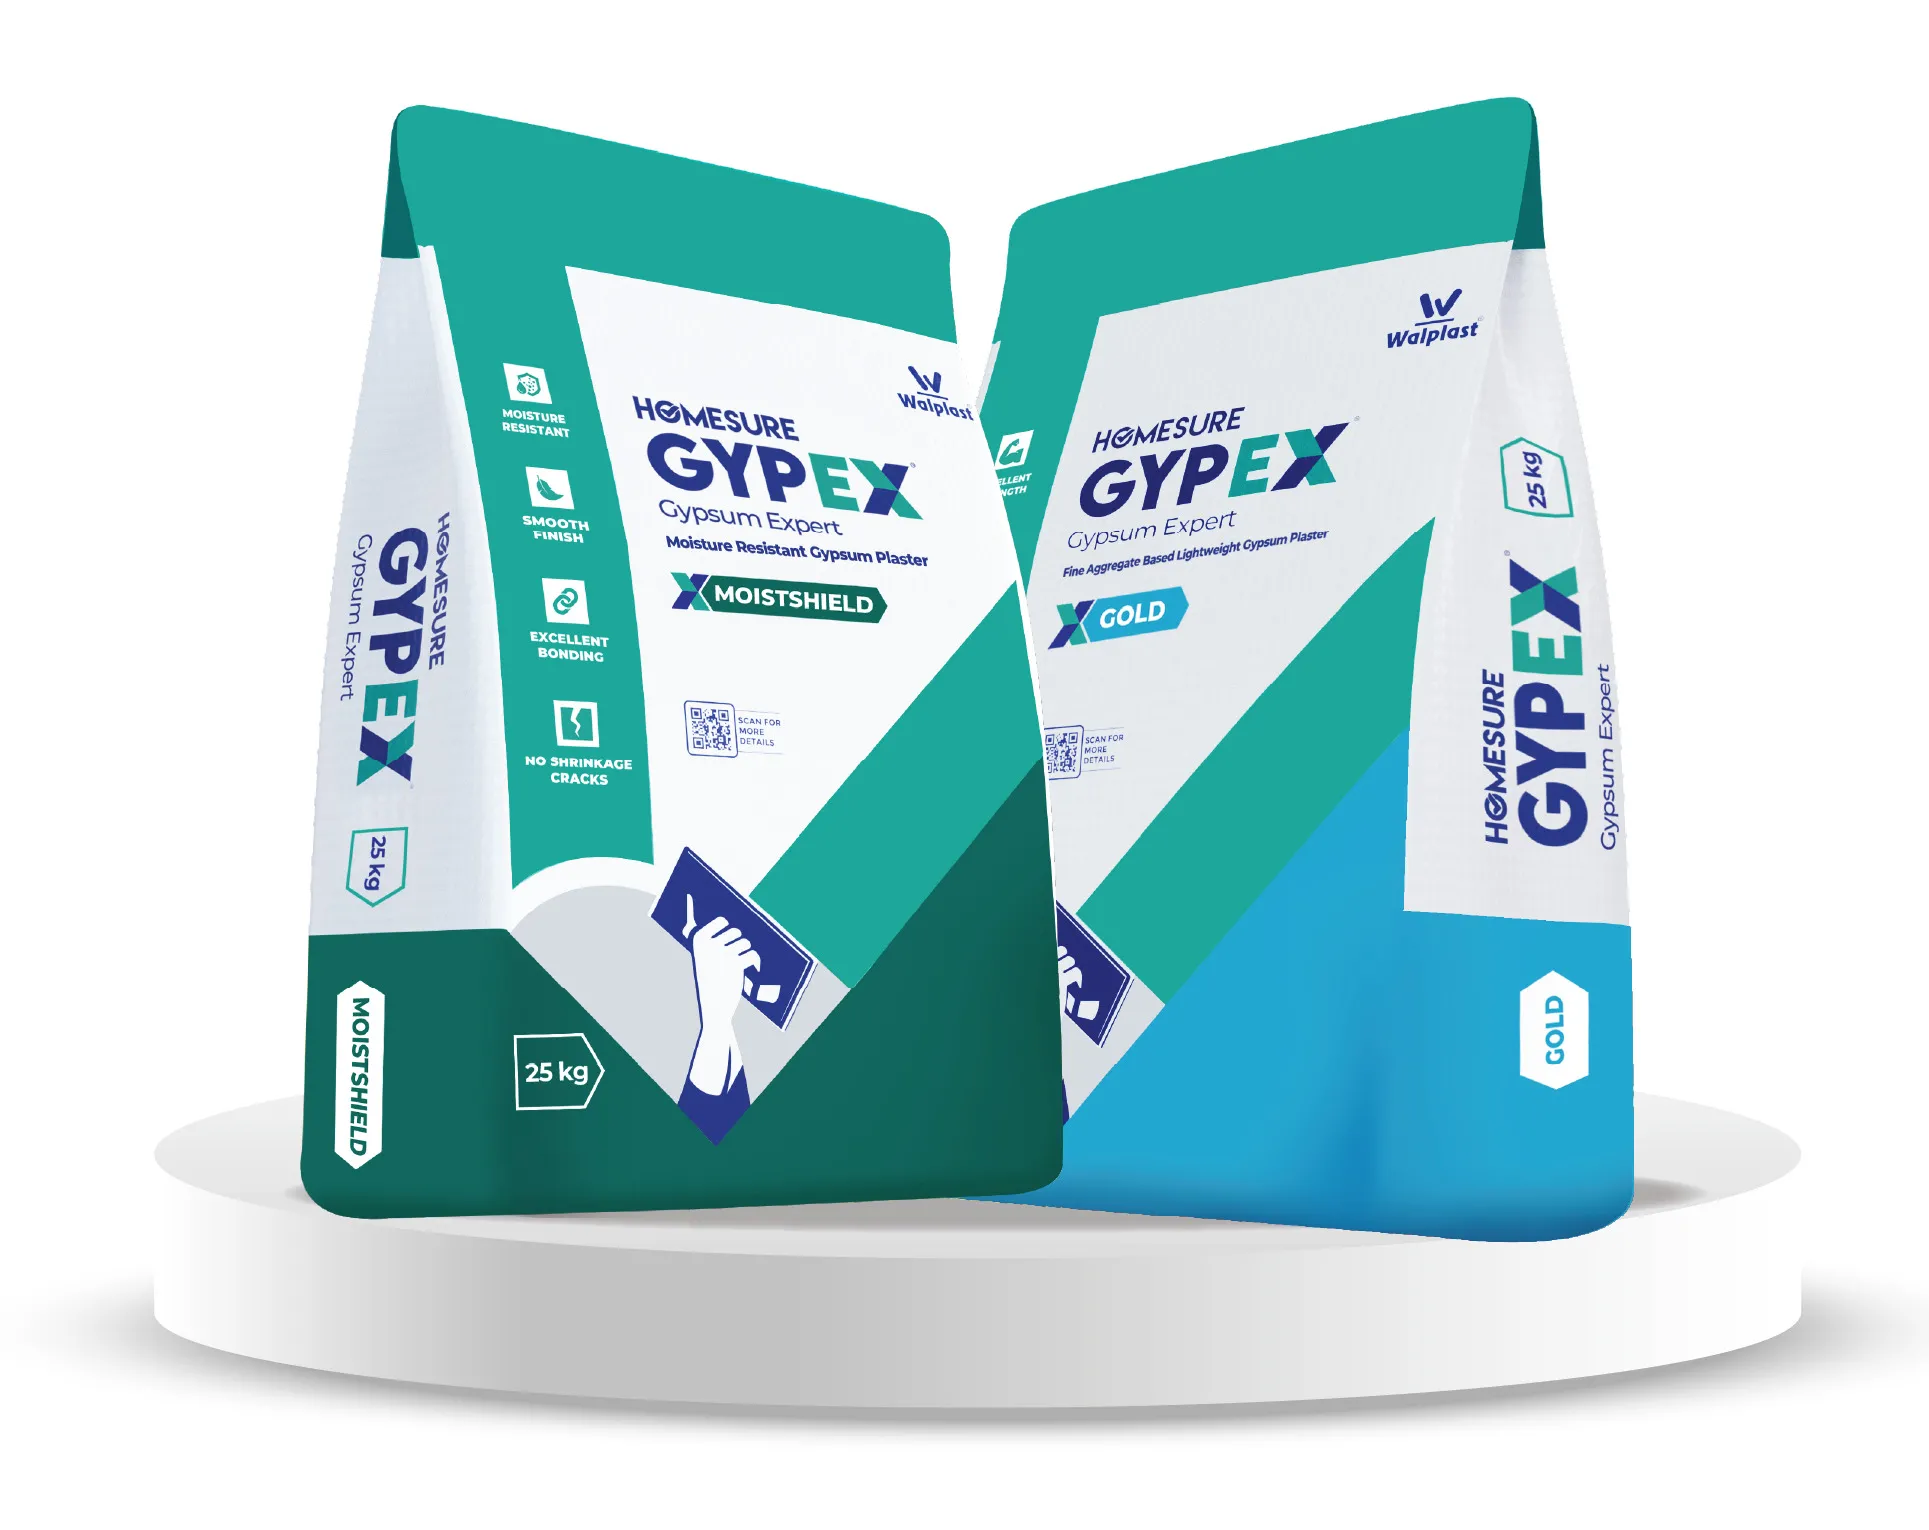
Walplast Launches Moisture-Resistant Gypsum Plaster Solutions

Walplast Products Pvt. Ltd. has expanded its HomeSure GypEx portfolio with the launch of GypEx MoistShield and GypEx Gold, two gypsum plaster solutions designed to address moisture-prone applications and improve plastering efficiency.The new products have been developed in response to the growing demand for faster construction processes, improved material performance and consistent surface quality. The solutions aim to simplify interior plastering while addressing specific application requirements across construction environments.“Through HomeSure GypEx MoistShield and GypEx Gold, we are exp..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code