- Home
- Infrastructure Urban
- ECONOMY & POLICY
- Forecasted GDP rate for FY22 drops to 9.2%: Care Ratings
Forecasted GDP rate for FY22 drops to 9.2%: Care Ratings
The spread of infection has also affected workers in various businesses in this round, which is directly affecting companies. Supply chains are being affected this time due to workers getting infected unlike the first wave in 2020 when there were restrictions on the movement of goods. Therefore, there is a double whammy due to the second wave of a lockdown as well as personal health of workers.
According to the recent Care Ratings report, it is assumed that the loss in June and part of July will be comparable to the previous months due to the spread of the virus in the interiors. Also based on the progress of the vaccination programme, it does appear that there will be significant delays in meeting targets and the nation will still be in the first gear mode in June with movement to the second starting earliest in July. Hence Q1 of this year will be stressed out to a large extent with July showing mixed signs, states the Care Ratings report.
There are 3.7 million active cases which can be affecting broadly over 10 million families. There have been cumulative discharges of around 19 million people which will affect at least 60-70 million families. This can potentially also affect the purchasing power of families and hence unlike last year when the pent-up demand theory worked to a certain extent, this time it will be dormant. These people would have spent considerable amounts of money on medical treatment and unless in the top echelons of income would not be in a position to spend more this time after the infection incidence abates. The sheer numbers this time will delay the demand revival process this year.
Under these assumptions, GDP growth for FY22 will be 9.2% with a downward bias as against 10.2% projected in April.
Movement in our forecasts for GDP growth (%)
Date of forecast | GDP growth |
2020-21 (Actual) | -8.0 |
2021-22: 24 March'21 | 11-11.2 |
2021-22: 5 April'21 | 10.7 |
2021-22: 21 April'21 | 10.2 |
2021-22: 12 May’ 21 | 9.2 |
Source: CARE Ratings
GDP in FY21 was Rs 134.08 lakh crore that was to increase to Rs 148.83-Rs 149.10 lakh crore as per the March forecast. The GDP level in real terms will be Rs 146.42 lakh crore based on 9.2% growth. The lower growth in GDP compared to the initial estimate of 11.2% would mean a loss of Rs 2.68 lakh crore in real terms or Rs 3.89 lakh crore in nominal terms. In real terms the growth would be:
Agriculture 3.3-3.5%,
Industry 9.5-10% and
Services 9-9.5%.
This in turn will also have fiscal implications.
The Budget had targeted a nominal GDP of Rs 222.87 lakh crore. The fiscal deficit was estimated at Rs 15.07 lakh crore accordingly. With real GDP growth falling by Rs 2.68 lakh crore, nominal GDP would now be reduced to Rs 218.98 lakh crore with a loss of nearly Rs 3.9 lakh crore of income.
Further, with GDP growth slowing down by 2% points, the overall tax revenue to the centre will come down from Rs 15.45 lakh crore to Rs 15.11 lakh crore, which is a shortfall of Rs 34,000 crore. Last month, the government has already announced an outlay of Rs 25,000 crore on account of the free food programme for 800 million people (which would be at Rs.5 kg/month). This additional cost combined with the potential decline in tax revenue will mean an increase in deficit by Rs 59,000 crore. The revised fiscal deficit under ceteris paribus conditions would be Rs 15.66 lakh crore or 7.15% of GDP. This is assuming that the government spends the additional Rs 25,000 cr outside the budget and does not channel the same from an existing allocation.
It should also be pointed out that any adverse effect on agriculture due to the spread of infection would also necessitate higher MNREGA spending and every additional Rs 10,000 crore spent on this programme can push the GDP up by 0.04%.
Care Ratings’ report on April 21 projects India’s GDP growth to be 10.2% for FY22 on the assumption that the lockdowns would be rolled back in June. This was premised on the daily infection caseload declining in the month of May. However, while there have been some swings in the last few days, the daily cases have not gone below the 350,000 mark. The seven- days moving average is still at around 390,000 as of May 10. The concern now is that the infections are spreading to the interiors too in most states which also means that agriculture, which was isolated from the first wave, can be affected this time though there is not a perceptible impact presently. The spread of infection has also affected workers in various businesses in this round, which is directly affecting companies. Supply chains are being affected this time due to workers getting infected unlike the first wave in 2020 when there were restrictions on the movement of goods. Therefore, there is a double whammy due to the second wave of a lockdown as well as personal health of workers. According to the recent Care Ratings report, it is assumed that the loss in June and part of July will be comparable to the previous months due to the spread of the virus in the interiors. Also based on the progress of the vaccination programme, it does appear that there will be significant delays in meeting targets and the nation will still be in the first gear mode in June with movement to the second starting earliest in July. Hence Q1 of this year will be stressed out to a large extent with July showing mixed signs, states the Care Ratings report. There are 3.7 million active cases which can be affecting broadly over 10 million families. There have been cumulative discharges of around 19 million people which will affect at least 60-70 million families. This can potentially also affect the purchasing power of families and hence unlike last year when the pent-up demand theory worked to a certain extent, this time it will be dormant. These people would have spent considerable amounts of money on medical treatment and unless in the top echelons of income would not be in a position to spend more this time after the infection incidence abates. The sheer numbers this time will delay the demand revival process this year. Under these assumptions, GDP growth for FY22 will be 9.2% with a downward bias as against 10.2% projected in April. Movement in our forecasts for GDP growth (%) Date of forecast GDP growth 2020-21 (Actual) -8.02021-22: 24 March'21 11-11.22021-22: 5 April'21 10.72021-22: 21 April'21 10.22021-22: 12 May’ 21 9.2 Source: CARE Ratings GDP in FY21 was Rs 134.08 lakh crore that was to increase to Rs 148.83-Rs 149.10 lakh crore as per the March forecast. The GDP level in real terms will be Rs 146.42 lakh crore based on 9.2% growth. The lower growth in GDP compared to the initial estimate of 11.2% would mean a loss of Rs 2.68 lakh crore in real terms or Rs 3.89 lakh crore in nominal terms. In real terms the growth would be: Agriculture 3.3-3.5%, Industry 9.5-10% and Services 9-9.5%. This in turn will also have fiscal implications. The Budget had targeted a nominal GDP of Rs 222.87 lakh crore. The fiscal deficit was estimated at Rs 15.07 lakh crore accordingly. With real GDP growth falling by Rs 2.68 lakh crore, nominal GDP would now be reduced to Rs 218.98 lakh crore with a loss of nearly Rs 3.9 lakh crore of income. Further, with GDP growth slowing down by 2% points, the overall tax revenue to the centre will come down from Rs 15.45 lakh crore to Rs 15.11 lakh crore, which is a shortfall of Rs 34,000 crore. Last month, the government has already announced an outlay of Rs 25,000 crore on account of the free food programme for 800 million people (which would be at Rs.5 kg/month). This additional cost combined with the potential decline in tax revenue will mean an increase in deficit by Rs 59,000 crore. The revised fiscal deficit under ceteris paribus conditions would be Rs 15.66 lakh crore or 7.15% of GDP. This is assuming that the government spends the additional Rs 25,000 cr outside the budget and does not channel the same from an existing allocation. It should also be pointed out that any adverse effect on agriculture due to the spread of infection would also necessitate higher MNREGA spending and every additional Rs 10,000 crore spent on this programme can push the GDP up by 0.04%. Image Source
Related Stories
Gold Stories
Perkins Begins Production of 5016 Power Generation Engine
Perkins has commenced production of its new 5016 full-authority electronic engine, completing its 5000 Series range of 6-, 8-, 12- and 16-cylinder engines. Manufactured in Stafford, UK, and Aurangabad, India, the range delivers up to 2,500 kVA of standby power and 2,250 kVA of prime power.The 61-litre V16 engine delivers 1,400–2,500 kVA at 50 Hz for base load, prime and standby applications. Designed for power generation, it supports critical infrastructure, including data centres, hospitals, airports and remote worksites.Engineered to meet ISO G3 and NFPA110 standards, the 5016 incorporates..
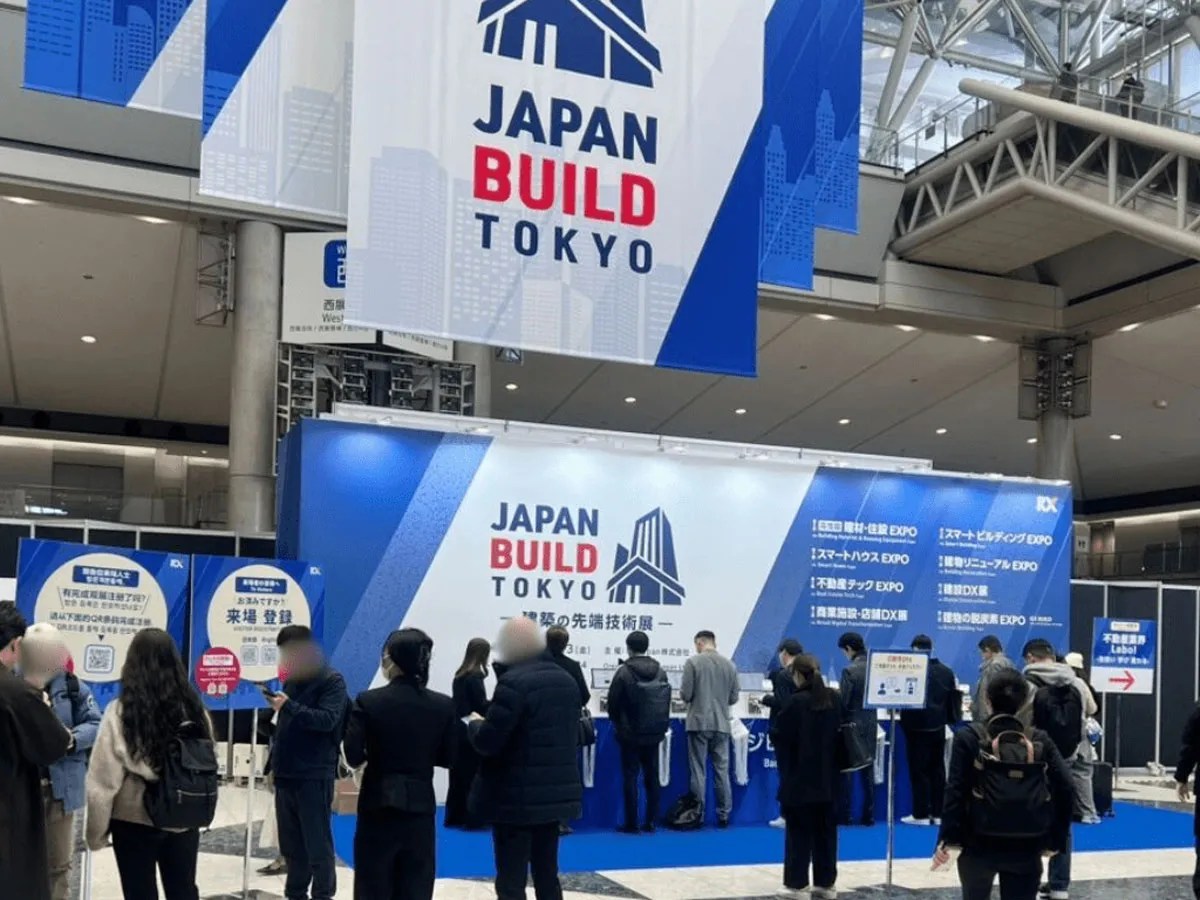
JAPAN BUILD Tokyo 2026 Expects 35,000 Visitors
RX Japan GK will organise the 11th edition of JAPAN BUILD Tokyo at Tokyo Big Sight from 2–4 December 2026, with approximately 35,000 visitors expected from the building, construction and real estate sectors.The exhibition will bring together manufacturers, developers, contractors, architects, distributors and property owners. According to the organiser, 51.2 per cent of visitors hold managerial positions or above, providing exhibitors with opportunities to engage with procurement decision-makers. The previous edition attracted 33,618 visitors and 548 exhibitors.JAPAN BUILD Tokyo will feature..
Magma Signs LOIs Worth Over Rs 8 Bn Across Industrial Businesses
Magma has signed Letters of Intent (LOIs) worth more than Rs 8 bn across its advanced materials, waste management, precision engineering and digital industrial solutions businesses.The company expects to execute around 70 per cent of the current LOI pipeline during FY27, providing visibility for the remainder of the financial year. The pipeline reflects rising demand from enterprise manufacturers and deeper engagement across Magma’s customer relationships.India’s industrial B2B trade is estimated at around USD 2 trillion. In precision engineering, imports account for 60-65 per cent of high..
Related Articles
Latest Updates
Recommended for you
Advertisement
Subscribe to Our Newsletter
Get daily newsletters around different themes from Construction world.
subscribe to the newsletter
Don't miss out on valuable insights and opportunities
to connect with like minded professionals