Red Sea Crisis: RBI and IRDAI Urged to Mitigate Export Impact
ECONOMY & POLICY

Red Sea Crisis: RBI and IRDAI Urged to Mitigate Export Impact

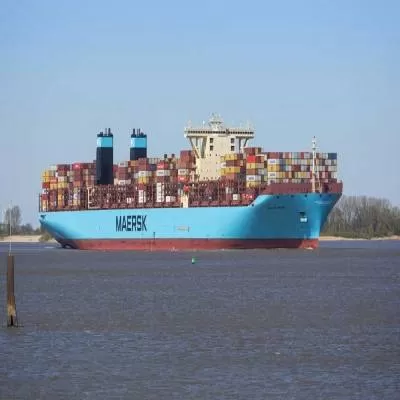
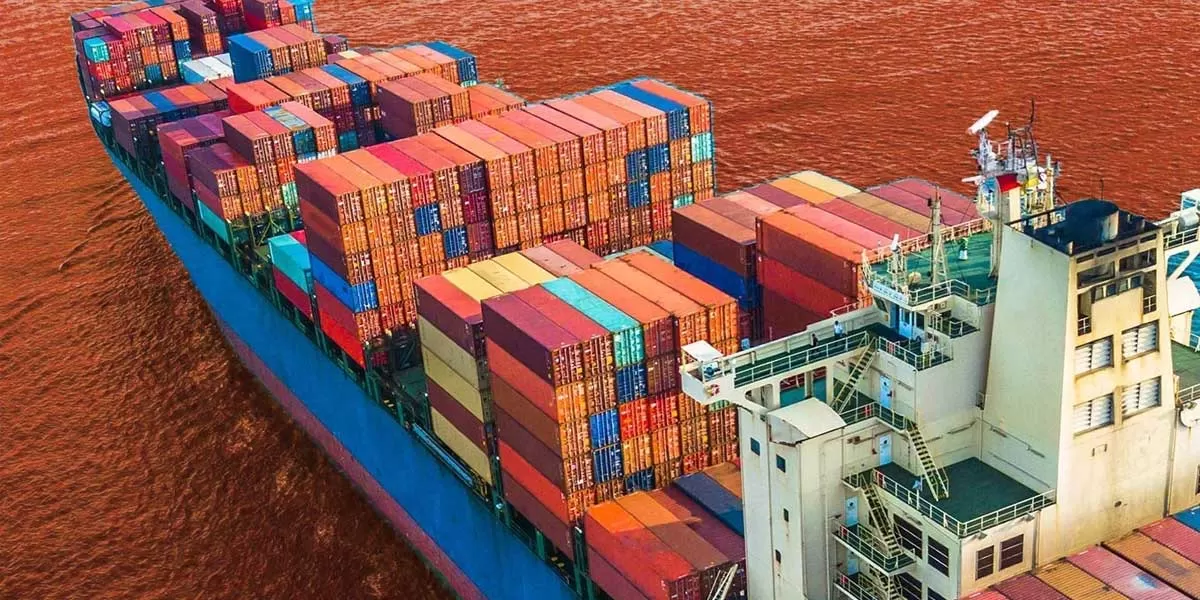
Amidst escalating tensions in the Red Sea region, concerns are mounting over the potential impact on India's oil and gas exports. The recent request made to the Reserve Bank of India (RBI) and the Insurance Regulatory and Development Authority of India (IRDAI) underscores the gravity of the situation. With key trade routes threatened and geopolitical tensions rising, stakeholders are seeking proactive measures to safeguard India's export interests.

The Red Sea crisis, sparked by escalating conflict and maritime security threats, has raised alarm bells across global markets. India, as a major exporter of oil and gas products, finds itself particularly vulnerable to disruptions in this vital trade corridor. The strategic significance of the Red Sea cannot be overstated, with a significant portion of global trade passing through its waters. Any disruption in this region has the potential to reverberate throughout the global economy.

In response to these challenges, the RBI and IRDAI have been called upon to play a crucial role in limiting the impact on India's exports. The RBI, with its authority over monetary policy and financial stability, is well-positioned to implement measures to mitigate the economic fallout. Similarly, the IRDAI, as the regulatory authority for the insurance sector, can explore options to provide coverage and risk management solutions for exporters operating in the region.

Efforts to address the Red Sea crisis extend beyond economic considerations alone. Geopolitical tensions in the region have escalated in recent months, with implications for regional stability and security. India, as a responsible global actor, has a vested interest in promoting peace and stability in the Red Sea region. Diplomatic efforts, in conjunction with economic measures, may prove instrumental in defusing tensions and safeguarding the interests of all stakeholders.

As the situation continues to evolve, collaboration between government agencies, industry stakeholders, and international partners will be crucial. By taking proactive steps to address the challenges posed by the Red Sea crisis, India can navigate these turbulent waters and emerge stronger on the global stage.

Amidst escalating tensions in the Red Sea region, concerns are mounting over the potential impact on India's oil and gas exports. The recent request made to the Reserve Bank of India (RBI) and the Insurance Regulatory and Development Authority of India (IRDAI) underscores the gravity of the situation. With key trade routes threatened and geopolitical tensions rising, stakeholders are seeking proactive measures to safeguard India's export interests. The Red Sea crisis, sparked by escalating conflict and maritime security threats, has raised alarm bells across global markets. India, as a major exporter of oil and gas products, finds itself particularly vulnerable to disruptions in this vital trade corridor. The strategic significance of the Red Sea cannot be overstated, with a significant portion of global trade passing through its waters. Any disruption in this region has the potential to reverberate throughout the global economy. In response to these challenges, the RBI and IRDAI have been called upon to play a crucial role in limiting the impact on India's exports. The RBI, with its authority over monetary policy and financial stability, is well-positioned to implement measures to mitigate the economic fallout. Similarly, the IRDAI, as the regulatory authority for the insurance sector, can explore options to provide coverage and risk management solutions for exporters operating in the region. Efforts to address the Red Sea crisis extend beyond economic considerations alone. Geopolitical tensions in the region have escalated in recent months, with implications for regional stability and security. India, as a responsible global actor, has a vested interest in promoting peace and stability in the Red Sea region. Diplomatic efforts, in conjunction with economic measures, may prove instrumental in defusing tensions and safeguarding the interests of all stakeholders. As the situation continues to evolve, collaboration between government agencies, industry stakeholders, and international partners will be crucial. By taking proactive steps to address the challenges posed by the Red Sea crisis, India can navigate these turbulent waters and emerge stronger on the global stage.

Related Stories

Gold Stories

Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code