+
Reliance's refining margins recover but retail remains uncertain
ECONOMY & POLICY

Reliance's refining margins recover but retail remains uncertain

Brokerage JP Morgan reported that one of the factors behind Reliance Industries Ltd's recent underperformance—weak refining margins—has shown improvement, while the other, sluggish retail top-line growth, remains unpredictable. The company’s stock has fallen by 22% from its peak on 8 July (compared to a 3.3% decline in NIFTY), reversing its earlier strong performance this year. Despite this, in a market where many stocks trade well above historical valuations, Reliance's fair relative valuations are considered an appealing aspect.

Led by billionaire Mukesh Ambani, Reliance Industries operates across three core business segments: the oil-to-chemical (O2C) unit for oil refining and petrochemicals, telecom services under Jio, and the retail division. The conglomerate also has a media unit and a new energy business. Reliance Retail and Jio Telecom collectively account for about 50% of the total consolidated EBITDA for FY24. According to JP Morgan, these segments are projected to contribute nearly all of the company's net EBITDA growth over the next three years. With an annual EBITDA run rate of USD 20 billion, the company is expected to maintain positive free cash flow for the next three years, despite significant capital expenditure plans for new energy projects, retail expansion, and petrochemical capacity increases.

JP Morgan highlighted two key challenges: "1) Refining margins, which dropped sharply beginning in June, and 2) continued disappointment in revenue and EBITDA growth at Reliance Retail." The brokerage observed that refining margins have rebounded recently, improving performance in the third quarter, and suggested that the reduction in Chinese export tax rebates could further support refining margins, or "cracks," which represent the difference between crude oil costs and finished product prices.

As for retail, JP Morgan questioned whether growth was bottoming out but noted that near-term predictions remain challenging. It attributed the struggles to a broader slowdown in retail and internal restructuring within the company. The report also flagged investor concerns about the impact of Quick Commerce on Reliance Retail’s performance.

Brokerage JP Morgan reported that one of the factors behind Reliance Industries Ltd's recent underperformance—weak refining margins—has shown improvement, while the other, sluggish retail top-line growth, remains unpredictable. The company’s stock has fallen by 22% from its peak on 8 July (compared to a 3.3% decline in NIFTY), reversing its earlier strong performance this year. Despite this, in a market where many stocks trade well above historical valuations, Reliance's fair relative valuations are considered an appealing aspect. Led by billionaire Mukesh Ambani, Reliance Industries operates across three core business segments: the oil-to-chemical (O2C) unit for oil refining and petrochemicals, telecom services under Jio, and the retail division. The conglomerate also has a media unit and a new energy business. Reliance Retail and Jio Telecom collectively account for about 50% of the total consolidated EBITDA for FY24. According to JP Morgan, these segments are projected to contribute nearly all of the company's net EBITDA growth over the next three years. With an annual EBITDA run rate of USD 20 billion, the company is expected to maintain positive free cash flow for the next three years, despite significant capital expenditure plans for new energy projects, retail expansion, and petrochemical capacity increases. JP Morgan highlighted two key challenges: 1) Refining margins, which dropped sharply beginning in June, and 2) continued disappointment in revenue and EBITDA growth at Reliance Retail. The brokerage observed that refining margins have rebounded recently, improving performance in the third quarter, and suggested that the reduction in Chinese export tax rebates could further support refining margins, or cracks, which represent the difference between crude oil costs and finished product prices. As for retail, JP Morgan questioned whether growth was bottoming out but noted that near-term predictions remain challenging. It attributed the struggles to a broader slowdown in retail and internal restructuring within the company. The report also flagged investor concerns about the impact of Quick Commerce on Reliance Retail’s performance.

Related Stories

Gold Stories

Next Story
Infrastructure Urban

KONE Opens India's First Digital Experience Centre in Pune

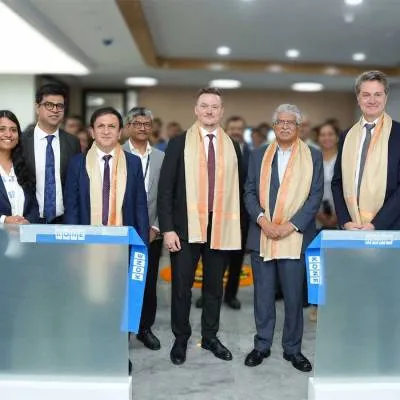
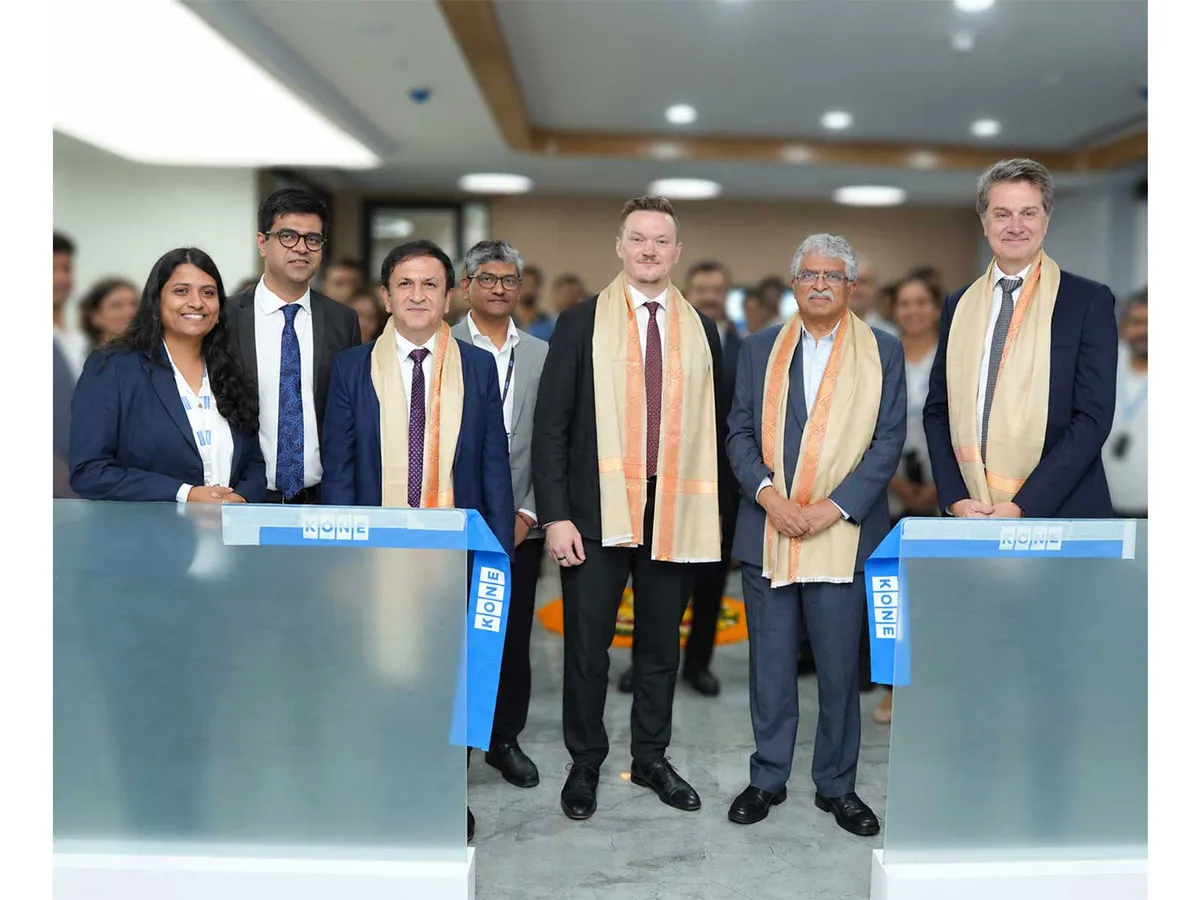
KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

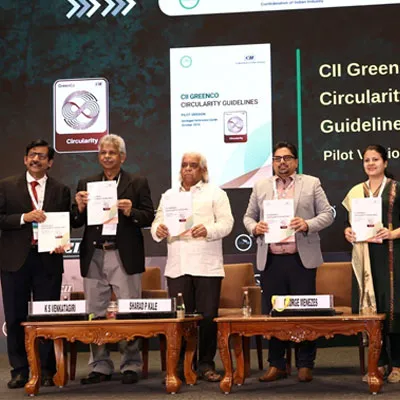
CII GreenCo Launches Circularity Guidelines for Indian Industry

The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

Global Electronics Association Launches IPC-1783-CO2E Standard

The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code