S&P Lifts Vedanta Outlook On Earnings, Cost Gains
ECONOMY & POLICY

S&P Lifts Vedanta Outlook On Earnings, Cost Gains

S&P Global has revised its outlook on Vedanta Resources to positive from stable while reaffirming its B+ rating, citing stronger earnings visibility, continued cost reductions and supportive metal prices. Together, these factors are expected to bolster the company’s cash flows.

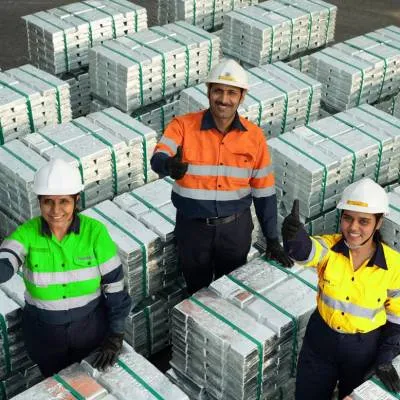
Vedanta has tightened its cost structure, particularly in aluminium. The commissioning of a 1.5-million-tonne-per-annum alumina refinery at Lanjigarh has raised total capacity to 5 mtpa. S&P expects the new capacity to scale up over the next six months, delivering cost savings of about US$ 50 per tonne of aluminium. The company is also enhancing bauxite integration, with a ramp-up in mining operations over the next 12–18 months projected to lower production costs further.

Vedanta is increasing the share of value-added products in aluminium and zinc, helping the company earn higher premiums over London Metal Exchange prices. S&P believes that lower costs and higher output will meaningfully lift earnings and strengthen credit metrics.

The agency forecasts a 10 per cent rise in EBITDA in both FY26 and FY27. This could push Vedanta’s funds-from-operations (FFO) to debt ratio slightly above the 30 per cent upgrade threshold, compared with an estimated 24 per cent in FY26. The positive outlook reflects this expectation.

While Vedanta’s credit profile has historically fluctuated with commodity cycles, S&P says deeper backward integration should soften volatility. However, delays in project ramp-up could strain the outlook given limited buffer in the FFO-to-debt ratio.

Vedanta’s holding company debt has also become more manageable, with repayments of US$ 500–600 million due annually over the next three fiscal years. S&P expects these obligations to be met through brand fees of US$ 350 million and dividends of US$ 600–700 million from Vedanta Ltd — lower than the previously projected US$ 800 million dividend requirement for FY26. Recent refinancing and planned repayment of intercompany loans are expected to reduce borrowing costs further.

Average interest expenses are projected at about US$ 450 million over the next two years, largely covered by brand fees, leaving most dividends available for debt reduction. S&P anticipates holding company debt to fall by US$ 500 million annually in FY27 and FY28.

Although deleveraging has strengthened Vedanta’s capital structure, the agency warns that long-term financial health depends on reducing reliance on dividends and maintaining a self-sustaining funding model. Acquisition-led growth also presents risk, with Vedanta historically pursuing debt-funded expansion. The agency notes that while the company’s US$ 2 billion bid for Jaiprakash Associates fell through, future leveraged transactions cannot be ruled out.

A rating upgrade is possible if Vedanta continues to reduce holding company debt, maintains FFO-to-debt above 30 per cent, successfully executes integration projects and improves its maturity profile while reducing reliance on dividends. The outlook could revert to stable if integration delays arise or if aggressive debt-funded expansion coincides with weaker cash flow.

Shares of Vedanta Ltd closed 1.29 per cent higher at Rs 532.80 on Monday and have gained 20 per cent so far in 2025.

S&P Global has revised its outlook on Vedanta Resources to positive from stable while reaffirming its B+ rating, citing stronger earnings visibility, continued cost reductions and supportive metal prices. Together, these factors are expected to bolster the company’s cash flows. Vedanta has tightened its cost structure, particularly in aluminium. The commissioning of a 1.5-million-tonne-per-annum alumina refinery at Lanjigarh has raised total capacity to 5 mtpa. S&P expects the new capacity to scale up over the next six months, delivering cost savings of about US$ 50 per tonne of aluminium. The company is also enhancing bauxite integration, with a ramp-up in mining operations over the next 12–18 months projected to lower production costs further. Vedanta is increasing the share of value-added products in aluminium and zinc, helping the company earn higher premiums over London Metal Exchange prices. S&P believes that lower costs and higher output will meaningfully lift earnings and strengthen credit metrics. The agency forecasts a 10 per cent rise in EBITDA in both FY26 and FY27. This could push Vedanta’s funds-from-operations (FFO) to debt ratio slightly above the 30 per cent upgrade threshold, compared with an estimated 24 per cent in FY26. The positive outlook reflects this expectation. While Vedanta’s credit profile has historically fluctuated with commodity cycles, S&P says deeper backward integration should soften volatility. However, delays in project ramp-up could strain the outlook given limited buffer in the FFO-to-debt ratio. Vedanta’s holding company debt has also become more manageable, with repayments of US$ 500–600 million due annually over the next three fiscal years. S&P expects these obligations to be met through brand fees of US$ 350 million and dividends of US$ 600–700 million from Vedanta Ltd — lower than the previously projected US$ 800 million dividend requirement for FY26. Recent refinancing and planned repayment of intercompany loans are expected to reduce borrowing costs further. Average interest expenses are projected at about US$ 450 million over the next two years, largely covered by brand fees, leaving most dividends available for debt reduction. S&P anticipates holding company debt to fall by US$ 500 million annually in FY27 and FY28. Although deleveraging has strengthened Vedanta’s capital structure, the agency warns that long-term financial health depends on reducing reliance on dividends and maintaining a self-sustaining funding model. Acquisition-led growth also presents risk, with Vedanta historically pursuing debt-funded expansion. The agency notes that while the company’s US$ 2 billion bid for Jaiprakash Associates fell through, future leveraged transactions cannot be ruled out. A rating upgrade is possible if Vedanta continues to reduce holding company debt, maintains FFO-to-debt above 30 per cent, successfully executes integration projects and improves its maturity profile while reducing reliance on dividends. The outlook could revert to stable if integration delays arise or if aggressive debt-funded expansion coincides with weaker cash flow. Shares of Vedanta Ltd closed 1.29 per cent higher at Rs 532.80 on Monday and have gained 20 per cent so far in 2025.

Related Stories

Gold Stories
Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code