India adds 513 MW new open-access solar capacity in Q1 2022
POWER & RENEWABLE ENERGY

India adds 513 MW new open-access solar capacity in Q1 2022

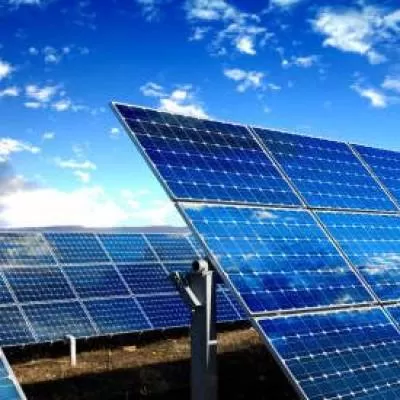
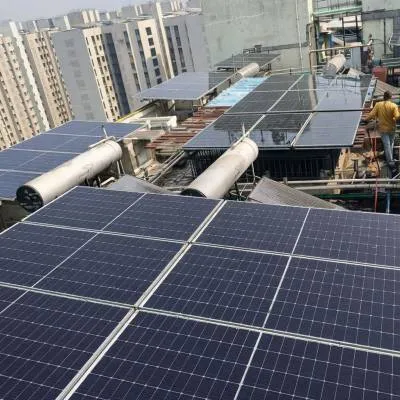
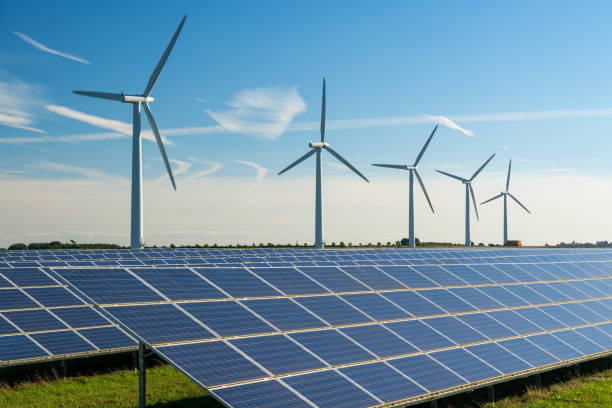
India added 513 MW of new open-access solar capacity in the first quarter (Q1) of 2022, recording an increase of 58% quarter-over-quarter (QoQ), compared to 324 MW established in Q4 2021. In Q1 2021, the year-over-year (YoY) installations grew by 22% compared to 422 MW.

The cumulative installed solar capacity in the open-access market stood at about 5.7 GW at the end of March 2022. The top five states in terms of open access installations accounted for 73% of the nation’s cumulative open access installations.

At the end of Q1 2022, the nation’s development pipeline of open access solar projects is 2 GW.

For the quarter, the top five states accounted for 86% of the total installations.

Karnataka was the largest market in Q1 2022, accounting for 30% of the total installations. The state accounted for 37% of the total open access installations.

In Q1 2022, Maharashtra was the second-largest market with a massive increase of 131% QoQ in solar open access installations against Q4 2021.

Gujarat is the third-largest market, accounting for 12.7% of the market.

In Karnataka, the success of open access may be attributed to the facilitating of open access regulations, timely distribution companies (DISCOM) clearances, early commissioning of projects, and the spurt in captive projects due to cost-saving advantages.

With the Approved List of Models and Manufacturers (ALMM) order extension for open access projects to October 1, 2022, and the Basic Customs Duty (BCD) effective from April 1, 2022, installers have been in a rush to start the projects to avoid procurement challenges.

The report analyses different short-term markets, such as the Day-Ahead Market (DAM), Term-Ahead Market, Green Term-Ahead Market, Green Day-Ahead Market (GDAM), and the Real-Time Market, which have been seeing a boost in the recent past.

The GTAM market had noticed a drop of about 49% in terms of volumes traded in Q4 2021. Green Energy in the Term-Ahead Market traded through the Indian Energy Exchange (IEX) recorded a drop of about 3% QoQ in costs.

Image Source

Also read: India witnesses 10 GW of solar installations in CY 2021

India added 513 MW of new open-access solar capacity in the first quarter (Q1) of 2022, recording an increase of 58% quarter-over-quarter (QoQ), compared to 324 MW established in Q4 2021. In Q1 2021, the year-over-year (YoY) installations grew by 22% compared to 422 MW. The cumulative installed solar capacity in the open-access market stood at about 5.7 GW at the end of March 2022. The top five states in terms of open access installations accounted for 73% of the nation’s cumulative open access installations. At the end of Q1 2022, the nation’s development pipeline of open access solar projects is 2 GW. For the quarter, the top five states accounted for 86% of the total installations. Karnataka was the largest market in Q1 2022, accounting for 30% of the total installations. The state accounted for 37% of the total open access installations. In Q1 2022, Maharashtra was the second-largest market with a massive increase of 131% QoQ in solar open access installations against Q4 2021. Gujarat is the third-largest market, accounting for 12.7% of the market. In Karnataka, the success of open access may be attributed to the facilitating of open access regulations, timely distribution companies (DISCOM) clearances, early commissioning of projects, and the spurt in captive projects due to cost-saving advantages. With the Approved List of Models and Manufacturers (ALMM) order extension for open access projects to October 1, 2022, and the Basic Customs Duty (BCD) effective from April 1, 2022, installers have been in a rush to start the projects to avoid procurement challenges. The report analyses different short-term markets, such as the Day-Ahead Market (DAM), Term-Ahead Market, Green Term-Ahead Market, Green Day-Ahead Market (GDAM), and the Real-Time Market, which have been seeing a boost in the recent past. The GTAM market had noticed a drop of about 49% in terms of volumes traded in Q4 2021. Green Energy in the Term-Ahead Market traded through the Indian Energy Exchange (IEX) recorded a drop of about 3% QoQ in costs. Image Source Also read: India witnesses 10 GW of solar installations in CY 2021

Related Stories

Gold Stories

Next Story
Infrastructure Urban

KONE Opens India's First Digital Experience Centre in Pune

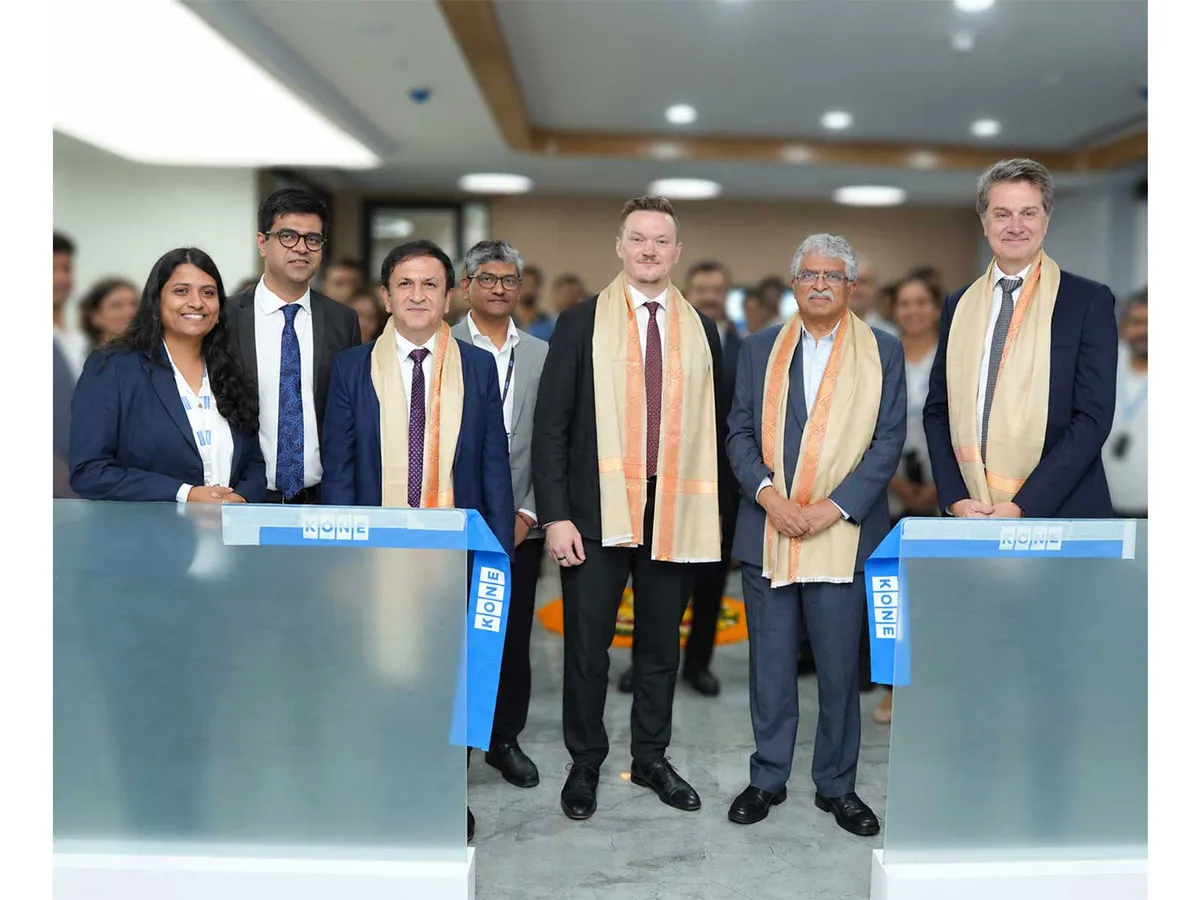
KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

CII GreenCo Launches Circularity Guidelines for Indian Industry

The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

Global Electronics Association Launches IPC-1783-CO2E Standard

The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code