Energy Storage Firm Stem’s Q3 Revenue Plunges
POWER & RENEWABLE ENERGY

Energy Storage Firm Stem’s Q3 Revenue Plunges

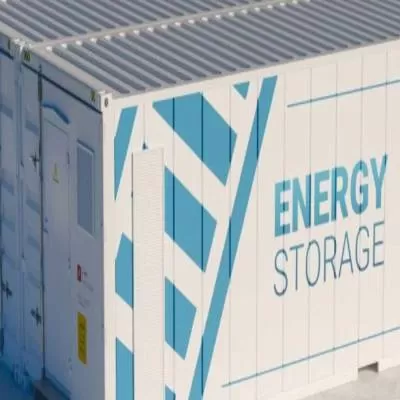
Smart energy storage company Stem‘s revenue in the third quarter (Q3) of 2024 dropped 78% to $29.3 from $133.7 million in Q3 2023 due to lower battery hardware sales. This decrease includes reductions of $5.6 million and $37.4 million, attributed to adjusted valuations of assets under specific hardware price guarantees established in 2022 and 2023.

Stem’s net loss rose 92.3% year-over-year (YoY) to $148.3 million from a $77.1 million net loss, primarily due to a $104.1 million bad debt expense related to impairments on accounts receivable for customer contracts with a parent company guarantee. The company’s earnings per share (EPS) of -$0.18 for Q3 exceeded analyst expectations by $0.021. The company concluded Q3 2024 with $75.4 million in cash and cash equivalents, compared to $89.6 million at the end of Q2 2024.

David Buzby, Stem’s Interim Chief Executive Officer, acknowledged the significant revenue drop due to lower hardware revenue during the quarter. The company recorded bookings of $29.1 million, a decline from $676.4 million in Q3 2023, mainly due to reduced bookings for battery hardware resales.

The contracted backlog stood at $1.5 billion, reflecting a 17% decrease from the end of Q3 2023 and a 2% decline from the end of Q2 2024. Contracted storage assets under management (AUM) totaled 6 GWh, up 20% YoY. Solar monitoring AUM reached 28.5 GW, up 8% from Q3 2023.

Stem stated that it is implementing cost-cutting measures to optimize business operations in accordance with a revised strategic approach. This shift was driven by ongoing uncertainty in project timelines for utility-scale storage hardware, which led to a strategic decision to reduce dependence on this revenue source. This unpredictability contributed to lower-than-expected bookings, revenue, and collections on accounts receivable.

The company reported a modest increase of approximately 200 MWh in storage assets and a growth of about 1.6 GW in solar during the quarter. However, the total contract value for bookings is expected to decline, primarily due to two factors: reduced battery storage hardware resales in new bookings and a move towards shorter software and service contracts in storage, now spanning 3 to 5 years instead of the previous 15 to 20 years.

Doran Hole, Chief Financial Officer and Executive Vice President announced that the company is revising its full-year 2024 guidance for several key metrics to reflect its most recent financial results, the ongoing implementation of its new strategy, and the anticipated project delays that continue to adversely affect revenue, bookings, and cash flow.

The energy storage system provider saw its revenue drop 63% YoY to $34 million in Q2 2024. Stem attributed the revenue dip and increased loss to reduced hardware demand and extended project timelines. During Q1, the company’s total revenue fell by 62% from $67.4 million in the prior quarter to $25.5 million.

Smart energy storage company Stem‘s revenue in the third quarter (Q3) of 2024 dropped 78% to $29.3 from $133.7 million in Q3 2023 due to lower battery hardware sales. This decrease includes reductions of $5.6 million and $37.4 million, attributed to adjusted valuations of assets under specific hardware price guarantees established in 2022 and 2023. Stem’s net loss rose 92.3% year-over-year (YoY) to $148.3 million from a $77.1 million net loss, primarily due to a $104.1 million bad debt expense related to impairments on accounts receivable for customer contracts with a parent company guarantee. The company’s earnings per share (EPS) of -$0.18 for Q3 exceeded analyst expectations by $0.021. The company concluded Q3 2024 with $75.4 million in cash and cash equivalents, compared to $89.6 million at the end of Q2 2024. David Buzby, Stem’s Interim Chief Executive Officer, acknowledged the significant revenue drop due to lower hardware revenue during the quarter. The company recorded bookings of $29.1 million, a decline from $676.4 million in Q3 2023, mainly due to reduced bookings for battery hardware resales. The contracted backlog stood at $1.5 billion, reflecting a 17% decrease from the end of Q3 2023 and a 2% decline from the end of Q2 2024. Contracted storage assets under management (AUM) totaled 6 GWh, up 20% YoY. Solar monitoring AUM reached 28.5 GW, up 8% from Q3 2023. Stem stated that it is implementing cost-cutting measures to optimize business operations in accordance with a revised strategic approach. This shift was driven by ongoing uncertainty in project timelines for utility-scale storage hardware, which led to a strategic decision to reduce dependence on this revenue source. This unpredictability contributed to lower-than-expected bookings, revenue, and collections on accounts receivable. The company reported a modest increase of approximately 200 MWh in storage assets and a growth of about 1.6 GW in solar during the quarter. However, the total contract value for bookings is expected to decline, primarily due to two factors: reduced battery storage hardware resales in new bookings and a move towards shorter software and service contracts in storage, now spanning 3 to 5 years instead of the previous 15 to 20 years. Doran Hole, Chief Financial Officer and Executive Vice President announced that the company is revising its full-year 2024 guidance for several key metrics to reflect its most recent financial results, the ongoing implementation of its new strategy, and the anticipated project delays that continue to adversely affect revenue, bookings, and cash flow. The energy storage system provider saw its revenue drop 63% YoY to $34 million in Q2 2024. Stem attributed the revenue dip and increased loss to reduced hardware demand and extended project timelines. During Q1, the company’s total revenue fell by 62% from $67.4 million in the prior quarter to $25.5 million.

Related Stories

Gold Stories

Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..

Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..

Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code