Mitsubishi Heavy Industries Reports Record FY24; Strong FY25 OutlooK
POWER & RENEWABLE ENERGY

Mitsubishi Heavy Industries Reports Record FY24; Strong FY25 OutlooK

Mitsubishi Heavy Industries (MHI) has reported its best-ever financial results for FY2024, achieving record highs in order intake, revenue, net income, and free cash flow. Order intake rose 5.8% year-on-year to ¥7,071.2 billion, while revenue climbed 7.9% to ¥5,027.1 billion. Business profit surged 35.6% to ¥383.1 billion with a 7.6% profit margin. Net income increased 10.6% year-on-year to ¥245.4 billion, and EBITDA rose 25.1% to ¥541.3 billion with a 10.8% margin.

Strong performance was led by the Energy Systems segment, particularly Gas Turbine Combined Cycle (GTCC) and Aero Engines, both of which saw substantial demand and improved margins. In the Plants & Infrastructure Systems segment, growth was driven by Metals Machinery and Machinery Systems. However, the Logistics, Thermal & Drive Systems segment recorded a decline in business profit due to lower unit sales and supply chain disruptions in Turbochargers.

The Aircraft, Defence & Space (ADS) segment posted strong growth, with revenue increasing by ¥239.0 billion, largely from the Defence & Space business. Increased revenue and higher margins resulted in a ¥27.2 billion year-on-year rise in segment business profit.
The company announced a full-year dividend of ¥23/share, up ¥3 from the previous year. For FY2025, MHI projects ¥5.4 trillion in revenue, ¥420 billion in business profit, and a dividend of ¥24/share, driven primarily by order execution in Defence & Space and continued demand in GTCC, Aero Engines, and HVAC.

“FY2024 was truly a remarkable year, with many of our businesses performing beyond expectations, which allowed us to report record figures in terms of order intake, revenue, net income, and free cash flow – this following what was by all accounts an extremely robust FY2023,” said Hisato Kozawa, Chief Financial Officer, MHI. “Regarding order intake, GTCC and Aero Engines in Energy, and Metals Machinery in P&I were star performers, and Defence & Space nearly matched the large order intake booked in FY2023. As a result, total orders in FY2024 exceeded the high bar set in the previous fiscal year. Revenue increased in Energy, P&I, and ADS, which were executing on substantial order backlogs. Increased revenue, improved margins, the positive impact from yen depreciation, as well as gains on fixed asset sales drove the large profit growth seen during this period."

"Today, we have also announced our earnings forecast for FY2025, which projects another record year for revenue and net income," Kozawa added. "Strong progress in project execution in GTCC and Defence, together with continued high demand in Aero Engines and HVAC, as well as a certain amount of recovery in Logistics Systems and Commercial Aviation will drive this revenue growth. Higher revenue combined with better margins will allow us to achieve ¥420 billion in business profit at a margin of 7.8%. In closing, please note that our earnings forecast does not reflect potential impact from the recent increase in global economic uncertainty, including that associated with tariffs. That said, we will aim to minimise any negative impact with a variety of countermeasures, such as negotiating cost passthroughs with our customers."

(JCN Newswire) 

Mitsubishi Heavy Industries (MHI) has reported its best-ever financial results for FY2024, achieving record highs in order intake, revenue, net income, and free cash flow. Order intake rose 5.8% year-on-year to ¥7,071.2 billion, while revenue climbed 7.9% to ¥5,027.1 billion. Business profit surged 35.6% to ¥383.1 billion with a 7.6% profit margin. Net income increased 10.6% year-on-year to ¥245.4 billion, and EBITDA rose 25.1% to ¥541.3 billion with a 10.8% margin.Strong performance was led by the Energy Systems segment, particularly Gas Turbine Combined Cycle (GTCC) and Aero Engines, both of which saw substantial demand and improved margins. In the Plants & Infrastructure Systems segment, growth was driven by Metals Machinery and Machinery Systems. However, the Logistics, Thermal & Drive Systems segment recorded a decline in business profit due to lower unit sales and supply chain disruptions in Turbochargers.The Aircraft, Defence & Space (ADS) segment posted strong growth, with revenue increasing by ¥239.0 billion, largely from the Defence & Space business. Increased revenue and higher margins resulted in a ¥27.2 billion year-on-year rise in segment business profit.The company announced a full-year dividend of ¥23/share, up ¥3 from the previous year. For FY2025, MHI projects ¥5.4 trillion in revenue, ¥420 billion in business profit, and a dividend of ¥24/share, driven primarily by order execution in Defence & Space and continued demand in GTCC, Aero Engines, and HVAC.“FY2024 was truly a remarkable year, with many of our businesses performing beyond expectations, which allowed us to report record figures in terms of order intake, revenue, net income, and free cash flow – this following what was by all accounts an extremely robust FY2023,” said Hisato Kozawa, Chief Financial Officer, MHI. “Regarding order intake, GTCC and Aero Engines in Energy, and Metals Machinery in P&I were star performers, and Defence & Space nearly matched the large order intake booked in FY2023. As a result, total orders in FY2024 exceeded the high bar set in the previous fiscal year. Revenue increased in Energy, P&I, and ADS, which were executing on substantial order backlogs. Increased revenue, improved margins, the positive impact from yen depreciation, as well as gains on fixed asset sales drove the large profit growth seen during this period.Today, we have also announced our earnings forecast for FY2025, which projects another record year for revenue and net income, Kozawa added. Strong progress in project execution in GTCC and Defence, together with continued high demand in Aero Engines and HVAC, as well as a certain amount of recovery in Logistics Systems and Commercial Aviation will drive this revenue growth. Higher revenue combined with better margins will allow us to achieve ¥420 billion in business profit at a margin of 7.8%. In closing, please note that our earnings forecast does not reflect potential impact from the recent increase in global economic uncertainty, including that associated with tariffs. That said, we will aim to minimise any negative impact with a variety of countermeasures, such as negotiating cost passthroughs with our customers.(JCN Newswire) 

Related Stories

Gold Stories

Next Story
Infrastructure Urban

KONE Opens India's First Digital Experience Centre in Pune

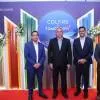
KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

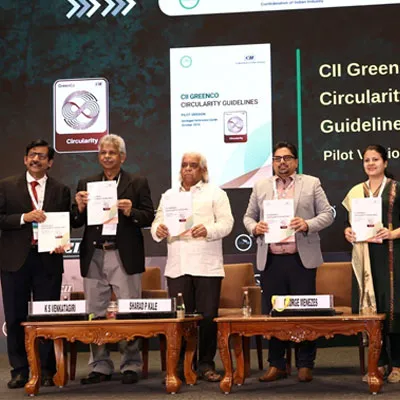
CII GreenCo Launches Circularity Guidelines for Indian Industry

The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

Global Electronics Association Launches IPC-1783-CO2E Standard

The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code