+
GST payable on maintenance charges
Real Estate

GST payable on maintenance charges

The finance ministry on July 22, 2019, had mentioned that a GST rate of 18 per cent applied to the flat owners if their monthly contribution to the residents’ welfare association (RWA) exceeded Rs 7,500.

With this background, a Nariman Point cooperative housing society (CHS) had filed an appeal against this order. But its efforts proved ineffectual as the GST Appellate authority for advance rulings, Maharashtra bench upheld the previous ruling and stated that GST has to be collected on the maintenance charges if it exceeds the threshold limit.

July 14 ruling of Authority for Advance Ruling (AAR) Maharashtra stated that activities of Nariman CHS towards its members were “taxable supplies” under the GST Act.

Various tax experts were not satisfied with this ruling as they did not think that these activities could be construed as ‘supply’ of services. Also, often certain tax scrutineer’s consider temporary tax cuts as a good fix in a downturn.

However, the Nariman CHS went on to highlight the point that it did not “supply” any service to its members. Also, in its appeal, the CHS had mentioned that AAR had failed to consider various judicial decisions especially that of the Supreme Court in 2009 case of Calcutta club which dealt with the ‘doctrine of mutuality’. This principle elucidates that the society and its members are not distinct entities further helping CHS in consolidating the point that CHS was not supplying any goods or services and henceforth does not come under the purview of GST.

But the appellate bench negated all these contentions and stated that the Supreme Court’s order was not applicable here as this order was relevant during the sales tax regime and the concept of supply has evolved to develop a wider meaning under the GST law.

To reiterate, the following conditions need to be satisfied for the application of GST on maintenance charges:
1. The aggregate of the charges levied by the society should exceed Rs 20 lakhs in a financial year and
2. The amount of the monthly maintenance charge for the particular flat or office should exceed Rs 7,500.

So, if the aggregate of maintenance charges levied by the housing society exceeds the threshold of Rs 20 lakhs in a financial year, it has to register itself under the GST laws and obtain a registration number.

Additionally, it is important to note that society does not have to levy GST on all the components billed in the invoice to the members. For example, the housing society cannot levy GST on charges which are in the nature of reimbursement of expenses is such that it is incurred by the society and recovered from its members such as various taxes and utility payments made by the housing society on behalf of the members. However, the housing society has to levy GST on the contribution made by the members towards the repairs funds.


The finance ministry on July 22, 2019, had mentioned that a GST rate of 18 per cent applied to the flat owners if their monthly contribution to the residents’ welfare association (RWA) exceeded Rs 7,500.With this background, a Nariman Point cooperative housing society (CHS) had filed an appeal against this order. But its efforts proved ineffectual as the GST Appellate authority for advance rulings, Maharashtra bench upheld the previous ruling and stated that GST has to be collected on the maintenance charges if it exceeds the threshold limit.July 14 ruling of Authority for Advance Ruling (AAR) Maharashtra stated that activities of Nariman CHS towards its members were “taxable supplies” under the GST Act.Various tax experts were not satisfied with this ruling as they did not think that these activities could be construed as ‘supply’ of services. Also, often certain tax scrutineer’s consider temporary tax cuts as a good fix in a downturn.However, the Nariman CHS went on to highlight the point that it did not “supply” any service to its members. Also, in its appeal, the CHS had mentioned that AAR had failed to consider various judicial decisions especially that of the Supreme Court in 2009 case of Calcutta club which dealt with the ‘doctrine of mutuality’. This principle elucidates that the society and its members are not distinct entities further helping CHS in consolidating the point that CHS was not supplying any goods or services and henceforth does not come under the purview of GST.But the appellate bench negated all these contentions and stated that the Supreme Court’s order was not applicable here as this order was relevant during the sales tax regime and the concept of supply has evolved to develop a wider meaning under the GST law.To reiterate, the following conditions need to be satisfied for the application of GST on maintenance charges:1. The aggregate of the charges levied by the society should exceed Rs 20 lakhs in a financial year and2. The amount of the monthly maintenance charge for the particular flat or office should exceed Rs 7,500.So, if the aggregate of maintenance charges levied by the housing society exceeds the threshold of Rs 20 lakhs in a financial year, it has to register itself under the GST laws and obtain a registration number.Additionally, it is important to note that society does not have to levy GST on all the components billed in the invoice to the members. For example, the housing society cannot levy GST on charges which are in the nature of reimbursement of expenses is such that it is incurred by the society and recovered from its members such as various taxes and utility payments made by the housing society on behalf of the members. However, the housing society has to levy GST on the contribution made by the members towards the repairs funds.

Related Stories

Gold Stories
Next Story
Infrastructure Urban

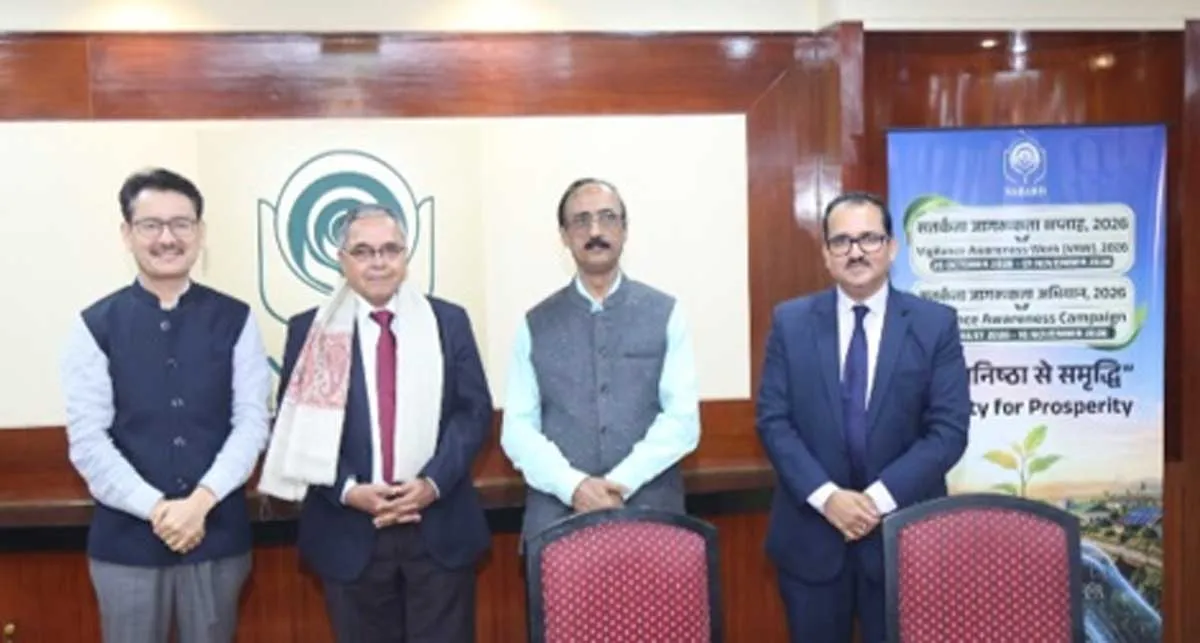
NABARD Holds Seminar on Vigilance, Integrity and Good Governance

National Bank for Agriculture and Rural Development (NABARD) organised a seminar on “Vigilance: Strengthening Integrity and Good Governance” on 25 August 2026 at its Head Office in Mumbai as part of the ongoing Vigilance Awareness Campaign 2026 being observed from 17 August to 16 November 2026, with the theme “Probity for Prosperity."" The seminar was graced by Suresh N Patel, Former Central Vigilance Commissioner, Government of India, as the chief guest and keynote speaker.  The programme was attended by G S Rawat, Deputy Managing Director, Dr Ajay K Sood, Deputy Managing Dire..
Next Story
Equipment

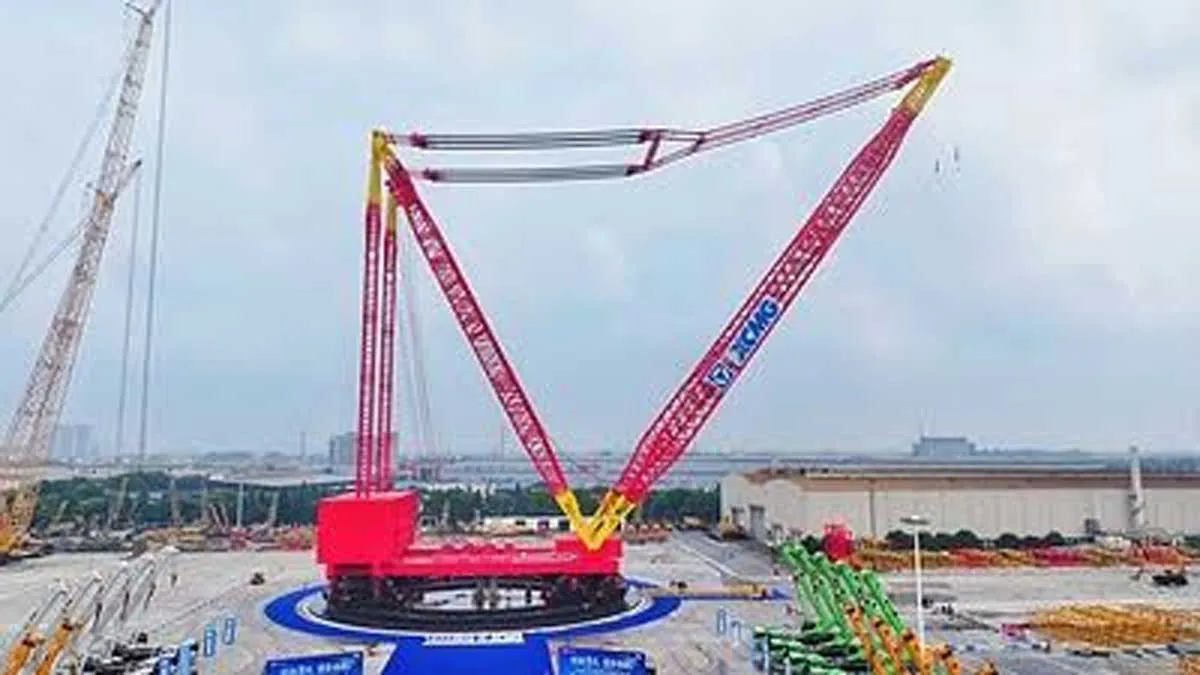
XCMG Unveils World's First 14,000-Ton Ring Crane for Heavy Lifting

XCMG has announced that the first main unit of the world's first 14,000-ton ring crane has rolled off the production line, marking a historic breakthrough in ultra-heavy lifting technology. Jointly developed by XCMG and Sinopec Heavy Lifting & Transportation Co., Ltd., the crane will be the largest-capacity ring crane ever built, setting a new benchmark for major construction projects worldwide.The crane features a modular configuration comprising two main units that work in tandem. The first main unit has completed final assembly and can independently perform lifting operations. Once both..
Next Story
Infrastructure Urban

Thriveni Logistics orders 200 tip trailers from Jagdamba trailers

Jagdamba Trailers (JTPL), one of India’s growing trailer manufacturers, has secured a significant order for 200 Tip Trailers from Thriveni Transport and Logistics Pvt. Ltd., a leading mining and logistics company serving operations across India and overseas.The order, placed for iron ore transportation, is a major milestone for JTPL, particularly as the company secured the business after competing with more than 10 established trailer manufacturers. It also strengthens an already successful relationship between the two companies. Approximately one and a half years ago, Thriveni Transport and..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code