+
Hyderabad Holds Highest Vacant Office Stock of 28 Mn Sq Ft: Vestian
Real Estate

Hyderabad Holds Highest Vacant Office Stock of 28 Mn Sq Ft: Vestian

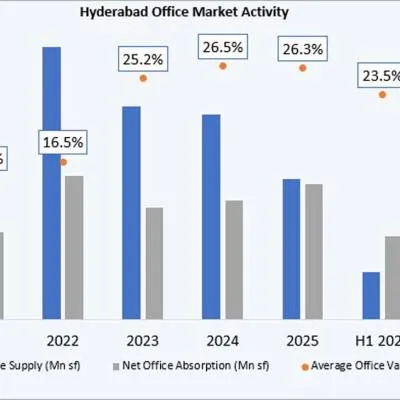
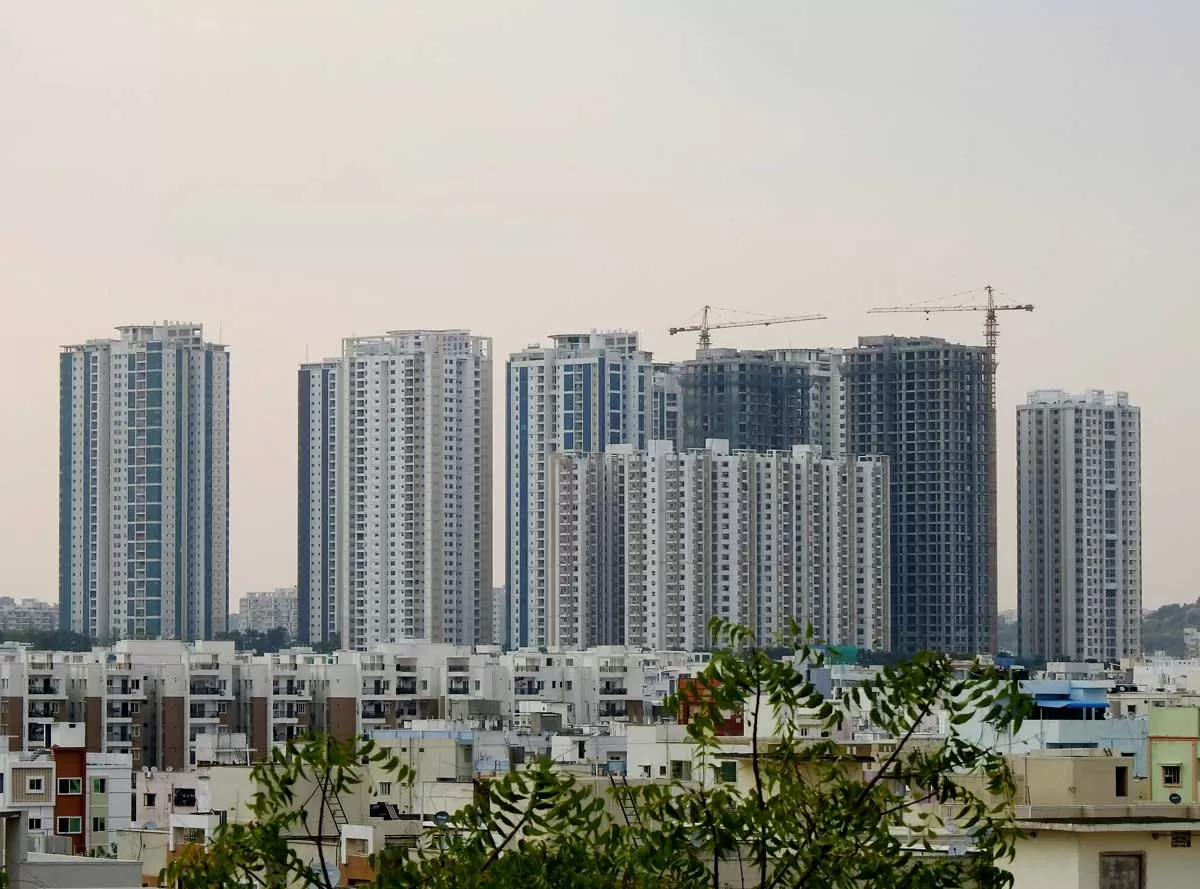
Hyderabad reported 59.0 million sq ft of new completions and 48.5 million sq ft of absorption since 2020. The trend of new completions surpassing absorption for five consecutive years has led to a significant rise in vacant office stock. As of Q1 2025, the city holds 28 million sq ft of vacant stock, the highest among the top seven cities. Despite robust demand, the stock is expected to rise further in 2025 on the back of a strong pipeline of upcoming supply in the city. However, pan-India construction activities slowed down by 39% on quarter and 12% over the previous year, reaching 9.50 million sq ft in Q1 2025. This slowdown can be attributed to the absence of new supply in Hyderabad and minimal supply additions in Chennai, Mumbai, and Kolkata during Q1 2025.

Conversely, the first quarter of 2025 witnessed sustained leasing activities across the top seven cities amid global macroeconomic uncertainty. As a result, absorption rose by 34% in Q1 2025 compared to the same period a year earlier, reaching 17.96 million sq ft. This can be attributed to the significant increase in real estate activities in the western cities (Mumbai and Pune), with the share rising from 24% in Q1 2024 to 37% in Q1 2025.

Moreover, the sudden rise of artificial intelligence altered the growth trajectory of the IT industry. This could be substantiated by the continuous dominance of IT-ITeS sector in the absorption. The sector accounted for 34% of the pan-India absorption in Q1 2025 and 36% in the previous quarter.

Shrinivas Rao, FRICS, CEO, Vestian said, “India’s office market maintained its growth momentum in Q1 2025, driven by sustained demand across the major office markets in India. Even though the absorption decreased over the previous quarter, demand for office spaces by GCCs, IT-ITeS, BFSI, and Flex Spaces is expected to swell in the forthcoming quarters.”

City-wise analysis

  • Bengaluru dominated pan-India absorption with 4.08 million sq ft in Q1 2025, closely followed by Mumbai with 3.99 million sq ft. Kolkata reported the lowest absorption of 0.23 million sq ft during Q1 2025, however, it increased by 44% on year and 289% over the previous quarter.
  • Despite a quarterly decline of 3% in value terms, the share of Bengaluru in pan-India absorption increased to 23% in Q1 2025 from 19% a quarter earlier. Similarly, the share of Mumbai also rose marginally by one percentage point to 22% in Q1 2025 despite an 11% decline in value terms.
  • Pune reported an annual increase of 276% in absorption, with its pan-India share rising from 5% in Q1 2024 to 15% in Q1 2025. Conversely, Chennai witnessed the highest annual drop of 52% with its share declining from 25% to 9% during the same period stated above.
  • Bengaluru led the absorption by GCCs among the top seven cities with 39% share in Q1 2025, registering a 39% QoQ and 119% YoY increase in value terms.
  • While Bengaluru led new completions in Q1 2025 with 37% share, Pune followed with 31% share. Bengaluru’s share increased from 21% in the previous quarter, whereas Pune’s share rose from 15%.
  • New completions in NCR doubled to 2.6 million sq ft in Q1 2025 compared to the same period a year ago. It also increased by 44% over the previous quarter.

Hyderabad reported 59.0 million sq ft of new completions and 48.5 million sq ft of absorption since 2020. The trend of new completions surpassing absorption for five consecutive years has led to a significant rise in vacant office stock. As of Q1 2025, the city holds 28 million sq ft of vacant stock, the highest among the top seven cities. Despite robust demand, the stock is expected to rise further in 2025 on the back of a strong pipeline of upcoming supply in the city. However, pan-India construction activities slowed down by 39% on quarter and 12% over the previous year, reaching 9.50 million sq ft in Q1 2025. This slowdown can be attributed to the absence of new supply in Hyderabad and minimal supply additions in Chennai, Mumbai, and Kolkata during Q1 2025.Conversely, the first quarter of 2025 witnessed sustained leasing activities across the top seven cities amid global macroeconomic uncertainty. As a result, absorption rose by 34% in Q1 2025 compared to the same period a year earlier, reaching 17.96 million sq ft. This can be attributed to the significant increase in real estate activities in the western cities (Mumbai and Pune), with the share rising from 24% in Q1 2024 to 37% in Q1 2025.Moreover, the sudden rise of artificial intelligence altered the growth trajectory of the IT industry. This could be substantiated by the continuous dominance of IT-ITeS sector in the absorption. The sector accounted for 34% of the pan-India absorption in Q1 2025 and 36% in the previous quarter.Shrinivas Rao, FRICS, CEO, Vestian said, “India’s office market maintained its growth momentum in Q1 2025, driven by sustained demand across the major office markets in India. Even though the absorption decreased over the previous quarter, demand for office spaces by GCCs, IT-ITeS, BFSI, and Flex Spaces is expected to swell in the forthcoming quarters.”City-wise analysisBengaluru dominated pan-India absorption with 4.08 million sq ft in Q1 2025, closely followed by Mumbai with 3.99 million sq ft. Kolkata reported the lowest absorption of 0.23 million sq ft during Q1 2025, however, it increased by 44% on year and 289% over the previous quarter.Despite a quarterly decline of 3% in value terms, the share of Bengaluru in pan-India absorption increased to 23% in Q1 2025 from 19% a quarter earlier. Similarly, the share of Mumbai also rose marginally by one percentage point to 22% in Q1 2025 despite an 11% decline in value terms.Pune reported an annual increase of 276% in absorption, with its pan-India share rising from 5% in Q1 2024 to 15% in Q1 2025. Conversely, Chennai witnessed the highest annual drop of 52% with its share declining from 25% to 9% during the same period stated above.Bengaluru led the absorption by GCCs among the top seven cities with 39% share in Q1 2025, registering a 39% QoQ and 119% YoY increase in value terms.While Bengaluru led new completions in Q1 2025 with 37% share, Pune followed with 31% share. Bengaluru’s share increased from 21% in the previous quarter, whereas Pune’s share rose from 15%.New completions in NCR doubled to 2.6 million sq ft in Q1 2025 compared to the same period a year ago. It also increased by 44% over the previous quarter.

Related Stories

Gold Stories
Next Story
Real Estate

Peninsula Land launches 19 luxury villas in Pune

Pune’s residential landscape is witnessing a shift as premium homebuyers increasingly seek larger spaces, privacy and independent living options beyond high-rise apartments. Addressing this demand, Peninsula Land Limited, part of the Ashok Piramal Group, has launched AshokVillas, an exclusive collection of 19 premium furnished villas in Gahunje, Pune.The development combines the independence of a standalone home with the convenience and security of a managed residential community. Designed around low-density horizontal living, AshokVillas offers residents private spaces while providing acces..
Next Story
Infrastructure Urban

MyBranch Expands South India Network with 16 Workspace Centres

MyBranch has expanded its South India presence with a 50,000 sq ft flexible workspace network comprising 16 centres across 14 cities in Andhra Pradesh, Karnataka, Tamil Nadu and Telangana.The expansion reflects growing demand for flexible office infrastructure as businesses establish regional teams, satellite offices and operations beyond traditional metropolitan markets. MyBranch’s network spans Bengaluru, Coimbatore, Guntur, Hanamkonda, Hubballi, Hyderabad, Madurai, Mangaluru, Rajahmundry, Salem, Tirupati, Vellore, Vijayawada and Visakhapatnam, with a large office space in Chennai also und..
Next Story
Building Material

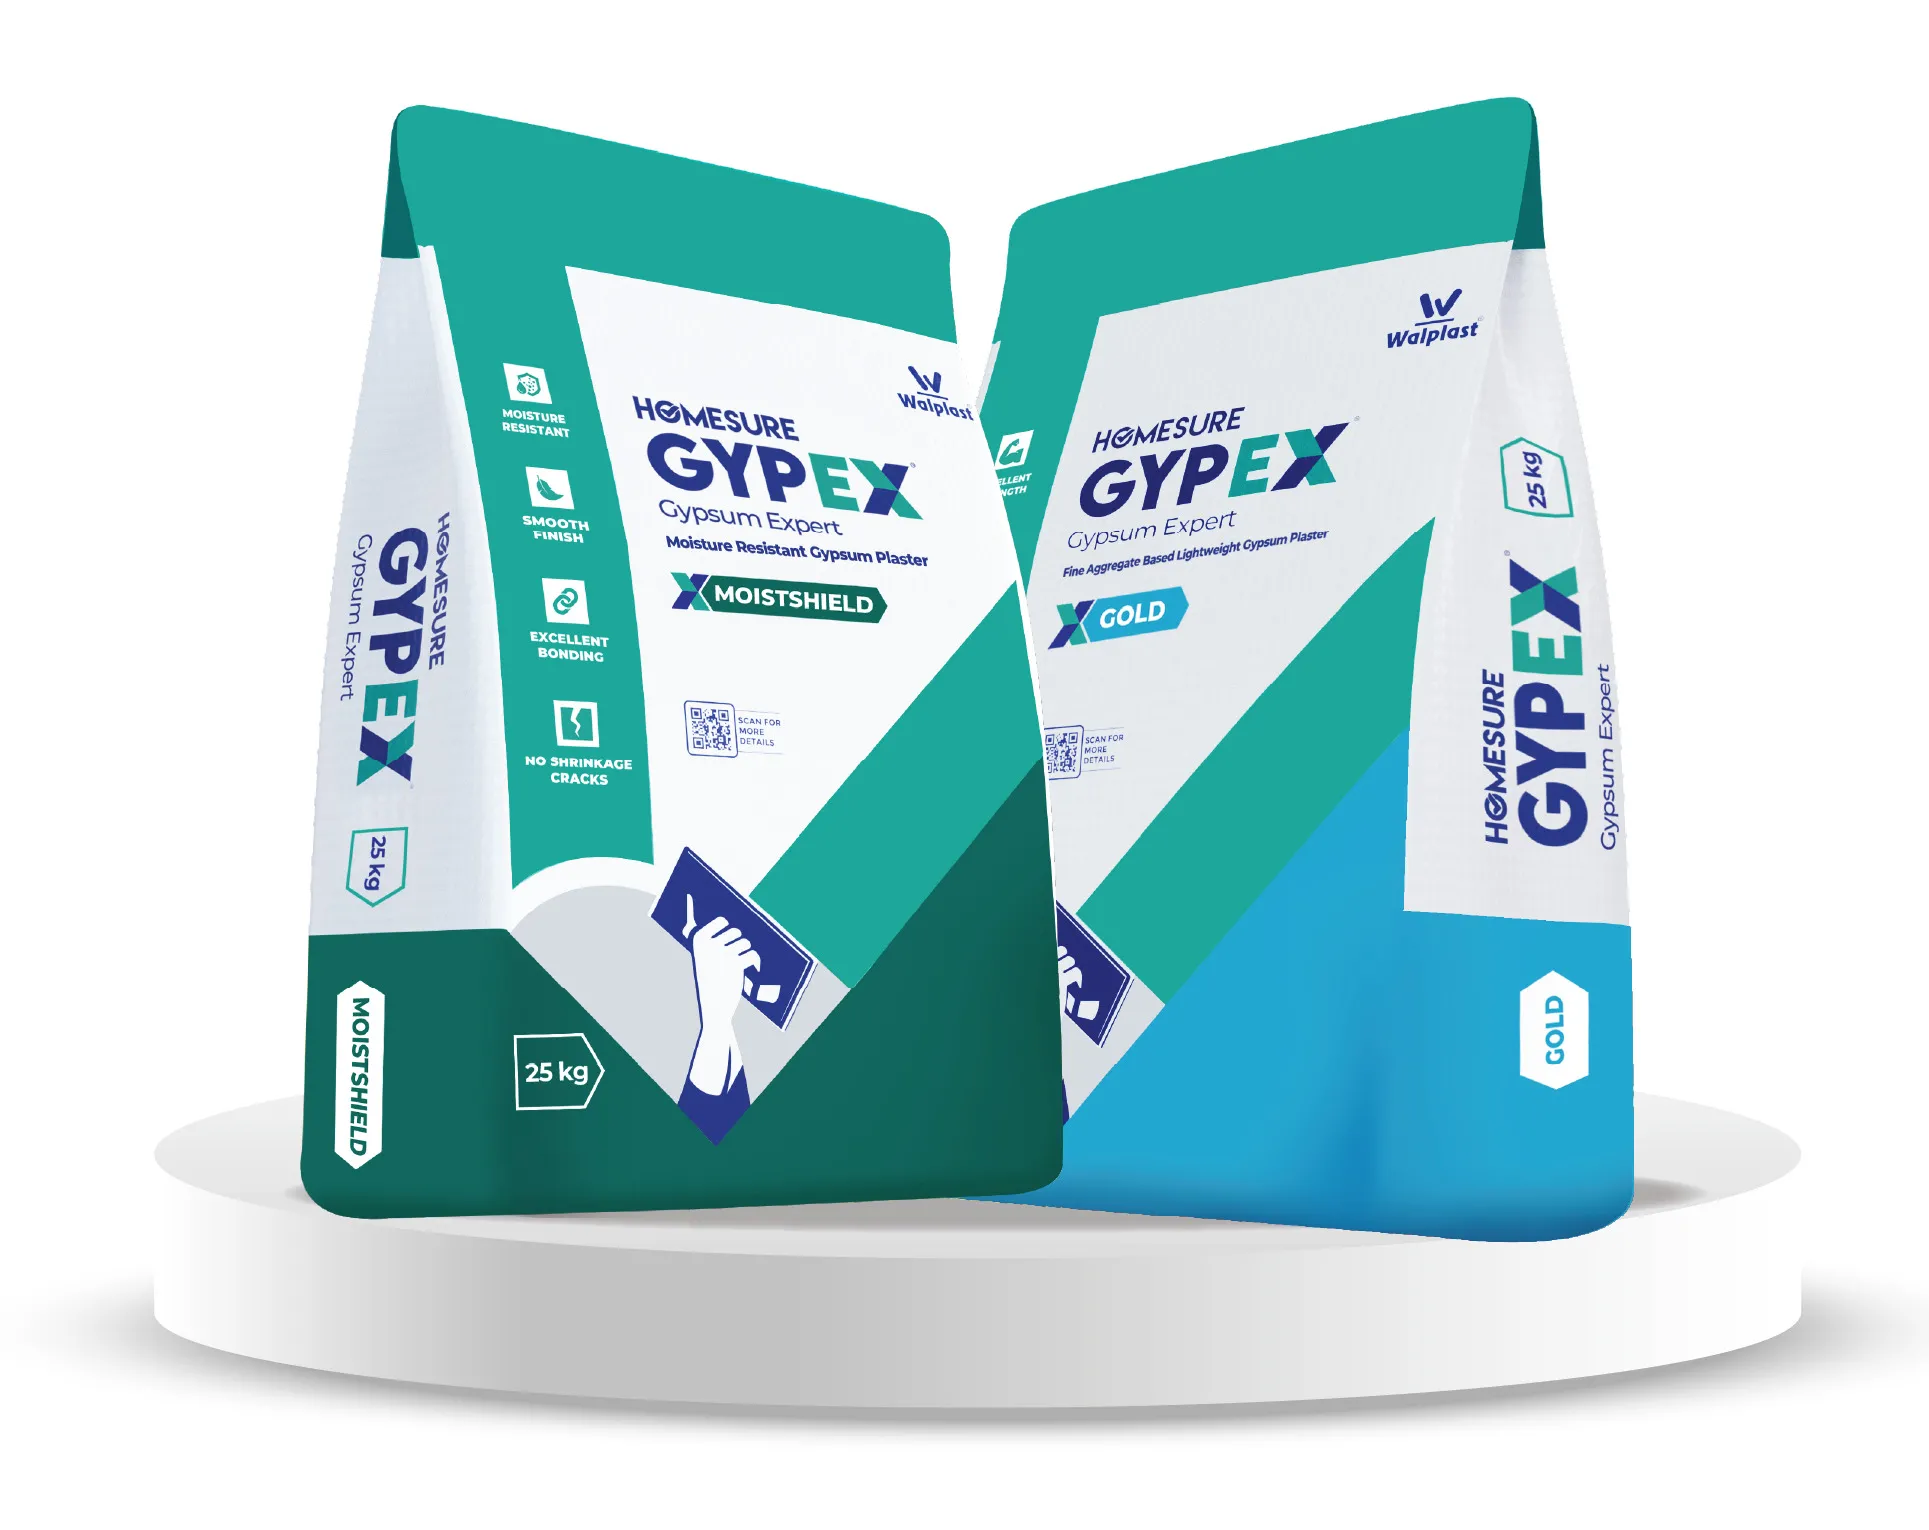
Walplast Launches Moisture-Resistant Gypsum Plaster Solutions

Walplast Products Pvt. Ltd. has expanded its HomeSure GypEx portfolio with the launch of GypEx MoistShield and GypEx Gold, two gypsum plaster solutions designed to address moisture-prone applications and improve plastering efficiency.The new products have been developed in response to the growing demand for faster construction processes, improved material performance and consistent surface quality. The solutions aim to simplify interior plastering while addressing specific application requirements across construction environments.“Through HomeSure GypEx MoistShield and GypEx Gold, we are exp..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code