+
Real Estate Sees Capital Shift as Formalisation Drives Demand
Real Estate

Real Estate Sees Capital Shift as Formalisation Drives Demand

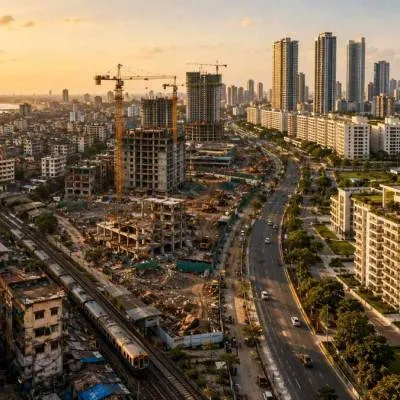
India’s real estate sector is undergoing a structural transformation marked by formalisation, premiumisation, and consolidation—driving a surging demand for capital and prompting a shift beyond traditional funding sources. 

In its fourth evolutionary phase, the sector has seen a rising share of luxury residential units and Grade A offices, an uptick in co-working spaces due to hybrid work models, and dominance by listed national players. Formalisation, initiated by RERA and IBC, has intensified, fuelling the appetite for funding. While promoters are increasingly using QIPs to raise equity, banks—with over Rs 35 trillion in exposure—remain the primary source of debt. However, regulatory limitations and risk aversion have curtailed their participation in early-stage development, particularly in land acquisition and stressed assets. 

During the 2010s, NBFCs filled this gap by funding early-stage commercial real estate. But following defaults, poor liability management, and regulatory tightening, they have ceded space to Alternative Investment Funds (AIFs). With the exit of some NBFCs and tighter RBI norms, AIFs have become the dominant players in high-risk, high-reward segments. Real estate now leads sectoral AIF investments, almost twice that of the next sector, indicating strong investor confidence and a maturing fundraising ecosystem. 

Commercial real estate, especially office space, offers robust growth opportunities. In CY24, office leasing surpassed previous records by 20 per cent, accompanied by rising rents and lower vacancies. CY25 continues this trend, led by demand from Bangalore, Delhi NCR, and Pune. Global Capability Centres (GCCs) are expanding their India footprint beyond back-office roles, with their numbers expected to grow 1.3x in the next few years. Flex space operators are thriving, evidenced by successful IPOs. A vibrant start-up and MSME environment further bolsters this outlook. REITs are positioning themselves to capitalise on these opportunities. 

India’s REIT ecosystem, built around office assets, has grown at a 30 per cent CAGR over five years, supported by new launches and ROFO-based acquisitions. Despite pandemic disruptions, REITs have delivered stable, tax-efficient distributions. With nearly 500 million sq ft of untapped Grade A office space, there’s an estimated REITable value of Rs 7 trillion. To emulate mature markets like the US—where 98 per cent of listed real estate is REIT-based—India must expand into segments like retail, hotels, and warehousing. 

Regulatory reforms are paving the way for broader investor participation. Sponsor stake dilution is enabling capital recycling, with average holdings falling from nearly 50 per cent to below one-third by June 2025. Institutional ownership (DIIs and FIIs) has increased from 28 per cent to 46 per cent, led by domestic institutions, thanks to supportive regulatory changes. However, retail participation remains limited. A broader asset base and consistent supply of investment-grade properties could drive REIT AUM growth at a 25–30 per cent CAGR in the coming years. 

India’s real estate sector is undergoing a structural transformation marked by formalisation, premiumisation, and consolidation—driving a surging demand for capital and prompting a shift beyond traditional funding sources. In its fourth evolutionary phase, the sector has seen a rising share of luxury residential units and Grade A offices, an uptick in co-working spaces due to hybrid work models, and dominance by listed national players. Formalisation, initiated by RERA and IBC, has intensified, fuelling the appetite for funding. While promoters are increasingly using QIPs to raise equity, banks—with over Rs 35 trillion in exposure—remain the primary source of debt. However, regulatory limitations and risk aversion have curtailed their participation in early-stage development, particularly in land acquisition and stressed assets. During the 2010s, NBFCs filled this gap by funding early-stage commercial real estate. But following defaults, poor liability management, and regulatory tightening, they have ceded space to Alternative Investment Funds (AIFs). With the exit of some NBFCs and tighter RBI norms, AIFs have become the dominant players in high-risk, high-reward segments. Real estate now leads sectoral AIF investments, almost twice that of the next sector, indicating strong investor confidence and a maturing fundraising ecosystem. Commercial real estate, especially office space, offers robust growth opportunities. In CY24, office leasing surpassed previous records by 20 per cent, accompanied by rising rents and lower vacancies. CY25 continues this trend, led by demand from Bangalore, Delhi NCR, and Pune. Global Capability Centres (GCCs) are expanding their India footprint beyond back-office roles, with their numbers expected to grow 1.3x in the next few years. Flex space operators are thriving, evidenced by successful IPOs. A vibrant start-up and MSME environment further bolsters this outlook. REITs are positioning themselves to capitalise on these opportunities. India’s REIT ecosystem, built around office assets, has grown at a 30 per cent CAGR over five years, supported by new launches and ROFO-based acquisitions. Despite pandemic disruptions, REITs have delivered stable, tax-efficient distributions. With nearly 500 million sq ft of untapped Grade A office space, there’s an estimated REITable value of Rs 7 trillion. To emulate mature markets like the US—where 98 per cent of listed real estate is REIT-based—India must expand into segments like retail, hotels, and warehousing. Regulatory reforms are paving the way for broader investor participation. Sponsor stake dilution is enabling capital recycling, with average holdings falling from nearly 50 per cent to below one-third by June 2025. Institutional ownership (DIIs and FIIs) has increased from 28 per cent to 46 per cent, led by domestic institutions, thanks to supportive regulatory changes. However, retail participation remains limited. A broader asset base and consistent supply of investment-grade properties could drive REIT AUM growth at a 25–30 per cent CAGR in the coming years. 

Related Stories

Gold Stories

Next Story
Infrastructure Urban

NABARD Holds Seminar on Vigilance, Integrity and Good Governance

National Bank for Agriculture and Rural Development (NABARD) organised a seminar on “Vigilance: Strengthening Integrity and Good Governance” on 25 August 2026 at its Head Office in Mumbai as part of the ongoing Vigilance Awareness Campaign 2026 being observed from 17 August to 16 November 2026, with the theme “Probity for Prosperity."" The seminar was graced by Suresh N Patel, Former Central Vigilance Commissioner, Government of India, as the chief guest and keynote speaker.  The programme was attended by G S Rawat, Deputy Managing Director, Dr Ajay K Sood, Deputy Managing Dire..
Next Story
Equipment

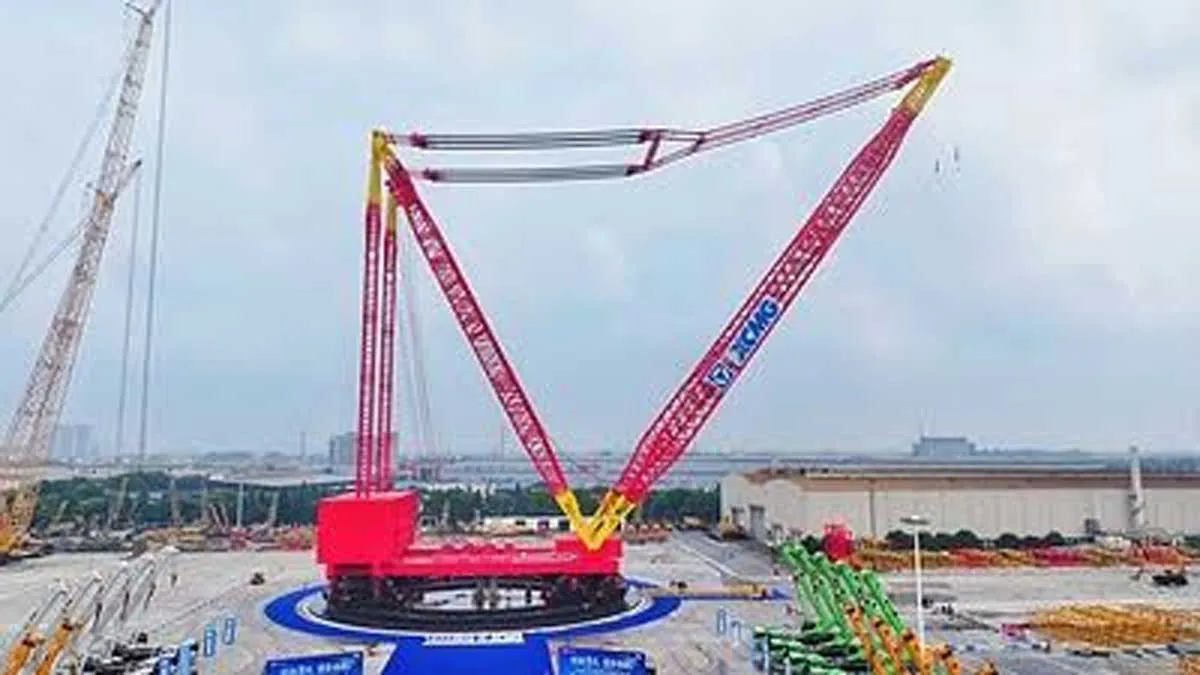
XCMG Unveils World's First 14,000-Ton Ring Crane for Heavy Lifting

XCMG has announced that the first main unit of the world's first 14,000-ton ring crane has rolled off the production line, marking a historic breakthrough in ultra-heavy lifting technology. Jointly developed by XCMG and Sinopec Heavy Lifting & Transportation Co., Ltd., the crane will be the largest-capacity ring crane ever built, setting a new benchmark for major construction projects worldwide.The crane features a modular configuration comprising two main units that work in tandem. The first main unit has completed final assembly and can independently perform lifting operations. Once both..
Next Story
Infrastructure Urban

Thriveni Logistics orders 200 tip trailers from Jagdamba trailers

Jagdamba Trailers (JTPL), one of India’s growing trailer manufacturers, has secured a significant order for 200 Tip Trailers from Thriveni Transport and Logistics Pvt. Ltd., a leading mining and logistics company serving operations across India and overseas.The order, placed for iron ore transportation, is a major milestone for JTPL, particularly as the company secured the business after competing with more than 10 established trailer manufacturers. It also strengthens an already successful relationship between the two companies. Approximately one and a half years ago, Thriveni Transport and..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code