Cement Margins To Contract In Q2 Recovery Likely In H2FY27
ECONOMY & POLICY

Cement Margins To Contract In Q2 Recovery Likely In H2FY27

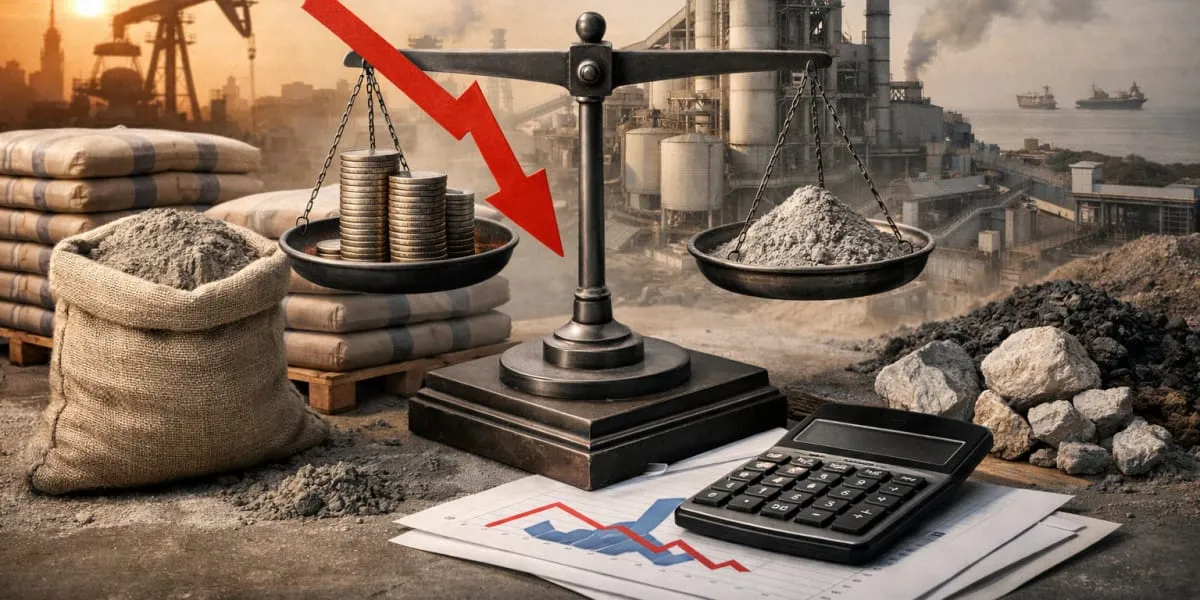
HDFC Securities reported that cement industry margins are expected to contract by over Rs 100 per metric tonne (t) to below Rs 880 per t in the second quarter on a quarter-on-quarter basis. The firm added that margins could recover in the second half of FY27 if West Asia turmoil subsides and commodity cost pressures ease. The assessment reflects seasonal demand weakness and rising input costs.

The report said cement prices are not expected to rise quarter on quarter as demand softens with the monsoon. It warned that fuel cost pressures, including higher coal and pet coke prices, will build QoQ and that seasonal operating leverage losses will weigh on profitability. HDFC Securities expected coal and pet coke costs to peak in Q2FY27 while PVC resin movements will push packaging costs higher before a cool off.

Demand trends during the quarter were described as volatile, with offtake muted in May and improvement following a delayed monsoon in June. Pricing traction remained sub-optimal amid the combined energy and packaging cost environment, constraining producers ability to pass through higher input prices. The report estimated that average cement selling prices rose modestly by two to three per cent quarter on quarter across regions.

On volumes the research house estimated aggregate volumes for its coverage universe to rise by around seven per cent year on year, which implied an approximate ten per cent quarter on quarter seasonal decline. On realisation it projected an average net selling revenue increase of two point five per cent quarter on quarter while remaining flattish year on year. The firm continued to express confidence in long term demand drivers.

HDFC Securities concluded that a combination of eventual cost cool off and steady demand should support a margin rebound from H2FY27 onwards, provided geopolitical pressures abate. It forecast that the coverage universe would deliver roughly eight point five per cent volume compound annual growth rate over FY26 to FY28E, underpinning a recovery in realisations and operating margins as the year progresses.

HDFC Securities reported that cement industry margins are expected to contract by over Rs 100 per metric tonne (t) to below Rs 880 per t in the second quarter on a quarter-on-quarter basis. The firm added that margins could recover in the second half of FY27 if West Asia turmoil subsides and commodity cost pressures ease. The assessment reflects seasonal demand weakness and rising input costs. The report said cement prices are not expected to rise quarter on quarter as demand softens with the monsoon. It warned that fuel cost pressures, including higher coal and pet coke prices, will build QoQ and that seasonal operating leverage losses will weigh on profitability. HDFC Securities expected coal and pet coke costs to peak in Q2FY27 while PVC resin movements will push packaging costs higher before a cool off. Demand trends during the quarter were described as volatile, with offtake muted in May and improvement following a delayed monsoon in June. Pricing traction remained sub-optimal amid the combined energy and packaging cost environment, constraining producers ability to pass through higher input prices. The report estimated that average cement selling prices rose modestly by two to three per cent quarter on quarter across regions. On volumes the research house estimated aggregate volumes for its coverage universe to rise by around seven per cent year on year, which implied an approximate ten per cent quarter on quarter seasonal decline. On realisation it projected an average net selling revenue increase of two point five per cent quarter on quarter while remaining flattish year on year. The firm continued to express confidence in long term demand drivers. HDFC Securities concluded that a combination of eventual cost cool off and steady demand should support a margin rebound from H2FY27 onwards, provided geopolitical pressures abate. It forecast that the coverage universe would deliver roughly eight point five per cent volume compound annual growth rate over FY26 to FY28E, underpinning a recovery in realisations and operating margins as the year progresses.

Related Stories

Gold Stories

Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code