ICRA revises outlook for CV industry; projects 0-3% growth in FY25
ECONOMY & POLICY

ICRA revises outlook for CV industry; projects 0-3% growth in FY25

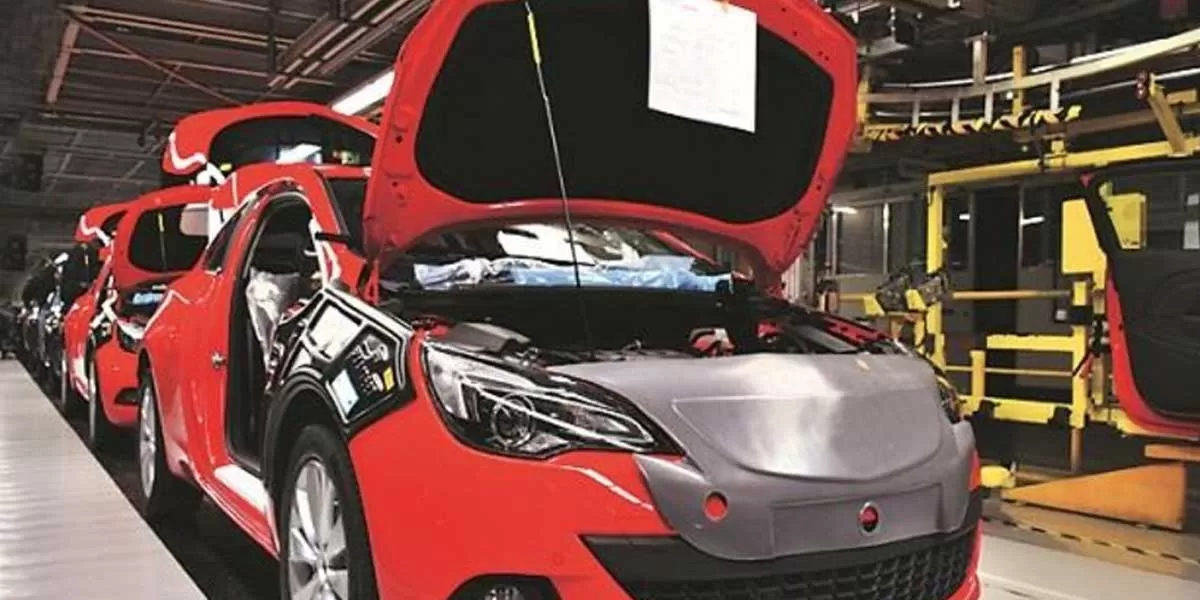
ICRA has revised its forecast for the commercial vehicle (CV) industry, now expecting a modest year-on-year growth of 0-3% in domestic wholesale volumes for FY25, up from the previously anticipated decline of 4-7%. This adjustment follows stronger-than-expected growth in the first four months of FY25 and a projected demand recovery in the latter half of the fiscal year. This marks the second consecutive year of slight growth, following a 1% and 3% Y-o-Y increase in wholesale and retail sales, respectively, in FY24.

Kinjal Shah, Senior Vice President & Co-Group Head ? Corporate Ratings, ICRA, attributed the market dynamics to several factors, including a slowdown in infrastructure activities during the General Elections and extreme heatwaves across the country, which affected demand in Q1 FY25. Despite these challenges, volumes exceeded ICRA's expectations. Looking ahead, Shah expects a recovery in H2 FY25, driven by government and private sector capital expenditure, improved rural demand linked to Kharif crop output, and healthy replacement demand due to an aging fleet.

Shah emphasised the long-term growth drivers for the CV industry, such as continued infrastructure development, increased mining activities, and improved road and highway connectivity, which are expected to support sustained growth.

- Medium and Heavy Commercial Vehicles (M&HCVs): This segment is projected to experience a nominal growth of 0-3% Y-o-Y in FY25, influenced by a high base effect and the impact of the General Elections on infrastructure activities. While FY24 ended with flat volumes, Q1 FY25 saw a mixed performance, with tippers contracting by 4% Y-o-Y and the haulage sub-segment growing by 3%. Tractor-trailers recorded a 7% Y-o-Y increase in Q1 FY25.

- Light Commercial Vehicles (LCVs): The LCV segment is expected to see negligible growth, ranging from -1% to 2% Y-o-Y in FY25, due to a high base effect, ongoing e-commerce slowdown, and competition from electric three-wheelers (e3Ws). FY24 saw a mild 3% decline in this segment, exacerbated by factors like a weak rural economy and rising ownership costs, which have increased the preference for pre-owned vehicles among small fleet operators.

- Bus segment: The bus segment is anticipated to grow by 8-11% Y-o-Y in FY25, driven by replacement demand from state road transport undertakings (SRTUs) scrapping older vehicles. This segment gained momentum in FY24, surpassing pre-COVID levels.

Diesel continues to dominate the domestic CV industry, with over 90% market penetration. In FY24, alternative fuels like CNG, LNG, and electric vehicles (EVs) accounted for about 9% of sales, with the highest EV penetration in the bus segment (7%).

ICRA projects the operating profit margin (OPM) of domestic CV original equipment manufacturers (OEMs) to range between 9.5%-10.5% in FY25, slightly down from 10.7% in FY24. This decline is attributed to muted volumes and increased competitive pricing, though cost improvements, favorable raw material prices, and product discipline are expected to provide some support. Capital expenditures and investments are expected to rise to approximately INR 56-58 billion in FY25, focusing on product development, alternate powertrains, technology upgrades, and maintenance.

Shah noted that the industry's credit metrics should remain stable in FY25, even with marginally contracted margins and increased capex. The industry's strong operating performance is expected to support its coverage metrics, with Total Debt/OPBITDA projected at 1.2-1.4 times by March 31, 2025, compared to 1.5 times in the previous year, and interest coverage at 6.8-7.2x in FY25, against 7.2x in FY24. Shah's analysis underscores both the challenges and opportunities within the domestic CV market for the upcoming fiscal year.

(ET)

ICRA has revised its forecast for the commercial vehicle (CV) industry, now expecting a modest year-on-year growth of 0-3% in domestic wholesale volumes for FY25, up from the previously anticipated decline of 4-7%. This adjustment follows stronger-than-expected growth in the first four months of FY25 and a projected demand recovery in the latter half of the fiscal year. This marks the second consecutive year of slight growth, following a 1% and 3% Y-o-Y increase in wholesale and retail sales, respectively, in FY24. Kinjal Shah, Senior Vice President & Co-Group Head ? Corporate Ratings, ICRA, attributed the market dynamics to several factors, including a slowdown in infrastructure activities during the General Elections and extreme heatwaves across the country, which affected demand in Q1 FY25. Despite these challenges, volumes exceeded ICRA's expectations. Looking ahead, Shah expects a recovery in H2 FY25, driven by government and private sector capital expenditure, improved rural demand linked to Kharif crop output, and healthy replacement demand due to an aging fleet. Shah emphasised the long-term growth drivers for the CV industry, such as continued infrastructure development, increased mining activities, and improved road and highway connectivity, which are expected to support sustained growth. - Medium and Heavy Commercial Vehicles (M&HCVs): This segment is projected to experience a nominal growth of 0-3% Y-o-Y in FY25, influenced by a high base effect and the impact of the General Elections on infrastructure activities. While FY24 ended with flat volumes, Q1 FY25 saw a mixed performance, with tippers contracting by 4% Y-o-Y and the haulage sub-segment growing by 3%. Tractor-trailers recorded a 7% Y-o-Y increase in Q1 FY25. - Light Commercial Vehicles (LCVs): The LCV segment is expected to see negligible growth, ranging from -1% to 2% Y-o-Y in FY25, due to a high base effect, ongoing e-commerce slowdown, and competition from electric three-wheelers (e3Ws). FY24 saw a mild 3% decline in this segment, exacerbated by factors like a weak rural economy and rising ownership costs, which have increased the preference for pre-owned vehicles among small fleet operators. - Bus segment: The bus segment is anticipated to grow by 8-11% Y-o-Y in FY25, driven by replacement demand from state road transport undertakings (SRTUs) scrapping older vehicles. This segment gained momentum in FY24, surpassing pre-COVID levels. Diesel continues to dominate the domestic CV industry, with over 90% market penetration. In FY24, alternative fuels like CNG, LNG, and electric vehicles (EVs) accounted for about 9% of sales, with the highest EV penetration in the bus segment (7%). ICRA projects the operating profit margin (OPM) of domestic CV original equipment manufacturers (OEMs) to range between 9.5%-10.5% in FY25, slightly down from 10.7% in FY24. This decline is attributed to muted volumes and increased competitive pricing, though cost improvements, favorable raw material prices, and product discipline are expected to provide some support. Capital expenditures and investments are expected to rise to approximately INR 56-58 billion in FY25, focusing on product development, alternate powertrains, technology upgrades, and maintenance. Shah noted that the industry's credit metrics should remain stable in FY25, even with marginally contracted margins and increased capex. The industry's strong operating performance is expected to support its coverage metrics, with Total Debt/OPBITDA projected at 1.2-1.4 times by March 31, 2025, compared to 1.5 times in the previous year, and interest coverage at 6.8-7.2x in FY25, against 7.2x in FY24. Shah's analysis underscores both the challenges and opportunities within the domestic CV market for the upcoming fiscal year. (ET)

Related Stories

Gold Stories

Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code