Toll collections to grow 10-11% in FY22 despite Covid: Care Ratings
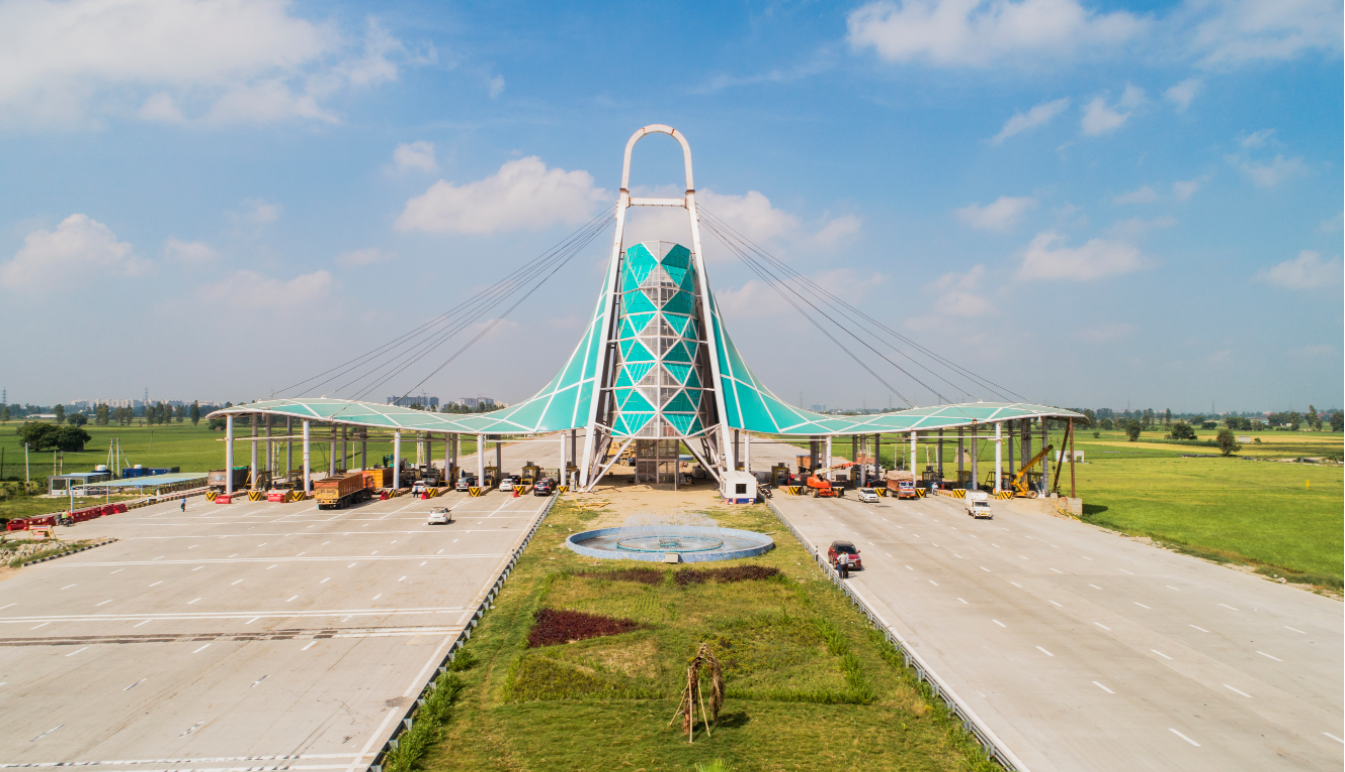
A recent study by Care Ratings pointed out that Care Ratings’ investment grade toll road portfolio is likely to deliver a stable credit performance, despite Covid. 47 out of 56 Care rated investment grade operational projects are likely to be stable from credit perspective, despite possible shocks of traffic disruption. This is on account of resilient toll collections, adequate debt coverage indicators and presence of liquidity buffers. For these projects, Care Ratings expects a debt service coverage ratio (DSCR) of at least 1.10 times for FY22, coupled with a liquidity reserve equivalent to one quarter of debt servicing amount. Balance nine projects are likely to be supported with need-based liquidity backup from the sponsors.
Toll Collections: Change in axle norms, traffic leakages to alternate routes and Covid-19 outbreak in March 2020 led to minor year-on-year (Y-o-Y) degrowth of 2.5% during FY20. In a bid to evaluate the overall sector performance during FY21, for operating toll roads in particular, Care Ratings assessed performance of 105 toll road projects (including rated by Care Ratings) admeasuring 38,000 km spanning across 15 states.

Toll revenues witnessed Y-o-Y degrowth of 10.23% in 9MFY21 as against 9MFY20 on account of the severe impact of lockdown during Q1FY21. The strong recovery in toll collections from Q3FY21 is likely to restrict the decline to 5.50% on Y-o-Y basis as against earlier expectations of over 20% degrowth for FY21.
With the onset of the second wave of Covid-19 and stringent guidelines announced by some states, passenger vehicular traffic is expected to witness a decline again in Q1FY22 after reaching closer to pre-covid levels in Q4FY21. Nevertheless, electricity consumption and Goods and Services Tax (GST) e-way bill collections, which are proxy for economic activity and movement of goods, have remained higher than Q1FY21 levels.
Read the full Care Ratings report here
Related Stories
Gold Stories

Schindler named among Forbes’ World’s Best Employers 2026
Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
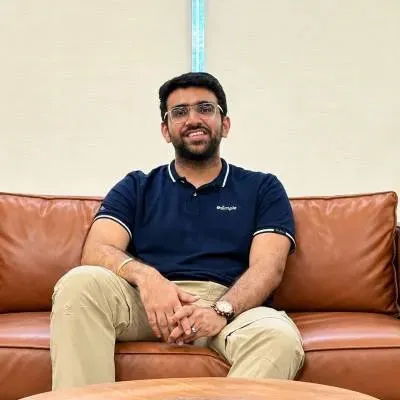
India needs an export-execution mindset: Vishesh Jain
Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Nuvoco reports 13.5% revenue growth in Q2 FY27
Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..
Related Articles
Latest Updates