Where are the orders?
Highway construction this year is even slower than 2020 – the first year of the pandemic that brought life to a grinding halt all over the world.
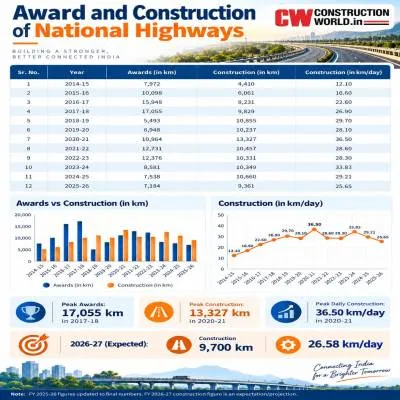
Data from the Ministry of Road Transport & Highways (MoRTH) showed that only 4,766 km of the targeted 12,000 km of highways for FY23 had been built from April to November, indicating a decline of nearly 7 per cent from 5,118 km in the same period last year. NHAI awarded 5,382 km of highways from April till November, a decline of 4 per cent against over 5,600 km of roads awarded a year earlier.
The Government constructed 10,237 km of highways in the pre-pandemic period of FY20 at 28.04 km per day. This increased in the first year of the pandemic when the country saw lockdowns, which indirectly helped accelerate construction. In FY 21, a record 13,327 km of highways were built at 36.51 km per day. However, last year in FY22 the pace has slackened to 10,457 km at 28.64 km per day.
The Ministry of Statistics & Programme Implementation (MoSPI), which measures project delays, reported that the number of projects showing cost overruns as on December 1, 2022, was 22 per cent, higher than 13 per cent in March 2018 with a cost escalation of Rs 4.5 trillion, which is 22 per cent more than the original project cost, or roughly Rs 1 trillion a year of escalation!
As I have been tracking this regularly, it now seems a foregone conclusion that the roads target of 12,000 km will not be achieved. Even though the numbers during the April-November period are not too different from those of the previous year, the tardiness despite absence of any obstacles this year is worrisome and does not infuse confidence that this is achievable in the next four months.
The year 2022 has been a mixed bag. While COVID fears receded and order books began humming, the infrastructure story did not accelerate after hitting a normal pace. Inflation hurt margins. Building material prices, particularly steel, took off vertically. Questions about the Government’s ability to spend money in infrastructure seemed validated with the tardiness in contracts awarded. Yet again, the Government diverted its core focus to elections. Exports are shaky with Europe in economic doldrums. China has just about abandoned its COVID policy of extreme caution but has been hit with a pandemic wave. Inflation is currently being battled with monetary tightening, causing interest rates to be increased, which has begun to hurt demand. Cement is facing a demand slump and the rural areas, too, have hit a pause button. However, the outcome of the rabi crop is likely to set it back on ‘play’ positively. The last quarter of this fiscal is not likely to warm the industry’s pockets even though costs have begun to rationalise. Credit disbursal is the lone bright star that continued to rise through the year.
According to CMIE, while Central Government capex spending is up, state government capex spending, which is of comparable magnitude, is sluggish. Also, new orders received by capital goods and construction companies dropped in July 2022 and have remained low since then. The average monthly orders between July and October 2022 were to the tune of Rs 142 billion, which is the lowest in many years.
We have a challenging last quarter to deal with. However, if India continues its reform programme and the ruling party does not get too involved in assembly elections, we stand a chance to attract over $ 100 billion of FDI and our PLI schemes can begin to add value to the economy.

Author: Pratap Padode is the Editor-in-Chief of Construction World and President of FIRST Construction Council.
Related Stories
Gold Stories

Schindler named among Forbes’ World’s Best Employers 2026
Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
India needs an export-execution mindset: Vishesh Jain
Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Nuvoco reports 13.5% revenue growth in Q2 FY27
Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..
Related Articles
Latest Updates