Logistics leasing crossed 13 mn sq ft in H1 2019; records 31per cent growth YoY
WAREHOUSING & LOGISTICS

Logistics leasing crossed 13 mn sq ft in H1 2019; records 31per cent growth YoY

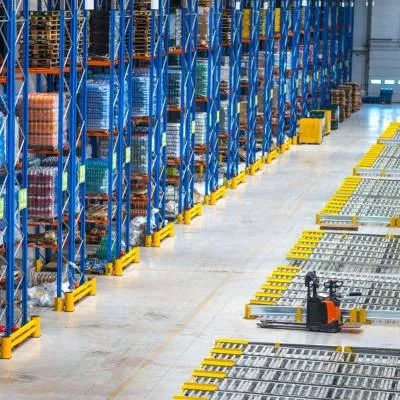
Photo: For representational purpose

  • Mumbai, Chennai and Bengaluru accounted for close to 60 per cent of leasing.
  • 3PL sector contributed close to 56 per cent of total absorption during H1 2019 compared to 31 per cent in H2 2018.
  • About 11 million sq ft supply added in H1 2019; led by Mumbai, Chennai and Ahmedabad.
  • Investment of more than US$ 200 million recorded in the industrial and logistics sector.

Logistics leasing in the country has recorded a growth of 31 per cent on a yearly basis, crossing 13 million sq ft, as per a CBRE South Asia report titled ‘India Industrial and Logistics Market View, H1 2019’. Mumbai, Chennai and Bengaluru accounted for more than 60 per cent of the leasing activity.

Speaking on the report, Anshuman Magazine, Chairman & CEO-India, South East Asia, Middle East & Africa, CBRE, said, “While the overall pipeline for the sector is expected to be around 60 million sq ft till 2020, at least 22 million sq ft of this supply is anticipated to be released by leading players. We also expect logistics leasing activity to strengthen owing to consolidation/ expansion by occupiers. In addition, as per our APAC Investor Intention Survey, 2019, India was among the top five investment destinations in APAC. Industrial and logistics was also one of the top segments expected to be targeted by investors in 2019.”

Similar to H2 2018, logistics space take-up was dominated by small-sized transactions (less than 50,000 sq ft), accounting for about 38 per cent of the leasing activity in H1 2019. The share of medium-sized transactions (ranging between 50,000 sq ft and 100,000 sq ft) rose from 26 per cent in H2 2018 to 32 per cent in H1 2019. Large-sized deals (greater than 100,000 sq ft) accounted for 30 per cent of the leasing activity during H1 2019. 

Jasmine Singh, Executive Director, Advisory & Transaction Services, CBRE India, said, “It is quite interesting to note that the key demand drivers of leasing activity in H1 2019 were 3PL (56 per cent) and engineering and manufacturing (6 per cent) firms. Domestic corporates drove demand with a share of about 85 per cent of leasing as compared to about 67 per cent in H1 2018. We also witnessed new launches to the tune of about 15 million sq ft by major developers.

Supply addition rose by about 54 per cent in H1 2019 as compared to H2 2018, with about 11 million sq ft of projects completed. About 65 per cent of the completions were reported in Mumbai, Chennai and Ahmedabad. Moreover, the increasing interest of leading players in expanding their portfolios was visible during H1 2019. 

Sustained occupier interest in locating in quality developments resulted in rental growth of about 5-40 per cent in NH-1 and NH-8 in NCR; about 3-24 per cent in Eastern and Western Corridors in Bengaluru; about 12-18 per cent in Western and Southern Corridors in Hyderabad; about 5-7 per cent in Western Corridor-II and Northern Corridor in Chennai and about 3-6 per cent in Narol in Ahmedabad on a half-yearly basis.

The outlook

The logistics sector in India is experiencing unprecedented structural shifts in the form of automation, leading to blurring of lines with the retail sector, transformation of supply chains and growing investments. Recent policy reforms and infrastructure initiatives, when completed, are likely to create a favourable business environment and position India among the most attractive investment destinations for the logistics industry in the coming quarters.

As technology permeates the sector, demand for quality space is increasing and corporates across segments are opting for large, modern warehouses. Advances in technology, particularly automation, will continue to enhance the specifications and operations of logistics assets, thereby pushing older, inferior-grade properties down the demand pyramid. Further, we expect that the trend of e-commerce platforms owning and operating their own facilities will result in more built-to-suit facilities, thereby taking off some “pure” leasing from the market.

Cities such as NCR, Mumbai, Bengaluru are expected to dominate the supply pipeline, with the average size of warehouses in NCR and Mumbai likely to exceed 1 million sq ft. Other cities such as Chennai, Hyderabad and Pune are also expected to witness supply addition, but the average size of developments are expected to be in the 0.3-0.5 million sq ft category. In order to satiate the demand for quality spaces, domestic companies would continue to partner (JV, merger, etc) with foreign players to seize the growth opportunity that the sector is offering.

For H2 2019, CBRE expects supply-constrained locations to continue to deliver rental growth, with new logistics hubs also emerging across cities in response to labour availability and land shortage. Prime locations likely to witness rental growth in coming months include NH-8 in NCR; Bhiwandi in Mumbai; Western and Northern Corridors in Chennai; Northern Corridor in Hyderabad; and NH-2 and NH-6 in Kolkata.


Photo: For representational purposeMumbai, Chennai and Bengaluru accounted for close to 60 per cent of leasing.3PL sector contributed close to 56 per cent of total absorption during H1 2019 compared to 31 per cent in H2 2018.About 11 million sq ft supply added in H1 2019; led by Mumbai, Chennai and Ahmedabad.Investment of more than US$ 200 million recorded in the industrial and logistics sector.Logistics leasing in the country has recorded a growth of 31 per cent on a yearly basis, crossing 13 million sq ft, as per a CBRE South Asia report titled ‘India Industrial and Logistics Market View, H1 2019’. Mumbai, Chennai and Bengaluru accounted for more than 60 per cent of the leasing activity.Speaking on the report, Anshuman Magazine, Chairman & CEO-India, South East Asia, Middle East & Africa, CBRE, said, “While the overall pipeline for the sector is expected to be around 60 million sq ft till 2020, at least 22 million sq ft of this supply is anticipated to be released by leading players. We also expect logistics leasing activity to strengthen owing to consolidation/ expansion by occupiers. In addition, as per our APAC Investor Intention Survey, 2019, India was among the top five investment destinations in APAC. Industrial and logistics was also one of the top segments expected to be targeted by investors in 2019.”Similar to H2 2018, logistics space take-up was dominated by small-sized transactions (less than 50,000 sq ft), accounting for about 38 per cent of the leasing activity in H1 2019. The share of medium-sized transactions (ranging between 50,000 sq ft and 100,000 sq ft) rose from 26 per cent in H2 2018 to 32 per cent in H1 2019. Large-sized deals (greater than 100,000 sq ft) accounted for 30 per cent of the leasing activity during H1 2019. Jasmine Singh, Executive Director, Advisory & Transaction Services, CBRE India, said, “It is quite interesting to note that the key demand drivers of leasing activity in H1 2019 were 3PL (56 per cent) and engineering and manufacturing (6 per cent) firms. Domestic corporates drove demand with a share of about 85 per cent of leasing as compared to about 67 per cent in H1 2018. We also witnessed new launches to the tune of about 15 million sq ft by major developers.Supply addition rose by about 54 per cent in H1 2019 as compared to H2 2018, with about 11 million sq ft of projects completed. About 65 per cent of the completions were reported in Mumbai, Chennai and Ahmedabad. Moreover, the increasing interest of leading players in expanding their portfolios was visible during H1 2019. Sustained occupier interest in locating in quality developments resulted in rental growth of about 5-40 per cent in NH-1 and NH-8 in NCR; about 3-24 per cent in Eastern and Western Corridors in Bengaluru; about 12-18 per cent in Western and Southern Corridors in Hyderabad; about 5-7 per cent in Western Corridor-II and Northern Corridor in Chennai and about 3-6 per cent in Narol in Ahmedabad on a half-yearly basis.The outlookThe logistics sector in India is experiencing unprecedented structural shifts in the form of automation, leading to blurring of lines with the retail sector, transformation of supply chains and growing investments. Recent policy reforms and infrastructure initiatives, when completed, are likely to create a favourable business environment and position India among the most attractive investment destinations for the logistics industry in the coming quarters.As technology permeates the sector, demand for quality space is increasing and corporates across segments are opting for large, modern warehouses. Advances in technology, particularly automation, will continue to enhance the specifications and operations of logistics assets, thereby pushing older, inferior-grade properties down the demand pyramid. Further, we expect that the trend of e-commerce platforms owning and operating their own facilities will result in more built-to-suit facilities, thereby taking off some “pure” leasing from the market.Cities such as NCR, Mumbai, Bengaluru are expected to dominate the supply pipeline, with the average size of warehouses in NCR and Mumbai likely to exceed 1 million sq ft. Other cities such as Chennai, Hyderabad and Pune are also expected to witness supply addition, but the average size of developments are expected to be in the 0.3-0.5 million sq ft category. In order to satiate the demand for quality spaces, domestic companies would continue to partner (JV, merger, etc) with foreign players to seize the growth opportunity that the sector is offering.For H2 2019, CBRE expects supply-constrained locations to continue to deliver rental growth, with new logistics hubs also emerging across cities in response to labour availability and land shortage. Prime locations likely to witness rental growth in coming months include NH-8 in NCR; Bhiwandi in Mumbai; Western and Northern Corridors in Chennai; Northern Corridor in Hyderabad; and NH-2 and NH-6 in Kolkata.

Related Stories

Gold Stories

Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..

Next Story
Infrastructure Urban

India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..

Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code