- Home
- Infrastructure Energy
- OIL & GAS
- Pandemic grips credit quality, weakens credit ratio
Pandemic grips credit quality, weakens credit ratio
Amid intensifying credit pressures, timely measures by the Reserve Bank of India (RBI) to permit banks to offer moratorium on servicing of bank loans until May 2020 comes as a big breather in the immediate term. However, over the near to medium term, credit quality trends would be driven by the ability of companies to rebound from the near-standstill demand situation.
Says Gurpreet Chhatwal, President, CRISIL Ratings, “We foresee India Inc’s credit quality deteriorating in the near-term. Our study of 35 sectors, both from manufacturing and services, however, shows sharp variation in resilience in a post-COVID-19 landscape. Strong balance sheets or continuing demand will support some sectors during the current lockdown. However, some other sectors could be hampered by collapsing discretionary demand or high leverage.”
These 35 sectors account for ~71 per cent of the debt (excluding financial sector) in CRISIL’s rated portfolio. Among the conclusions of the study are:
In the financial services segment, the lockdown restrictions will have a near-term impact on both collections and fresh loan disbursements.
While the RBI moratorium provides some relief on the assets side, it is on liabilities side that challenges could emerge for non-banking financial companies (NBFCs) with high share of capital market borrowings. That’s because no moratorium has been announced so far for capital market borrowings (such as bonds and commercial paper) and repayments on these will have to be made on time, during a period when collections would be impacted significantly.
Most NBFCs rated investment-grade by CRISIL have high levels of liquidity and/or enjoy strong parentage. CRISIL’s analysis of the top 100 rated NBFCs indicates that majority have liquidity buffer of over two times towards repayment of capital market borrowings due in the next two months.
In terms of resilience of the underlying asset classes, CRISIL’s analysis reveals that:
Says Somasekhar Vemuri, Senior Director, CRISIL Ratings, “Supportive measures from the Government of India and the RBI have eased cash flow pressures in various sectors for now. As the lockdown is lifted, credit profiles will be back to being driven by fundamentals – namely, pace of economic recovery, demand resilience in respective sectors, and normalisation of working capital cycles.”
However, the duration, spread and intensity of the pandemic will continue to materially impact the credit outlook for fiscal 2021, with rating downgrades likely to far outnumber upgrades.
Further fiscal and/or monetary support will be a monitorable for any upside to this expectation.
Click on this link for more on: Pandemic to weigh on India Inc’s credit quality.
- COVID-19
- Coronavirus
- pandemic
- global recession
- outlook
- India Inc
- gross domestic product
- GDP
- growth forecast
- slowing economy
- credit ratio
- credit pressures
- Reserve Bank of India
- RBI
- Gurpreet Chhatwal
- CRISIL Ratings
- balance sheets
- pharmaceuticals
- fertiliser
- oil refineries
- power and gas
- distribution and transmission
- power generators
- roads
- construction
- lockdown
- airlines
- real estate
- weak balance sheets
- financial services
- loan disbursements
- NBFCs
- capital market
- capital market borrowings
- affordable home loans
- Somasekhar Vemuri
- cash flow pressures
- working capital
Intensifying COVID-19 or the Coronavirus pandemic and a looming global recession have cast an unprecedented cloud over the credit quality outlook of India Inc, which has already been impacted by a slowing economy. This has forced CRISIL to slash its base-case gross domestic product (GDP) growth forecast for fiscal 2021 to 3.5 per cent. The impact of a slowing economy has already started reflecting in rating actions with downgrades (469) outnumbering upgrades (360) in the second half of fiscal 2020, and CRISIL’s credit ratio sliding to 0.77 time compared with 1.21 times in the first half. Amid intensifying credit pressures, timely measures by the Reserve Bank of India (RBI) to permit banks to offer moratorium on servicing of bank loans until May 2020 comes as a big breather in the immediate term. However, over the near to medium term, credit quality trends would be driven by the ability of companies to rebound from the near-standstill demand situation. Says Gurpreet Chhatwal, President, CRISIL Ratings, “We foresee India Inc’s credit quality deteriorating in the near-term. Our study of 35 sectors, both from manufacturing and services, however, shows sharp variation in resilience in a post-COVID-19 landscape. Strong balance sheets or continuing demand will support some sectors during the current lockdown. However, some other sectors could be hampered by collapsing discretionary demand or high leverage.” These 35 sectors account for ~71 per cent of the debt (excluding financial sector) in CRISIL’s rated portfolio. Among the conclusions of the study are: Nearly 44 per cent of debt is in sectors which are expected to be in high resilience category. Among these pharmaceuticals, fertiliser, oil refineries, power and gas distribution and transmission benefit from the essential nature of products and in some cases, even from government support. Telecom and fast moving consumer goods will see the least impact on demand – indeed, some of their sub-segments may actually benefit from demand uptick during the COVID-19 disruption. Nearly 52 per cent of debt is in sectors expected to be in moderately resilience category, such as automobile manufacturers, power generators, roads and construction. While these sectors have moderate-to-high disruption due to the lockdown, key mitigating factors, which partially cushion the impact, include the presence of strong balance sheets or liquidity, or relatively faster demand recovery. Around 4 per cent of debt is in sectors that are least resilient, such as airlines, gems and jewellery, auto dealers and real estate, given the discretionary nature of goods and services, and weak balance sheets. In the financial services segment, the lockdown restrictions will have a near-term impact on both collections and fresh loan disbursements. While the RBI moratorium provides some relief on the assets side, it is on liabilities side that challenges could emerge for non-banking financial companies (NBFCs) with high share of capital market borrowings. That’s because no moratorium has been announced so far for capital market borrowings (such as bonds and commercial paper) and repayments on these will have to be made on time, during a period when collections would be impacted significantly. Most NBFCs rated investment-grade by CRISIL have high levels of liquidity and/or enjoy strong parentage. CRISIL’s analysis of the top 100 rated NBFCs indicates that majority have liquidity buffer of over two times towards repayment of capital market borrowings due in the next two months. In terms of resilience of the underlying asset classes, CRISIL’s analysis reveals that: Gold loans will see faster asset-backed recovery despite weaker income profile of borrowers, while the home loans segment will be less affected as majority of borrowers are salaried.Vehicle loans and affordable home loans segments are expected to see moderate recovery as economic activity resumes. Unsecured microfinance, and loans to small and medium enterprises (including the loan against property segment) will continue be impacted to a relatively greater extent over the next 9-12 months because of the weak credit profile of borrowers and expectations of only a gradual recovery in the economy. Says Somasekhar Vemuri, Senior Director, CRISIL Ratings, “Supportive measures from the Government of India and the RBI have eased cash flow pressures in various sectors for now. As the lockdown is lifted, credit profiles will be back to being driven by fundamentals – namely, pace of economic recovery, demand resilience in respective sectors, and normalisation of working capital cycles.” However, the duration, spread and intensity of the pandemic will continue to materially impact the credit outlook for fiscal 2021, with rating downgrades likely to far outnumber upgrades. Further fiscal and/or monetary support will be a monitorable for any upside to this expectation.Click on this link for more on: Pandemic to weigh on India Inc’s credit quality.
Related Stories
Gold Stories
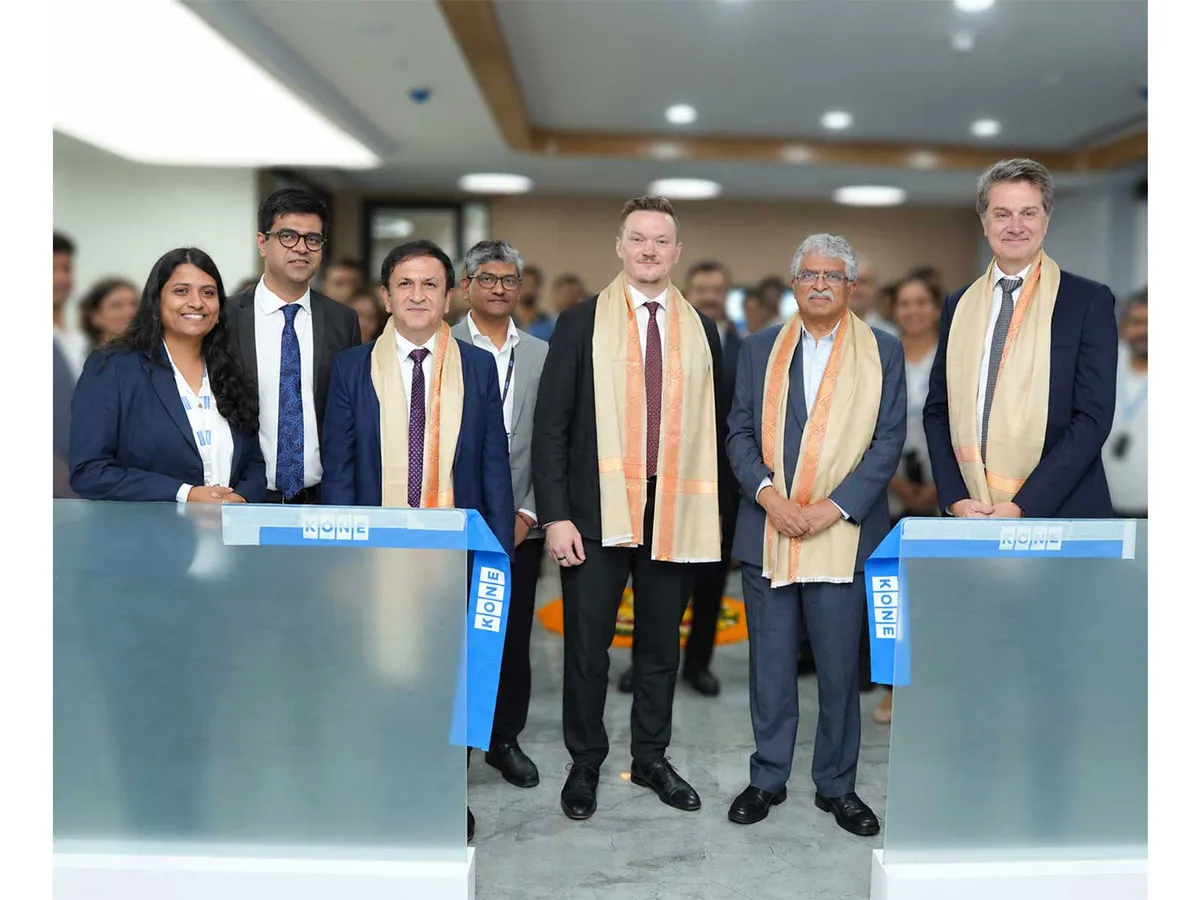
KONE Opens India's First Digital Experience Centre in Pune
KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
CII GreenCo Launches Circularity Guidelines for Indian Industry
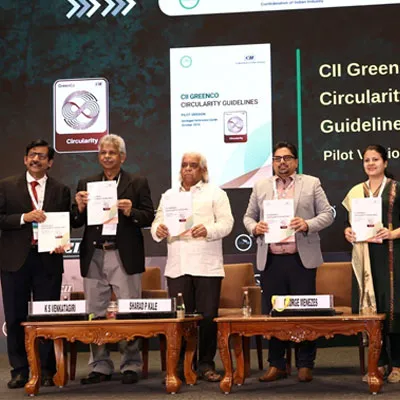
The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Global Electronics Association Launches IPC-1783-CO2E Standard
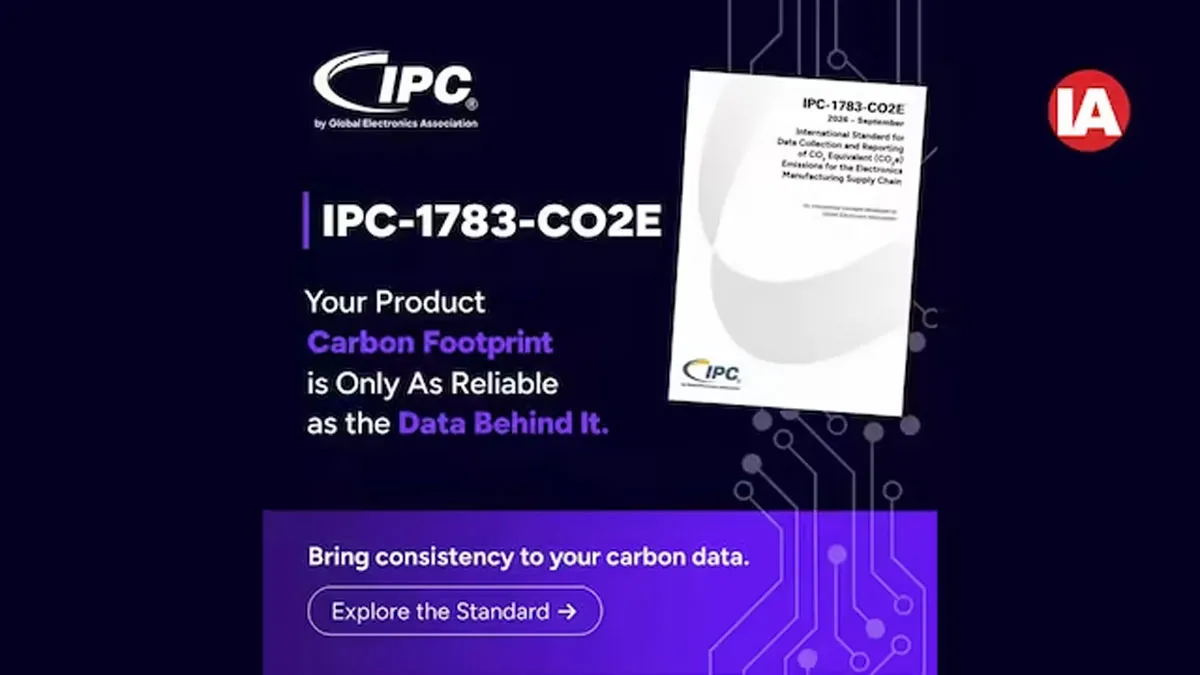
The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..
Related Articles
Latest Updates
Recommended for you
Advertisement
Subscribe to Our Newsletter
Get daily newsletters around different themes from Construction world.
subscribe to the newsletter
Don't miss out on valuable insights and opportunities
to connect with like minded professionals