Malls would have a larger catchment area in these Tier-II and Tier-III cities. Here's more!
Real Estate

Malls would have a larger catchment area in these Tier-II and Tier-III cities. Here's more!

Expansion of brick-n-mortar retail is also underway outside metros. Between 2006 and 2017, Tier-II cities reportedly received close to five times the investment of Tier-I cities, which <span style="font-weight: bold;">Anuj Kejriwal, Managing Director &amp; CEO, Anarock Retail</span> ascribes to 'investors and mall developers realising the potential of these smaller markets and trying to make their presence felt.' <p></p> <p>According to <span style="font-weight: bold;">Pratik Mantri, Director, Mantri Developers,</span> developers have been quick to spot the potential in Tier-II cities&nbsp;<span style="font-size: 13.3333px;">'</span>to gain first-mover advantage, as once a mall establishes loyalty through convenience it becomes hard to disrupt.'</p> <p>Demand-supply economics is at play in this growth. On the one hand, there is a 'dearth of quality malls, more so in Tier-II and Tier-III cities', to quote <span style="font-weight: bold;">Jayen Naik, Vice President-Malls, Nexus Malls.</span> On the other hand, the demand for retail space has spilled over to Tier-II and Tier-III cities, driven by 'an increasing consumer base with increasing spending potential', according to <span style="font-weight: bold;">Bimal Sharma, Head, Retail Services, CBRE.</span> </p> <p>To a certain extent, e-commerce has furthered the growth of malls especially in Tier-II and Tier-III cities, Naik believes, 'by generating interest in brands and pushing first-time trials by aspirational customers, which inevitably spurs the desire for an experience that only the brick-n-mortar format can deliver'.</p> <p>From the perspective of brands, the key drivers of retail space in Tier-II and Tier-III cities are the fact that 'these cities are hitherto uncharted locations and have relatively lower real-estate costs (compared to metros)', says Sharma. </p> <p>Tier-I cities are facing low vacancy levels, space saturation, crippled infrastructure and high rentals, adds Kejriwal, calling Tier-II and Tier-III the country's future growth engines with the potential for the market size to grow more than 10 times. He sees big prospects for retail expansion in Tier-II cities such as Lucknow, Coimbatore, Chandigarh, Mangaluru and Ahmedabad.</p> <p><span style="font-weight: bold;">Anshul Pahuja, Vice President, Business Development, Pacific Development Corporation,</span> cites Lucknow, Kanpur, Dehradun, Mathura, Agra, Jaipur, Chandigarh and cities in Punjab as some of the Tier-II cities with great potential. Sharma counts Jaipur, Chandigarh, Kochi, Bhubaneshwar and Nagpur as the retail sector's next happening destinations.</p> <p>But the bright prospects may well extend beyond these cities. 'In the next decade, we expect to see malls of about 4-5 lakh sq ft develop in every city with a population of about 500,000,' says Naik, relying on the 1:1 ideal ratio between the size of a mall and the size of the population in the catchment area to estimate the size.</p> <p>But if these malls would have a larger catchment area, larger even than malls in metros, they could be bigger. For instance, a mall in Mohali could attract visitors from the Chandigarh capital region as well as nearby cities in Punjab, Haryana and Himachal Pradesh, explains <span style="font-weight: bold;">Aashish Agarwal, Senior Director (Head-Consulting), Colliers International India, </span>provided it is developed as a destination.</p> <p></p>

Expansion of brick-n-mortar retail is also underway outside metros. Between 2006 and 2017, Tier-II cities reportedly received close to five times the investment of Tier-I cities, which <span style="font-weight: bold;">Anuj Kejriwal, Managing Director &amp; CEO, Anarock Retail</span> ascribes to 'investors and mall developers realising the potential of these smaller markets and trying to make their presence felt.' <p></p> <p>According to <span style="font-weight: bold;">Pratik Mantri, Director, Mantri Developers,</span> developers have been quick to spot the potential in Tier-II cities&nbsp;<span style="font-size: 13.3333px;">'</span>to gain first-mover advantage, as once a mall establishes loyalty through convenience it becomes hard to disrupt.'</p> <p>Demand-supply economics is at play in this growth. On the one hand, there is a 'dearth of quality malls, more so in Tier-II and Tier-III cities', to quote <span style="font-weight: bold;">Jayen Naik, Vice President-Malls, Nexus Malls.</span> On the other hand, the demand for retail space has spilled over to Tier-II and Tier-III cities, driven by 'an increasing consumer base with increasing spending potential', according to <span style="font-weight: bold;">Bimal Sharma, Head, Retail Services, CBRE.</span> </p> <p>To a certain extent, e-commerce has furthered the growth of malls especially in Tier-II and Tier-III cities, Naik believes, 'by generating interest in brands and pushing first-time trials by aspirational customers, which inevitably spurs the desire for an experience that only the brick-n-mortar format can deliver'.</p> <p>From the perspective of brands, the key drivers of retail space in Tier-II and Tier-III cities are the fact that 'these cities are hitherto uncharted locations and have relatively lower real-estate costs (compared to metros)', says Sharma. </p> <p>Tier-I cities are facing low vacancy levels, space saturation, crippled infrastructure and high rentals, adds Kejriwal, calling Tier-II and Tier-III the country's future growth engines with the potential for the market size to grow more than 10 times. He sees big prospects for retail expansion in Tier-II cities such as Lucknow, Coimbatore, Chandigarh, Mangaluru and Ahmedabad.</p> <p><span style="font-weight: bold;">Anshul Pahuja, Vice President, Business Development, Pacific Development Corporation,</span> cites Lucknow, Kanpur, Dehradun, Mathura, Agra, Jaipur, Chandigarh and cities in Punjab as some of the Tier-II cities with great potential. Sharma counts Jaipur, Chandigarh, Kochi, Bhubaneshwar and Nagpur as the retail sector's next happening destinations.</p> <p>But the bright prospects may well extend beyond these cities. 'In the next decade, we expect to see malls of about 4-5 lakh sq ft develop in every city with a population of about 500,000,' says Naik, relying on the 1:1 ideal ratio between the size of a mall and the size of the population in the catchment area to estimate the size.</p> <p>But if these malls would have a larger catchment area, larger even than malls in metros, they could be bigger. For instance, a mall in Mohali could attract visitors from the Chandigarh capital region as well as nearby cities in Punjab, Haryana and Himachal Pradesh, explains <span style="font-weight: bold;">Aashish Agarwal, Senior Director (Head-Consulting), Colliers International India, </span>provided it is developed as a destination.</p> <p></p>

Related Stories

Gold Stories

Next Story
Infrastructure Urban

KONE Opens India's First Digital Experience Centre in Pune

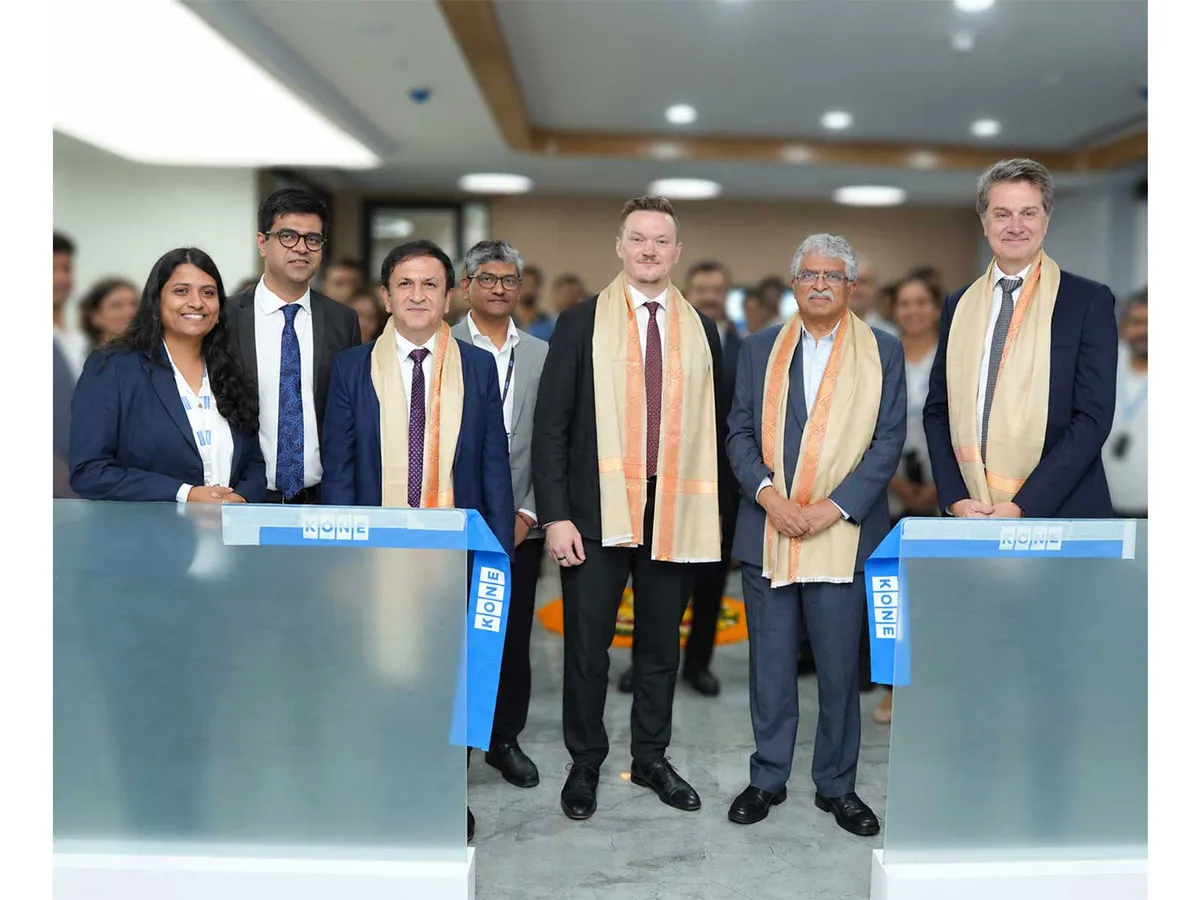
KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

CII GreenCo Launches Circularity Guidelines for Indian Industry

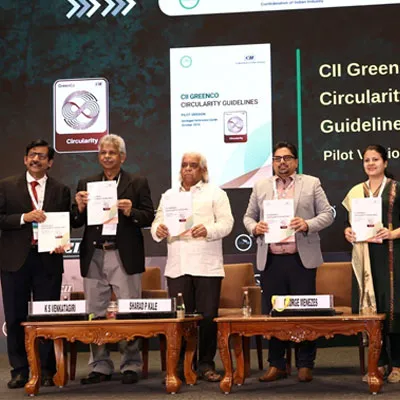
The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

Global Electronics Association Launches IPC-1783-CO2E Standard

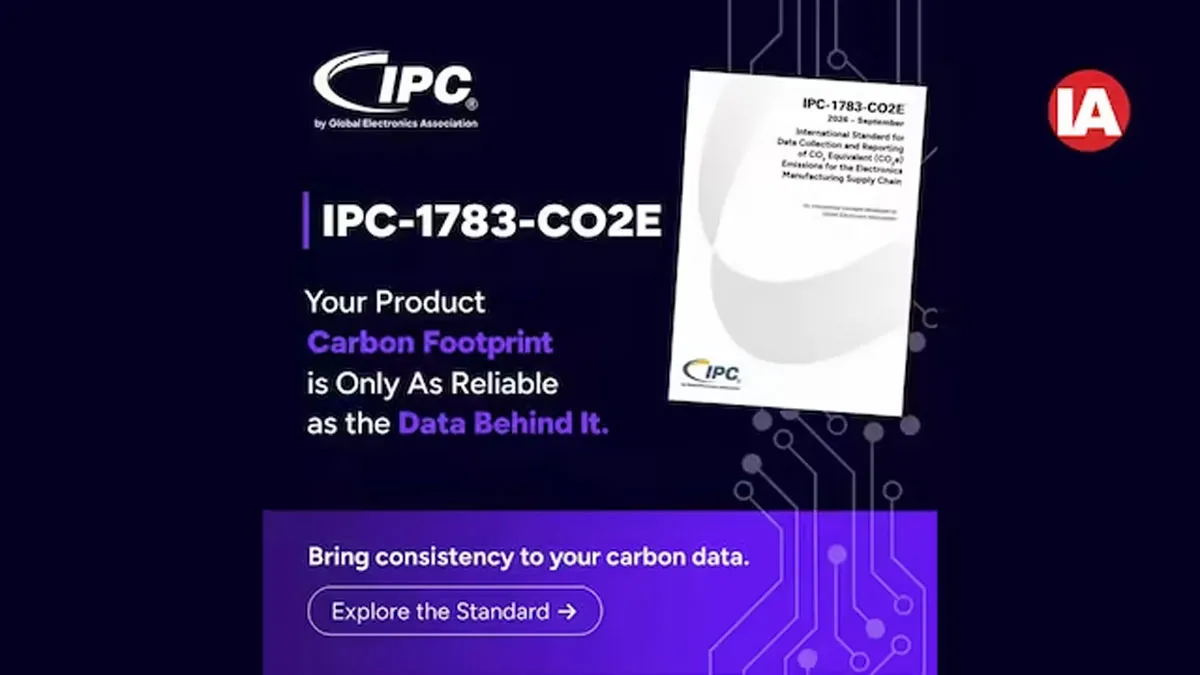
The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code