1% TDS applies on immovable property over Rs 50 lakh
Real Estate

1% TDS applies on immovable property over Rs 50 lakh

1% of Tax Deduction at Source (TDS) will be applied on non-agriculture immovable properties over Rs 50 lakh based on the sale price or the stamp duty after an amendment in the Income Tax Act.

Currently, the TDS is deducted based on the consideration value of the immovable properties. There is no consistency in the Income Tax Act regarding the levy of the TDS.

Nirmala Sitharaman, Minister of Finance, has proposed the amendment to do in the anomaly in the law.

According to the Finance Bill 2022 and the Budget, the government proposes to amend Section 194-IA of the Income Tax Act to remove inconsistency with Section 43CA and 50CA of the law.

According to the Finance Bill, Section 194-IA of the Act provides a tax deduction on the payment on transfer of some immovable properties apart from agricultural land.

Sub-section I provide for deduction of tax by any person responsible for paying a resident any amount of consideration for transfer of any immovable property during the time of credit or payment of the amount to the resident at 1% of amount as the income tax.

Sub-section 2 provided no deduction of tax where the consideration of the transfer of any immovable property is under Rs 50 lakh.

According to the document, TDS has to be deducted from the amount of consideration paid by the transferee to the transferor. The section does not count the stamp duty value of the immovable property, while Sections 43CA and 50C of the Act, for the computation of income under profit and gains from business and capital gains, respectively, the stamp duty value is also to be considered.

The Ministry highlighted the inconsistency in the provisions of Section 194-IA and Section 43CA and 50C of the Act.

As per the document, for removing inconsistency in regulations, it is proposed to amend Section 194-IA of the Act in case of transfer of immovable property, TDS of 1% will be deducted from the amount paid or credited to the resident or the stamp duty value of the property.

In case of consideration paid for the transfer of immovable property and the stamp duty value of the property is under Rs 50 lakh, then no tax will be deducted under Section 194-IA of the Act.

Image Source

Also read: Government to modify TDS norms on immovable property sale

1% of Tax Deduction at Source (TDS) will be applied on non-agriculture immovable properties over Rs 50 lakh based on the sale price or the stamp duty after an amendment in the Income Tax Act. Currently, the TDS is deducted based on the consideration value of the immovable properties. There is no consistency in the Income Tax Act regarding the levy of the TDS. Nirmala Sitharaman, Minister of Finance, has proposed the amendment to do in the anomaly in the law. According to the Finance Bill 2022 and the Budget, the government proposes to amend Section 194-IA of the Income Tax Act to remove inconsistency with Section 43CA and 50CA of the law. According to the Finance Bill, Section 194-IA of the Act provides a tax deduction on the payment on transfer of some immovable properties apart from agricultural land. Sub-section I provide for deduction of tax by any person responsible for paying a resident any amount of consideration for transfer of any immovable property during the time of credit or payment of the amount to the resident at 1% of amount as the income tax. Sub-section 2 provided no deduction of tax where the consideration of the transfer of any immovable property is under Rs 50 lakh. According to the document, TDS has to be deducted from the amount of consideration paid by the transferee to the transferor. The section does not count the stamp duty value of the immovable property, while Sections 43CA and 50C of the Act, for the computation of income under profit and gains from business and capital gains, respectively, the stamp duty value is also to be considered. The Ministry highlighted the inconsistency in the provisions of Section 194-IA and Section 43CA and 50C of the Act. As per the document, for removing inconsistency in regulations, it is proposed to amend Section 194-IA of the Act in case of transfer of immovable property, TDS of 1% will be deducted from the amount paid or credited to the resident or the stamp duty value of the property. In case of consideration paid for the transfer of immovable property and the stamp duty value of the property is under Rs 50 lakh, then no tax will be deducted under Section 194-IA of the Act. Image Source Also read: Government to modify TDS norms on immovable property sale

Related Stories

Gold Stories
Next Story
Real Estate

Adani begins construction of Dharavi rehabilitation homes

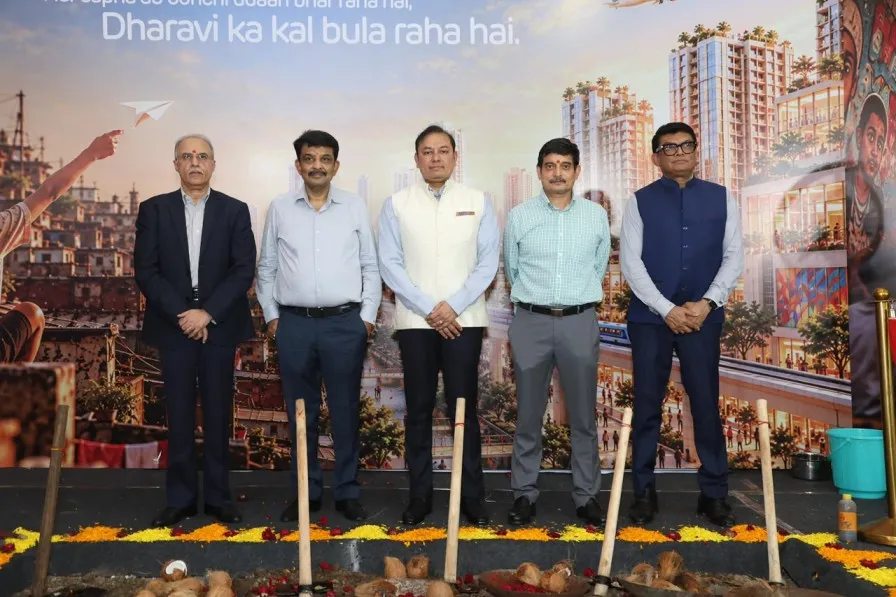
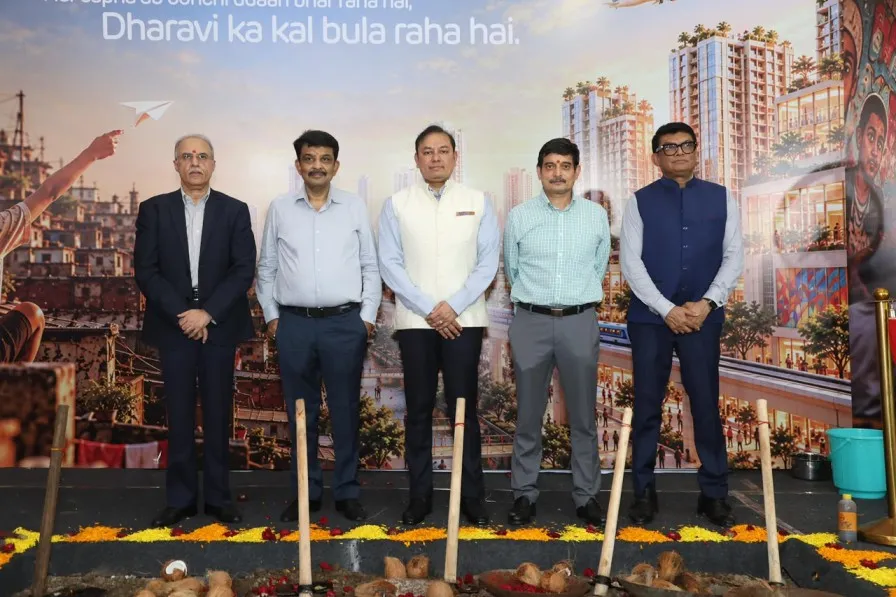
Construction of rehabilitation homes for eligible Dharavi residents has commenced at the 22-acre Matunga railway site, following a Bhoomi Poojan ceremony performed by Pranav Adani, Director, Adani Enterprises (AEL). The project, being implemented by Adani Navbharat Developers (ANDPL), envisages 10 towers comprising 10,432 rehabilitation apartments and 1,379 commercial and industrial units.Under the in-situ rehabilitation scheme, eligible residents will receive homes measuring 350 sq ft. Residents from Sectors 6 and 1 will be accommodated at Matunga first, followed by nearly 4,500 apartments fo..
Next Story
Real Estate

Adani begins construction of Dharavi rehabilitation homes

Construction of rehabilitation homes for eligible Dharavi residents has commenced at the 22-acre Matunga railway site, following a Bhoomi Poojan ceremony performed by Pranav Adani, Director, Adani Enterprises (AEL). The project, being implemented by Adani Navbharat Developers (ANDPL), envisages 10 towers comprising 10,432 rehabilitation apartments and 1,379 commercial and industrial units.Under the in-situ rehabilitation scheme, eligible residents will receive homes measuring 350 sq ft. Residents from Sectors 6 and 1 will be accommodated at Matunga first, followed by nearly 4,500 apartments fo..
Next Story
Equipment

Seven Propel 470 HEV electric tippers go to work on coal haulage in Chhattisgarh

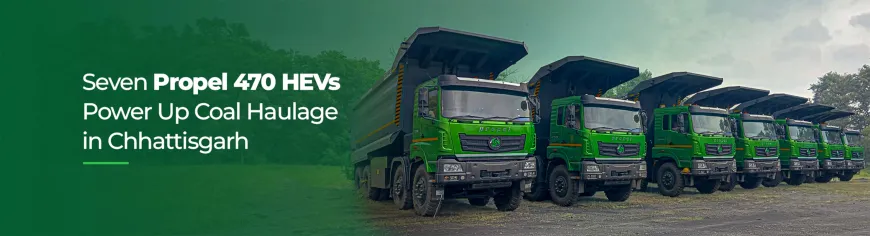
Propel EV, the electric mobility division of Propel Industries and India's No. 1 electric tipper brand, has deployed seven 470 HEV electric trucks with a leading coal-haulage contractor at one of India's largest opencast coal mines in Chhattisgarh. The trucks are in daily operation, moving coal on continuous haul cycles in one of the most demanding applications in Indian mining.Why Electric - and Why CoalCoal haulage runs round the clock: heavy loads, long haul cycles, steep ramps and abrasive dust. It is also where diesel hurts most. Engines run continuously, fuel is the largest single operat..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code