+
India’s Office Market Poised for Record 90+ Mn Sq Ft Leasing in 2025
Real Estate

India’s Office Market Poised for Record 90+ Mn Sq Ft Leasing in 2025

India’s office real estate sector is on track to achieve a historic milestone, with gross leasing volume (GLV) expected to cross 90 million square feet in 2025, according to Cushman & Wakefield’s Q2 India Office Market Report. In H1 2025, GLV stood at approximately 42 million sq ft, setting a strong pace for the year. 

Q2 2025 reported 21.4 million sq ft of leasing across the top eight cities, up 5 per cent quarter-on-quarter and flat year-on-year. This follows the sector’s record-breaking performance of ~89 million sq ft in 2024. If the trend continues, 2025 will be the second straight year to exceed 85 million sq ft, reinforcing a new market baseline. 

Demand continues to be driven by Global Capability Centres (GCCs), IT-BPM, flex space operators, BFSI, and engineering & manufacturing firms. GLV captures fresh leases, open market renewals, and pre-leases, offering a comprehensive measure of market activity. 

In Q2, Bengaluru (5.0 mn sq ft), Delhi NCR (4.6 mn sq ft), and Mumbai (3.9 mn sq ft) contributed 63 per cent of the total leasing volume. Other city contributions included Pune (3.3 mn sq ft), Chennai (2.2 mn sq ft), Hyderabad (1.7 mn sq ft), Kolkata (0.5 mn sq ft), and Ahmedabad (0.2 mn sq ft). 

Net absorption in Q2 2025 stood at 13.5 million sq ft, a 19 per cent increase over the same quarter last year, with H1 2025 net absorption totalling 27.8 million sq ft. Delhi NCR (5.2 mn sq ft), Pune (4.3 mn sq ft), and Chennai (3.1 mn sq ft) achieved record-high half-yearly absorption levels. 

Fresh leases accounted for 77 per cent of leasing in H1, continuing a trend seen since 2022. Pre-commitments rose to 10 per cent, indicating tight supply and urgent occupier demand. 

GCCs led leasing demand, accounting for 24 per cent of total activity in Q2, with Bengaluru and Pune together representing 63 per cent of this segment. H1 2025 saw the highest ever GCC leasing at 11.4 mn sq ft, up 3 per cent year-on-year. IT-BPM accounted for 40 per cent of this, followed by E&M GCCs at 36 per cent. 

Sector-wise, IT-BPM remained the largest occupier with a 34 per cent share in Q2, amounting to over 7 million sq ft—its second-highest post-pandemic quarterly volume. Flex workspace operators followed with 18 per cent, up 50 per cent quarter-on-quarter. For H1, IT-BPM contributed 32 per cent of leasing, followed by BFSI and flex segments at 16 per cent each, and E&M at 13 per cent. 

Q2 2025 saw 12.5 million sq ft of new supply, up 53 per cent year-on-year and 17 per cent quarter-on-quarter. For H1, supply touched 23.2 mn sq ft, with over 60 per cent concentrated in Bengaluru and Pune. Pune led with 4.8 mn sq ft in Q2 and 8.0 mn sq ft in H1, its highest on record. 

Net absorption outpaced new supply, resulting in a 230 bps drop in vacancy during H1. Tight vacancy in Bengaluru, Pune, Mumbai and Chennai is driving rental increases. Hyderabad and Mumbai posted the strongest rent growth at 15–16 per cent year-on-year. 

Anshul Jain, Chief Executive, India, SEA & APAC Tenant Representation, Cushman & Wakefield, said: 
 “India’s office market continues to outperform global peers, underpinned by a solid economic outlook and long-term occupier confidence. Our forecast of more than 90 million square feet of gross leasing this year reflects the sector’s structural strength—particularly as we see sustained growth in sectors like technology, BFSI, and engineering. 
 The GCC segment continues to be a key driver of demand, contributing a record 27 per cent of total leasing in H1. These centers are maturing in complexity and scale, and India’s deep talent pool and improving infrastructure continue to reinforce its positioning as a global hub. At the same time, we are seeing more diverse sources of demand from domestic corporates, financial institutions, and flex players. As we head into H2, we expect this momentum to continue—buoyed by easing inflation, expected rate cuts, and the continued evolution of India as a strategic business location.” 

Veera Babu, Executive Managing Director, Tenant Representation, Cushman & Wakefield, added: 
 “The market has seen strong momentum and is well on track to reach 90 million square feet this year—setting a new milestone for Indian real estate. With 42 million square feet already leased in H1, and a robust pipeline of active deals, it’s clear that demand remains broad-based and resilient. 
 The growth is being fuelled by a convergence of trends—expansion of existing occupiers, rapid scaling of GCCs, and entry of new domestic and global firms. But supply is lagging in core locations, creating a landlord’s market. Occupiers looking for high-quality space need to act early, especially as pre-commitments are on the rise and rentals are climbing in prime markets.” 


India’s office real estate sector is on track to achieve a historic milestone, with gross leasing volume (GLV) expected to cross 90 million square feet in 2025, according to Cushman & Wakefield’s Q2 India Office Market Report. In H1 2025, GLV stood at approximately 42 million sq ft, setting a strong pace for the year. Q2 2025 reported 21.4 million sq ft of leasing across the top eight cities, up 5 per cent quarter-on-quarter and flat year-on-year. This follows the sector’s record-breaking performance of ~89 million sq ft in 2024. If the trend continues, 2025 will be the second straight year to exceed 85 million sq ft, reinforcing a new market baseline. Demand continues to be driven by Global Capability Centres (GCCs), IT-BPM, flex space operators, BFSI, and engineering & manufacturing firms. GLV captures fresh leases, open market renewals, and pre-leases, offering a comprehensive measure of market activity. In Q2, Bengaluru (5.0 mn sq ft), Delhi NCR (4.6 mn sq ft), and Mumbai (3.9 mn sq ft) contributed 63 per cent of the total leasing volume. Other city contributions included Pune (3.3 mn sq ft), Chennai (2.2 mn sq ft), Hyderabad (1.7 mn sq ft), Kolkata (0.5 mn sq ft), and Ahmedabad (0.2 mn sq ft). Net absorption in Q2 2025 stood at 13.5 million sq ft, a 19 per cent increase over the same quarter last year, with H1 2025 net absorption totalling 27.8 million sq ft. Delhi NCR (5.2 mn sq ft), Pune (4.3 mn sq ft), and Chennai (3.1 mn sq ft) achieved record-high half-yearly absorption levels. Fresh leases accounted for 77 per cent of leasing in H1, continuing a trend seen since 2022. Pre-commitments rose to 10 per cent, indicating tight supply and urgent occupier demand. GCCs led leasing demand, accounting for 24 per cent of total activity in Q2, with Bengaluru and Pune together representing 63 per cent of this segment. H1 2025 saw the highest ever GCC leasing at 11.4 mn sq ft, up 3 per cent year-on-year. IT-BPM accounted for 40 per cent of this, followed by E&M GCCs at 36 per cent. Sector-wise, IT-BPM remained the largest occupier with a 34 per cent share in Q2, amounting to over 7 million sq ft—its second-highest post-pandemic quarterly volume. Flex workspace operators followed with 18 per cent, up 50 per cent quarter-on-quarter. For H1, IT-BPM contributed 32 per cent of leasing, followed by BFSI and flex segments at 16 per cent each, and E&M at 13 per cent. Q2 2025 saw 12.5 million sq ft of new supply, up 53 per cent year-on-year and 17 per cent quarter-on-quarter. For H1, supply touched 23.2 mn sq ft, with over 60 per cent concentrated in Bengaluru and Pune. Pune led with 4.8 mn sq ft in Q2 and 8.0 mn sq ft in H1, its highest on record. Net absorption outpaced new supply, resulting in a 230 bps drop in vacancy during H1. Tight vacancy in Bengaluru, Pune, Mumbai and Chennai is driving rental increases. Hyderabad and Mumbai posted the strongest rent growth at 15–16 per cent year-on-year. Anshul Jain, Chief Executive, India, SEA & APAC Tenant Representation, Cushman & Wakefield, said:  “India’s office market continues to outperform global peers, underpinned by a solid economic outlook and long-term occupier confidence. Our forecast of more than 90 million square feet of gross leasing this year reflects the sector’s structural strength—particularly as we see sustained growth in sectors like technology, BFSI, and engineering.  The GCC segment continues to be a key driver of demand, contributing a record 27 per cent of total leasing in H1. These centers are maturing in complexity and scale, and India’s deep talent pool and improving infrastructure continue to reinforce its positioning as a global hub. At the same time, we are seeing more diverse sources of demand from domestic corporates, financial institutions, and flex players. As we head into H2, we expect this momentum to continue—buoyed by easing inflation, expected rate cuts, and the continued evolution of India as a strategic business location.” Veera Babu, Executive Managing Director, Tenant Representation, Cushman & Wakefield, added:  “The market has seen strong momentum and is well on track to reach 90 million square feet this year—setting a new milestone for Indian real estate. With 42 million square feet already leased in H1, and a robust pipeline of active deals, it’s clear that demand remains broad-based and resilient.  The growth is being fuelled by a convergence of trends—expansion of existing occupiers, rapid scaling of GCCs, and entry of new domestic and global firms. But supply is lagging in core locations, creating a landlord’s market. Occupiers looking for high-quality space need to act early, especially as pre-commitments are on the rise and rentals are climbing in prime markets.” 

Related Stories

Gold Stories

Next Story
Infrastructure Urban

NABARD Holds Seminar on Vigilance, Integrity and Good Governance

National Bank for Agriculture and Rural Development (NABARD) organised a seminar on “Vigilance: Strengthening Integrity and Good Governance” on 25 August 2026 at its Head Office in Mumbai as part of the ongoing Vigilance Awareness Campaign 2026 being observed from 17 August to 16 November 2026, with the theme “Probity for Prosperity."" The seminar was graced by Suresh N Patel, Former Central Vigilance Commissioner, Government of India, as the chief guest and keynote speaker.  The programme was attended by G S Rawat, Deputy Managing Director, Dr Ajay K Sood, Deputy Managing Dire..
Next Story
Equipment

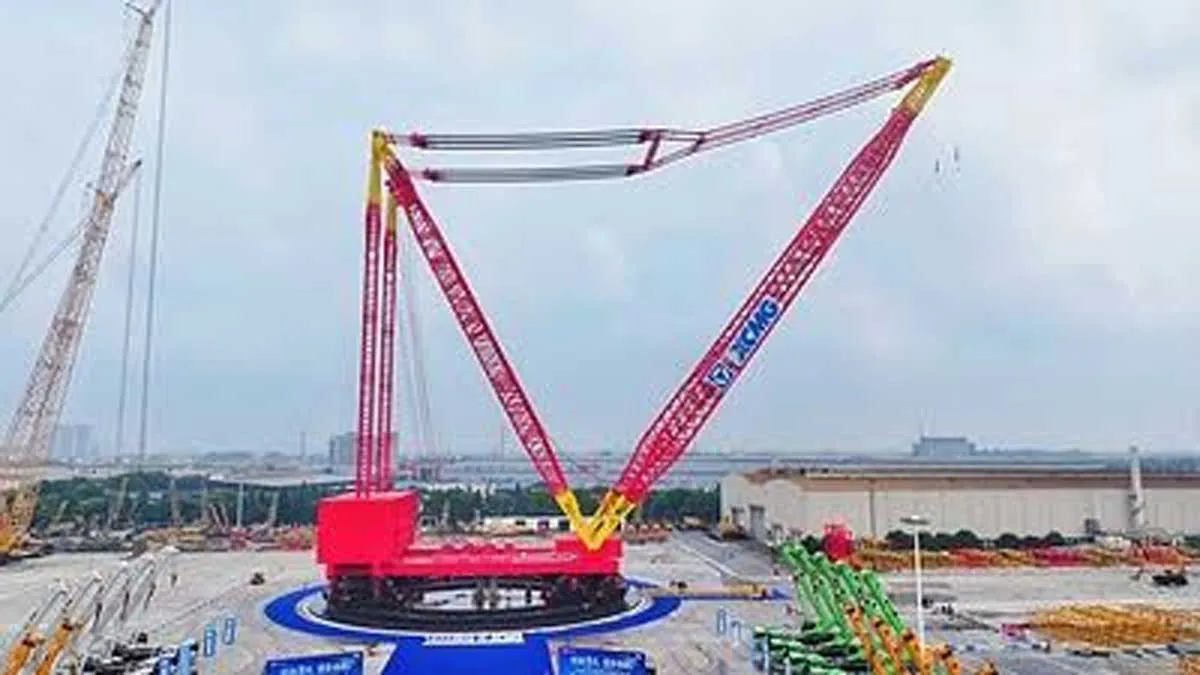
XCMG Unveils World's First 14,000-Ton Ring Crane for Heavy Lifting

XCMG has announced that the first main unit of the world's first 14,000-ton ring crane has rolled off the production line, marking a historic breakthrough in ultra-heavy lifting technology. Jointly developed by XCMG and Sinopec Heavy Lifting & Transportation Co., Ltd., the crane will be the largest-capacity ring crane ever built, setting a new benchmark for major construction projects worldwide.The crane features a modular configuration comprising two main units that work in tandem. The first main unit has completed final assembly and can independently perform lifting operations. Once both..
Next Story
Infrastructure Urban

Thriveni Logistics orders 200 tip trailers from Jagdamba trailers

Jagdamba Trailers (JTPL), one of India’s growing trailer manufacturers, has secured a significant order for 200 Tip Trailers from Thriveni Transport and Logistics Pvt. Ltd., a leading mining and logistics company serving operations across India and overseas.The order, placed for iron ore transportation, is a major milestone for JTPL, particularly as the company secured the business after competing with more than 10 established trailer manufacturers. It also strengthens an already successful relationship between the two companies. Approximately one and a half years ago, Thriveni Transport and..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code