ESAF Bank Reports Steady Growth With Strong Secured Lending
ECONOMY & POLICY

ESAF Bank Reports Steady Growth With Strong Secured Lending

ESAF Small Finance Bank, headquartered in Thrissur, has announced its financial results for the quarter ended 30 September 2025, reporting steady business expansion, strong growth in secured lending and continued improvement in asset quality.

The Bank’s total business reached Rs 420.31 billion, up 5.2 per cent year-on-year, driven by higher secured lending and strong retail deposit mobilisation. Gross advances rose 4.3 per cent to Rs 191.37 billion, while total deposits climbed 5.9 per cent to Rs 228.94 billion.

Secured loan disbursements surged 161 per cent to Rs 72.92 billion, with secured loans now forming 82 per cent of total disbursements. The gold loan book more than doubled to Rs 75 billion from Rs 37.41 billion a year earlier, emerging as a key growth driver alongside the Agri, MSME, Mobility and Mortgage portfolios. Meanwhile, micro loans now account for 39 per cent of total advances, down from 61 per cent, highlighting ESAF’s strategic shift towards a more secured and diversified lending mix.

The Bank narrowed its quarterly net loss to Rs 1.16 billion, compared with Rs 1.9 billion in Q2 FY25, supported by stronger operating performance and a more resilient portfolio.

CASA balances rose 13.7 per cent to Rs 60.46 billion, improving the CASA ratio to 26.4 per cent. Retail deposits now account for 96 per cent of total deposits, with retail term deposits rising from Rs 145.62 billion to Rs 160.33 billion, underscoring strong customer confidence.

ESAF’s Provision Coverage Ratio improved to 74.4 per cent, and net NPA remained stable at 3.8 per cent. Capital Adequacy stood healthy at 22.4 per cent, supported by Tier II issuances of Rs 1.15 billion in Q2 and Rs 1.5 billion in Q3.

The Bank added nearly 2 million new customers during the quarter, taking its total customer base to 9.78 million across 24 states and 2 union territories.

Managing Director and CEO Dr K. Paul Thomas said the solid growth in business and CASA deposits reflected deep and sustained customer trust. He added that strong traction in secured lending—particularly gold, mobility, mortgage and Agri loans—positions the Bank for quality-led expansion. ESAF, he said, remains focused on strengthening its balance sheet, enhancing asset quality and accelerating technology-led customer engagement.

Financial Highlights (Q2 FY26)

Business Growth

Total business rose 5.2 per cent YoY to Rs 420.31 billion.

Advances

Gross advances up 4.3 per cent YoY to Rs 191.37 billion.

Micro and gold loans each contributed 39 per cent of advances.

Disbursements more than doubled to Rs 89.13 billion (from Rs 40.58 billion).

Deposits

Total deposits up 5.9 per cent YoY to Rs 228.94 billion.

CASA deposits increased 14 per cent to Rs 60.46 billion.

CASA ratio improved to 26.4 per cent.

Profitability Metrics

Net Interest Income: Rs 3.64 billion.

Net Interest Margin: 5.9 per cent.

Pre-Provision Operating Profit: Rs 930 million.

Provisions: Rs 2.49 billion.

Net loss: Rs 1.16 billion.

Asset Quality

PCR: 74.4 per cent.

Net NPA: 3.8 per cent.

Network As of September 2025, the Bank operated 788 branches, 718 ATMs, 33 institutional business correspondents and 1,110 customer service centres across its nationwide network.

ESAF Small Finance Bank, headquartered in Thrissur, has announced its financial results for the quarter ended 30 September 2025, reporting steady business expansion, strong growth in secured lending and continued improvement in asset quality. The Bank’s total business reached Rs 420.31 billion, up 5.2 per cent year-on-year, driven by higher secured lending and strong retail deposit mobilisation. Gross advances rose 4.3 per cent to Rs 191.37 billion, while total deposits climbed 5.9 per cent to Rs 228.94 billion. Secured loan disbursements surged 161 per cent to Rs 72.92 billion, with secured loans now forming 82 per cent of total disbursements. The gold loan book more than doubled to Rs 75 billion from Rs 37.41 billion a year earlier, emerging as a key growth driver alongside the Agri, MSME, Mobility and Mortgage portfolios. Meanwhile, micro loans now account for 39 per cent of total advances, down from 61 per cent, highlighting ESAF’s strategic shift towards a more secured and diversified lending mix. The Bank narrowed its quarterly net loss to Rs 1.16 billion, compared with Rs 1.9 billion in Q2 FY25, supported by stronger operating performance and a more resilient portfolio. CASA balances rose 13.7 per cent to Rs 60.46 billion, improving the CASA ratio to 26.4 per cent. Retail deposits now account for 96 per cent of total deposits, with retail term deposits rising from Rs 145.62 billion to Rs 160.33 billion, underscoring strong customer confidence. ESAF’s Provision Coverage Ratio improved to 74.4 per cent, and net NPA remained stable at 3.8 per cent. Capital Adequacy stood healthy at 22.4 per cent, supported by Tier II issuances of Rs 1.15 billion in Q2 and Rs 1.5 billion in Q3. The Bank added nearly 2 million new customers during the quarter, taking its total customer base to 9.78 million across 24 states and 2 union territories. Managing Director and CEO Dr K. Paul Thomas said the solid growth in business and CASA deposits reflected deep and sustained customer trust. He added that strong traction in secured lending—particularly gold, mobility, mortgage and Agri loans—positions the Bank for quality-led expansion. ESAF, he said, remains focused on strengthening its balance sheet, enhancing asset quality and accelerating technology-led customer engagement. Financial Highlights (Q2 FY26) Business Growth Total business rose 5.2 per cent YoY to Rs 420.31 billion. Advances Gross advances up 4.3 per cent YoY to Rs 191.37 billion. Micro and gold loans each contributed 39 per cent of advances. Disbursements more than doubled to Rs 89.13 billion (from Rs 40.58 billion). Deposits Total deposits up 5.9 per cent YoY to Rs 228.94 billion. CASA deposits increased 14 per cent to Rs 60.46 billion. CASA ratio improved to 26.4 per cent. Profitability Metrics Net Interest Income: Rs 3.64 billion. Net Interest Margin: 5.9 per cent. Pre-Provision Operating Profit: Rs 930 million. Provisions: Rs 2.49 billion. Net loss: Rs 1.16 billion. Asset Quality PCR: 74.4 per cent. Net NPA: 3.8 per cent. Network As of September 2025, the Bank operated 788 branches, 718 ATMs, 33 institutional business correspondents and 1,110 customer service centres across its nationwide network.

Related Stories

Gold Stories

Next Story
Infrastructure Urban

KONE Opens India's First Digital Experience Centre in Pune

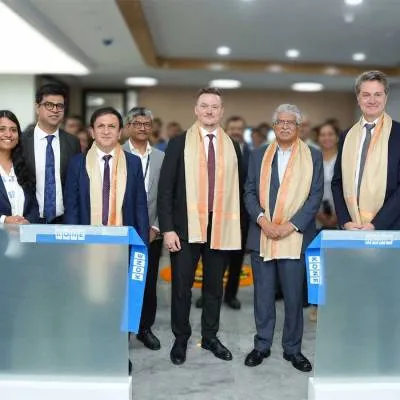
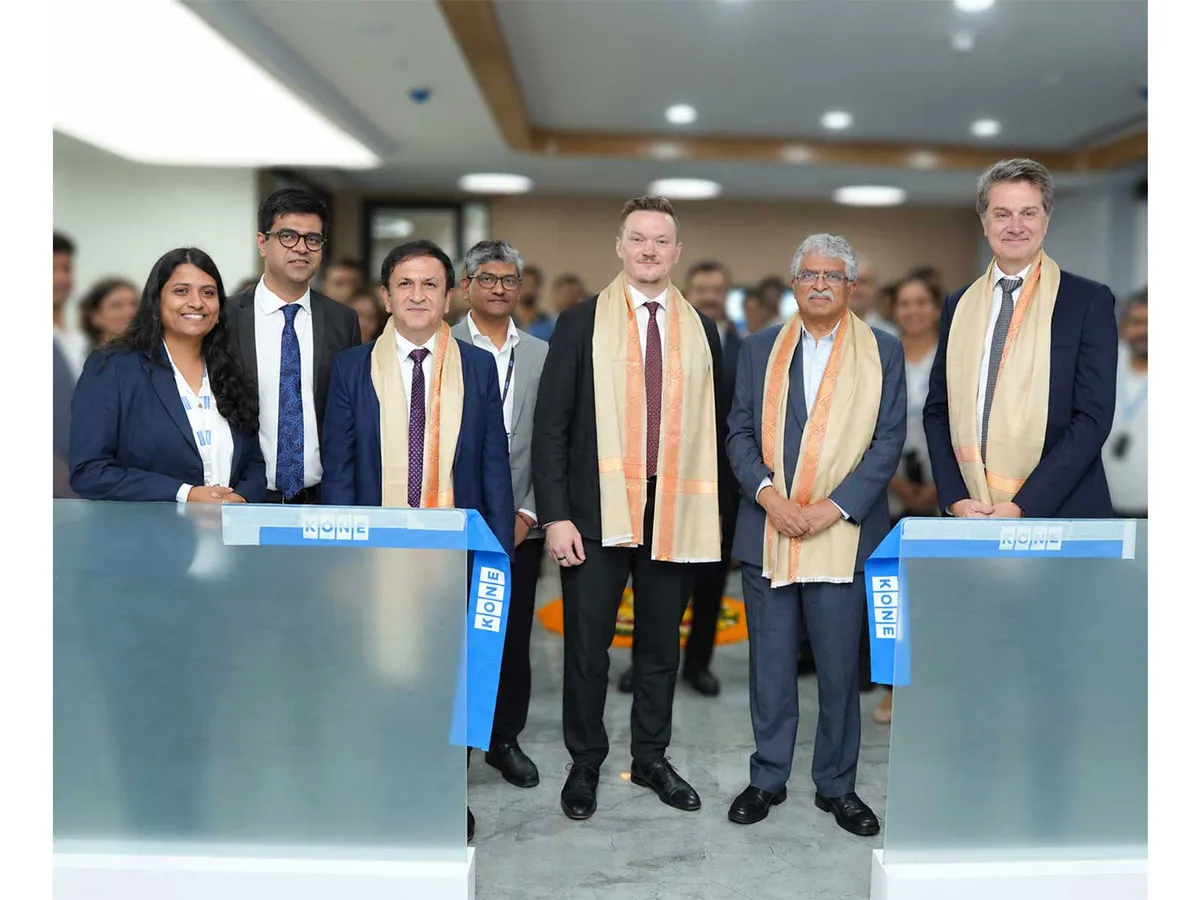
KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

CII GreenCo Launches Circularity Guidelines for Indian Industry

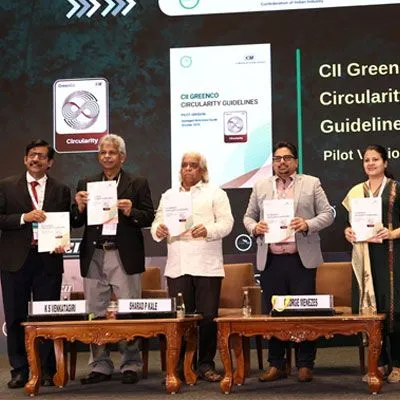
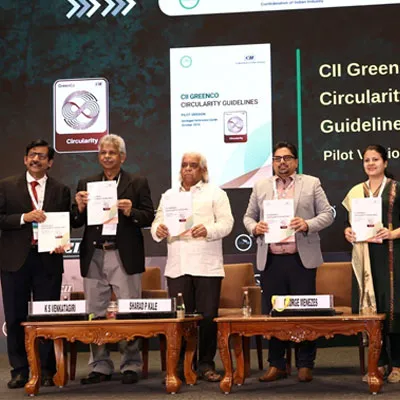
The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

Global Electronics Association Launches IPC-1783-CO2E Standard

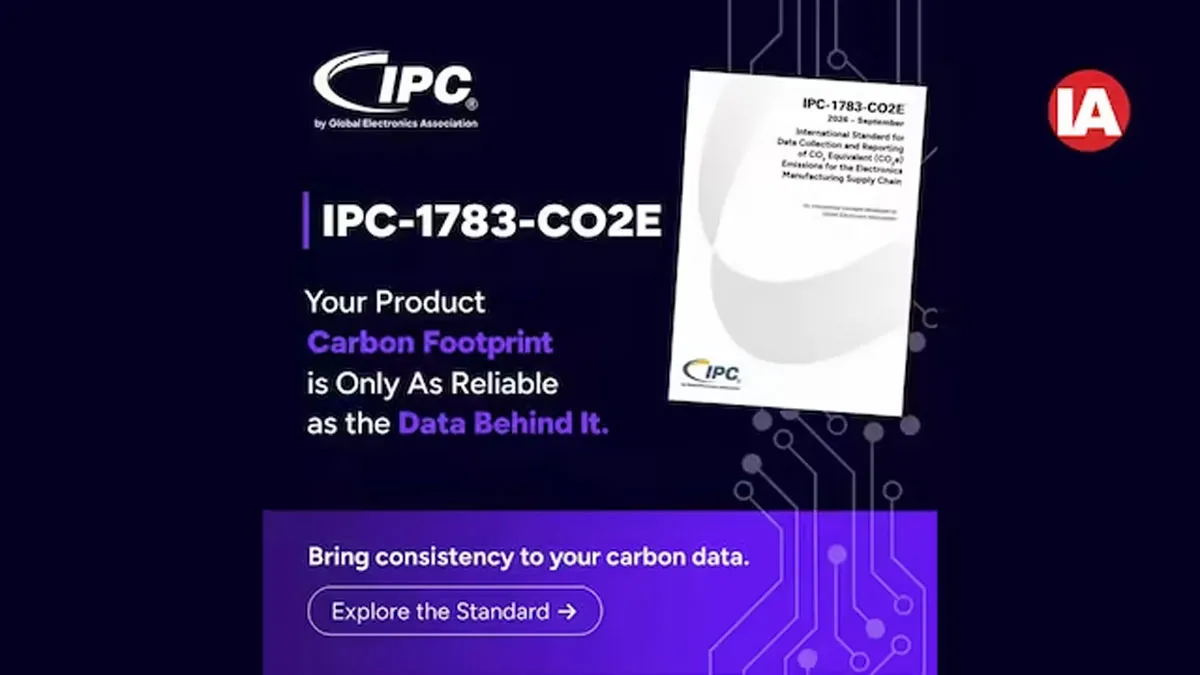
The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code