India's NHAI debt servicing cost to cross Rs 500 bn by FY28
ROADS & HIGHWAYS

India's NHAI debt servicing cost to cross Rs 500 bn by FY28

The Ministry of Road Transport and Highways has stated that the National Highways Authority of India (NHAI) will exceed Rs 500 billion in debt servicing costs by FY28, as estimated and shared with a Parliamentary standing committee.

Based on government projections, the cost of servicing the debt, including interest payments and bond redemption, will reach 20.5 per cent of budgetary support in five years. This forecast assumes continued growth in budgetary allocations until FY28, following the recent trend, and a continued freeze on new borrowings. As NHAI's debt surged between 2017-18 and 2021-22, the government prohibited further borrowing in 2022-23 and started providing greater financial provisions.

According to the Ministry of Road Transport and Highways, the NHAI's debt servicing costs will increase from Rs 332.61 billion in the current fiscal year to Rs 532.39 billion by FY28.

This highlights the urgency of attracting private investments to sustain the progress of highway construction in the country and the potential strain on the exchequer due to NHAI's weak financial position.

The government's policy think tank, Niti Aayog, recently invited bids from consultants to support an evaluation study of road projects and the functioning of NHAI.

The bid document issued by the Development Monitoring and Evaluation Office (DMEO), a part of Niti Aayog, suggests that a closer examination is required to assess NHAI's ability to manage its growing debt burden and achieve its highway development targets.

As of March 2022, NHAI's total debt stood at Rs 3.48 trillion, up from Rs 237.97 billion in 2014. The majority of this debt, amounting to Rs 3.27 trillion, was accumulated between 2017-18 and 2021-22, when the private sector withdrew from highway development due to disputes and delays in the build-operate-transfer (BOT) model.

The funds were raised through bonds in 112 instalments, with the final bond set to mature in 2050. Besides debt, NHAI also faces contingent liabilities, primarily arising from disputed claims filed by contractors and developers. As of March 31, 2020, NHAI had contingent liabilities totalling Rs 717.65 billion.

While the budgetary support to NHAI may appear substantial, it includes the road and infrastructure cess, toll collection, and proceeds from Infrastructure Investment Trusts (InvITs). All tolls collected on NHAI roads are deposited in the Consolidated Fund of India and then allocated to NHAI under the expenditure head of the Permanent Bridge Fee Fund (PBFF). Cess shares are routed through the Central Roads and Infrastructure Fund (CRIF).

According to budget documents, NHAI will receive Rs 1.62 trillion in FY24, of which Rs 208.07 billion will come from PBFF, Rs 100 billion from asset monetisation, and only Rs 1,400 from CRIF, indicating a significant decrease in the share of cess. The government and NHAI have been making efforts to address the situation by attempting to revive the BOT (toll) model and aggressively monetising operational highways. During the Covid-19 pandemic, when interest rates were low, NHAI negotiated lower rates on some of its debts, resulting in annual interest cost savings of Rs 4-5 billion, according to an official.

Between 2007 and 2014, only the BOT-toll model was used for highway construction, but it came to a halt thereafter. No projects were awarded on the BOT model in 2018-19 and 2019-20. The aim is to increase the share of BOT in highway construction to 10 per cent. Under the Engineering Procurement and Construction (EPC) model, the government bears the full cost of highways. In the Hybrid Annuity Model (HAM), the government pays 40 per cent of the construction cost upfront to concessionaires and the rest in instalments.

The government's target is to allocate 60 per cent of projects through HAM, 30 per cent through EPC, and 10 per cent through BOT. An ICRA report predicts that EPC will remain the dominant model, accounting for 70-75 per cent of highway construction projects this year, while BOT will be less than 5 per cent. Monetisation is another aspect of the plan to support highway development programs, with a target of raising Rs 450 billion from asset monetisation this year.

"The funds will be raised through toll-operate-transfer, infrastructure investment trust (InvIT), and asset-backed securitisation models, with an equal distribution among all three monetisation methods," stated an official.

In the previous financial year, NHAI raised Rs 142.68 billion from asset monetisation, falling short of the Rs 200 billion target. NHAI officials express confidence in improving toll collections. Asset monetisation and increased government support are expected to address the order and debt levels, according to a report by Kotak Institutional Equities.

Also Read
NITI Aayog seeks consultant to evaluate the operation of NHAI
Nitin Gadkari reviews progress of Kaziranga Elevated Road project


The Ministry of Road Transport and Highways has stated that the National Highways Authority of India (NHAI) will exceed Rs 500 billion in debt servicing costs by FY28, as estimated and shared with a Parliamentary standing committee. Based on government projections, the cost of servicing the debt, including interest payments and bond redemption, will reach 20.5 per cent of budgetary support in five years. This forecast assumes continued growth in budgetary allocations until FY28, following the recent trend, and a continued freeze on new borrowings. As NHAI's debt surged between 2017-18 and 2021-22, the government prohibited further borrowing in 2022-23 and started providing greater financial provisions. According to the Ministry of Road Transport and Highways, the NHAI's debt servicing costs will increase from Rs 332.61 billion in the current fiscal year to Rs 532.39 billion by FY28. This highlights the urgency of attracting private investments to sustain the progress of highway construction in the country and the potential strain on the exchequer due to NHAI's weak financial position. The government's policy think tank, Niti Aayog, recently invited bids from consultants to support an evaluation study of road projects and the functioning of NHAI. The bid document issued by the Development Monitoring and Evaluation Office (DMEO), a part of Niti Aayog, suggests that a closer examination is required to assess NHAI's ability to manage its growing debt burden and achieve its highway development targets. As of March 2022, NHAI's total debt stood at Rs 3.48 trillion, up from Rs 237.97 billion in 2014. The majority of this debt, amounting to Rs 3.27 trillion, was accumulated between 2017-18 and 2021-22, when the private sector withdrew from highway development due to disputes and delays in the build-operate-transfer (BOT) model. The funds were raised through bonds in 112 instalments, with the final bond set to mature in 2050. Besides debt, NHAI also faces contingent liabilities, primarily arising from disputed claims filed by contractors and developers. As of March 31, 2020, NHAI had contingent liabilities totalling Rs 717.65 billion. While the budgetary support to NHAI may appear substantial, it includes the road and infrastructure cess, toll collection, and proceeds from Infrastructure Investment Trusts (InvITs). All tolls collected on NHAI roads are deposited in the Consolidated Fund of India and then allocated to NHAI under the expenditure head of the Permanent Bridge Fee Fund (PBFF). Cess shares are routed through the Central Roads and Infrastructure Fund (CRIF). According to budget documents, NHAI will receive Rs 1.62 trillion in FY24, of which Rs 208.07 billion will come from PBFF, Rs 100 billion from asset monetisation, and only Rs 1,400 from CRIF, indicating a significant decrease in the share of cess. The government and NHAI have been making efforts to address the situation by attempting to revive the BOT (toll) model and aggressively monetising operational highways. During the Covid-19 pandemic, when interest rates were low, NHAI negotiated lower rates on some of its debts, resulting in annual interest cost savings of Rs 4-5 billion, according to an official. Between 2007 and 2014, only the BOT-toll model was used for highway construction, but it came to a halt thereafter. No projects were awarded on the BOT model in 2018-19 and 2019-20. The aim is to increase the share of BOT in highway construction to 10 per cent. Under the Engineering Procurement and Construction (EPC) model, the government bears the full cost of highways. In the Hybrid Annuity Model (HAM), the government pays 40 per cent of the construction cost upfront to concessionaires and the rest in instalments. The government's target is to allocate 60 per cent of projects through HAM, 30 per cent through EPC, and 10 per cent through BOT. An ICRA report predicts that EPC will remain the dominant model, accounting for 70-75 per cent of highway construction projects this year, while BOT will be less than 5 per cent. Monetisation is another aspect of the plan to support highway development programs, with a target of raising Rs 450 billion from asset monetisation this year. The funds will be raised through toll-operate-transfer, infrastructure investment trust (InvIT), and asset-backed securitisation models, with an equal distribution among all three monetisation methods, stated an official. In the previous financial year, NHAI raised Rs 142.68 billion from asset monetisation, falling short of the Rs 200 billion target. NHAI officials express confidence in improving toll collections. Asset monetisation and increased government support are expected to address the order and debt levels, according to a report by Kotak Institutional Equities. Also Read NITI Aayog seeks consultant to evaluate the operation of NHAINitin Gadkari reviews progress of Kaziranga Elevated Road project
Related Stories

Gold Stories

Next Story
Real Estate

Anshul Singhal launches Vantrock with Rs 42 billion development plan

Real estate professional Anshul Singhal has launched Vantrock Real Assets Private Limited (VRAPL), a Mumbai-headquartered platform focused initially on warehousing, industrial and logistics parks. The company plans to develop approximately 11.5 million sq ft of assets, with an estimated gross development value (GDV) of Rs 42 billion (approximately USD 434 million) on completion.The first phase will cover around 3 million sq ft across the National Capital Region (NCR), Bengaluru and Pune, with an estimated development value of Rs 11 billion (approximately USD 113 million). Construction is sched..

Next Story
Infrastructure Transport

Afcons wins CII award for biodiversity management

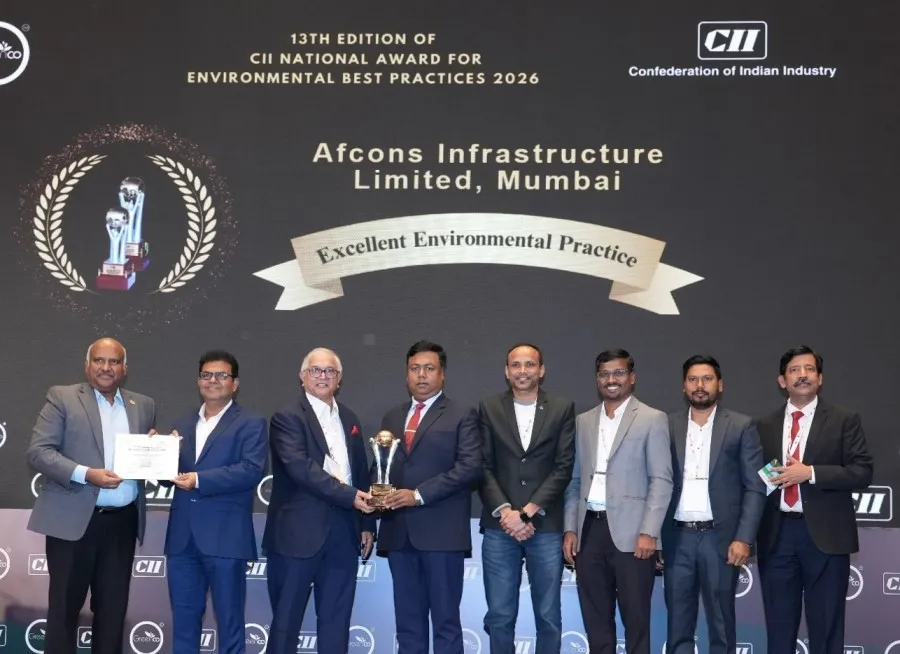
Afcons Infrastructure has received the Confederation of Indian Industry (CII) National Award for Environmental Best Practices 2026 in the Biodiversity Management category for its work on the Mumbai-Ahmedabad High Speed Rail Project’s C-2 package.The award was presented at a ceremony in Chennai on 9 October 2026. It was received by Mihir Mishra, Vice-President, CPE, and Sumon Paul, Assistant General Manager, HSE, along with the Afcons team.The project adopted several resource recovery and waste management practices. These included recycling concrete washout waste to recover sand, aggregates a..

Next Story
Technology

Indian businesses lead globally in planned AI investment, says Autodesk

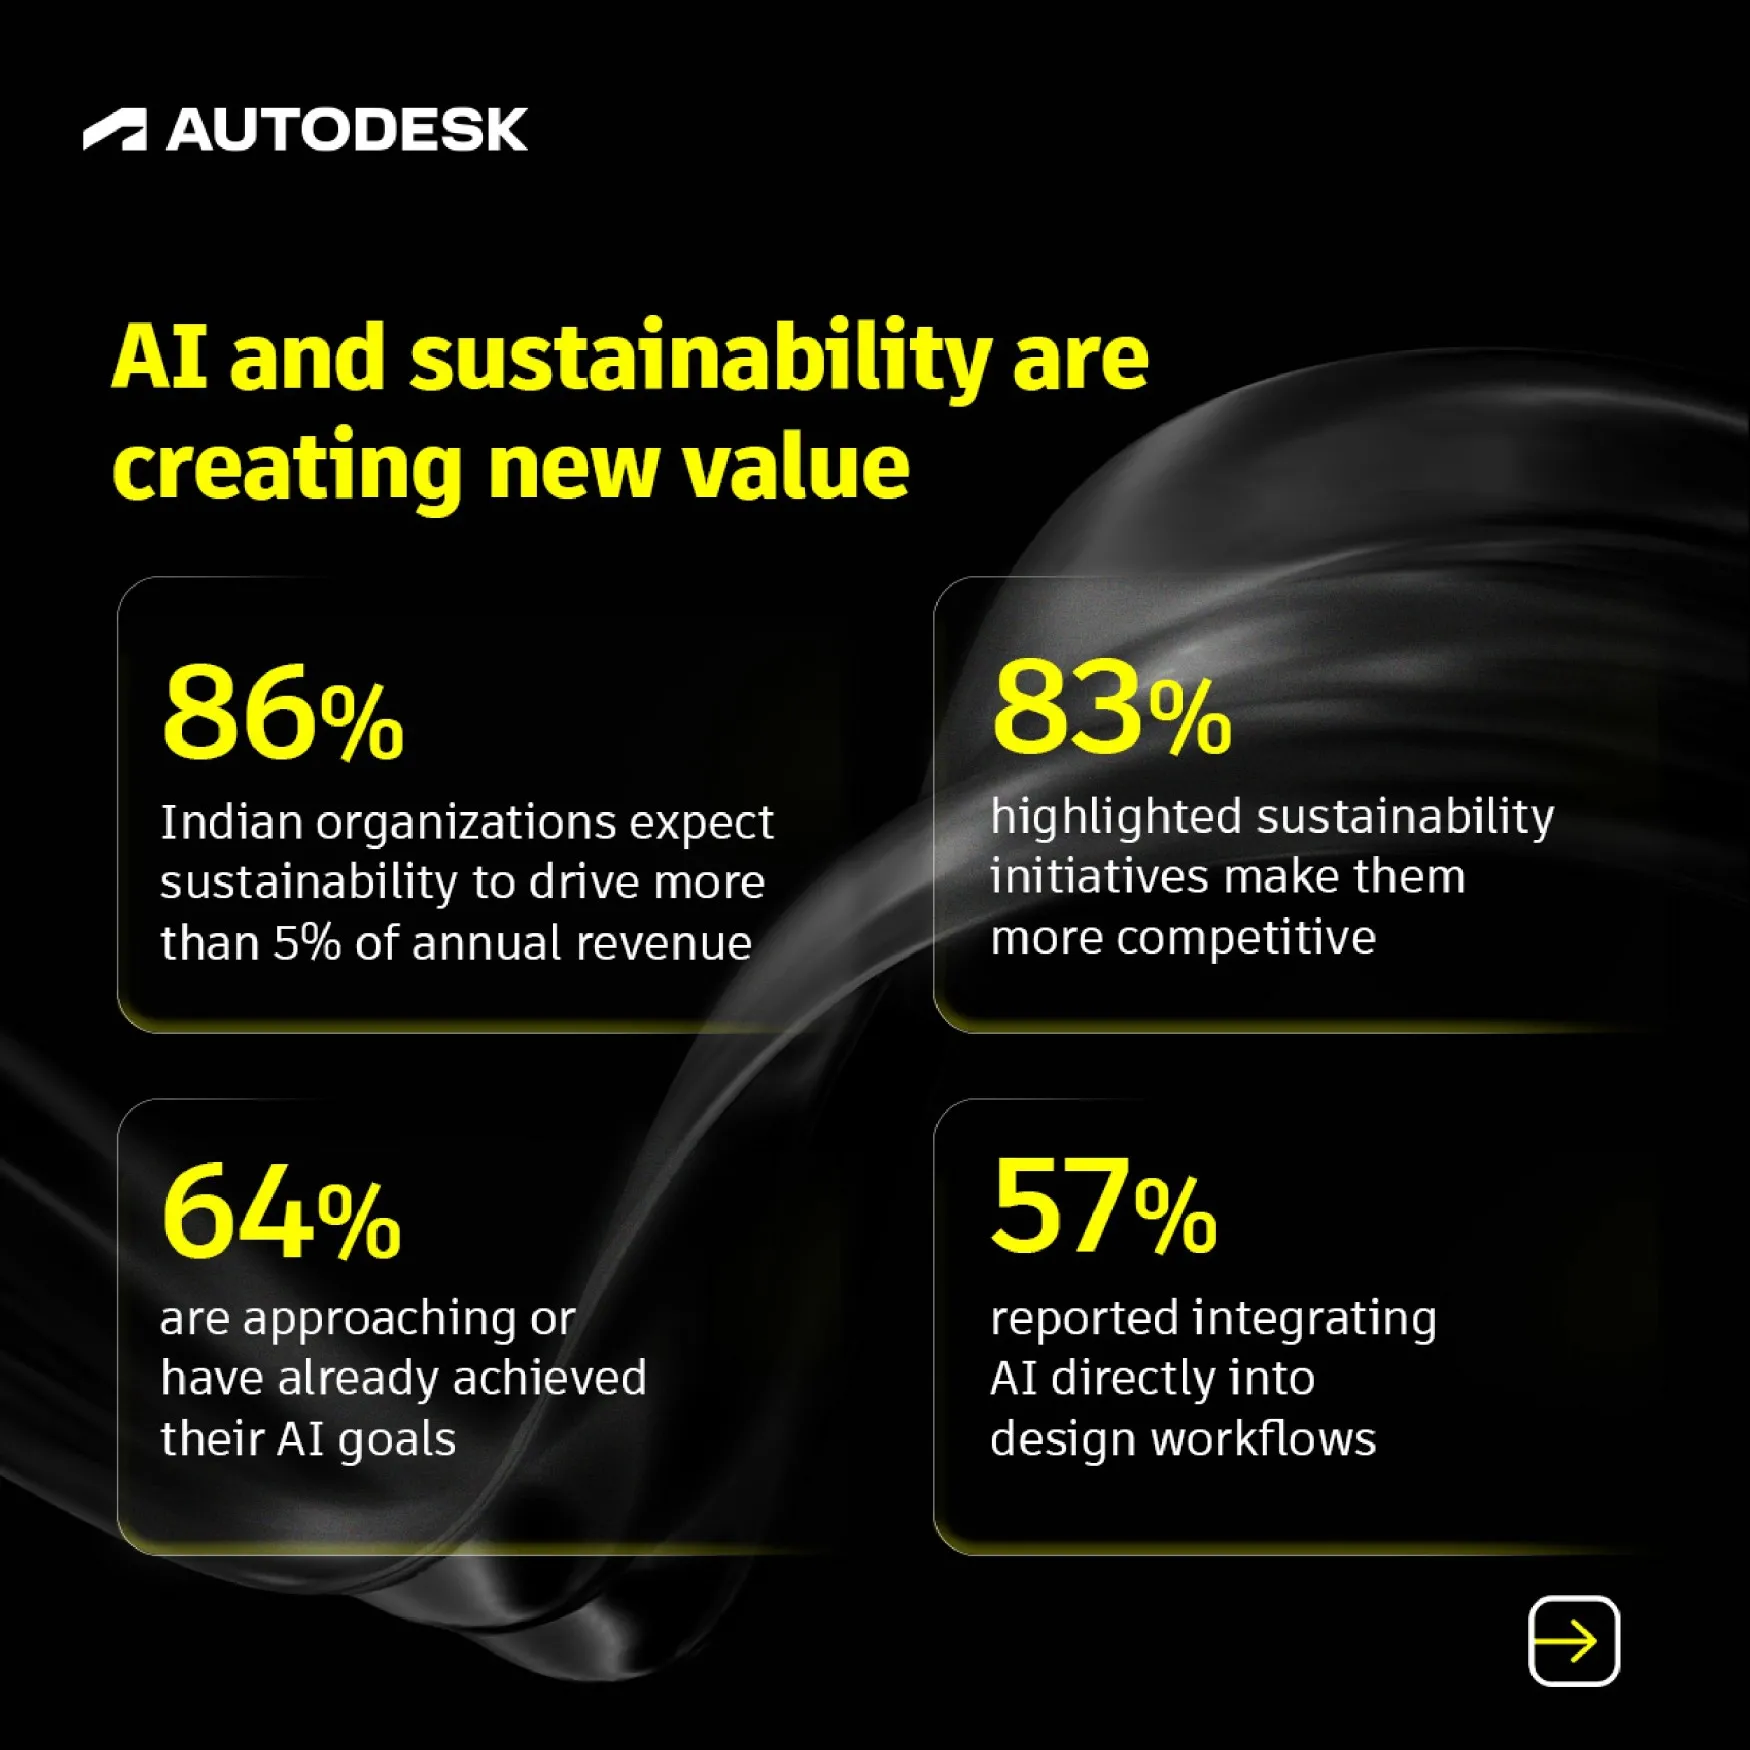
Indian organisations are moving towards deeper integration of artificial intelligence (AI), digital technologies and sustainability into business operations, according to Autodesk’s 2026 State of Design & Make report. The fourth edition of the annual study highlights growing AI adoption, measurable outcomes from digital transformation and the role of sustainability in long-term business growth.The report found that 64 per cent of Indian organisations are approaching or have achieved their current AI goals. While 88 per cent believe AI will enhance their industry, up from 78 per cent in 2..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code