+
Q3 2025: Housing Sales Volume Declines 9% Annually
Real Estate

Q3 2025: Housing Sales Volume Declines 9% Annually


India’s residential real estate market showed mixed trends in Q3 2025. Despite global economic uncertainties and affordability challenges, housing demand remained resilient, supported by rising incomes, urbanisation, and aspirational homeownership.

According to ANAROCK Research, housing sales across the top 7 cities stood at approx. 97,080 units in Q3 2025, a 9 per cent decline from 1,07,060 units in Q3 2024. However, the total sales value grew 14 per cent annually – from approx. Rs 1.33 trillion in Q3 2024 to approx. Rs 1.52 trillion in Q3 2025 – largely driven by higher traction in the luxury and ultra-luxury segments.

“While sales volumes dipped, they still outstripped new supply in the quarter, reflecting continued market health,” said Anuj Puri, Chairman – ANAROCK Group.

City-wise Performance
  • MMR led sales with approx. 30,260 units, followed by Pune with approx. 16,620 units. Together, they accounted for 48 per cent of total sales in the top 7 cities.
  • All cities saw annual dips in sales except Chennai (up 33 per cent) and Kolkata (up 4 per cent).
  • New launches rose marginally by 3 per cent YoY to approx. 96,690 units, with MMR (29,565 units) and Pune (19,375 units) leading supply. Pune, Kolkata, and Chennai posted the sharpest yearly rise in new supply.
Segment & Price Trends
  • The luxury housing segment (>Rs 10.5 Mn) dominated new supply with a 38% share, followed by the premium segment (Rs 8 million–10.5 Mn) at 24%.
  • The mid-segment (Rs 40–80 lakh) contributed 23%, while affordable housing had the lowest share at 16 per cent.
  • Available inventory dipped marginally from approx. 5,64,415 units in Q3 2024 to approx. 5,61,756 units in Q3 2025.
  • Average prices across the top 7 cities rose 9 per cent YoY, led by NCR (24 per cent %) and Bengaluru (10 per cent).
Despite the monsoon season and the traditionally slow ‘shraad’ period, sales rose 1 per cent quarterly, indicating steady momentum ahead of the festive season.

“The impact of the recently announced US H1-B visa norms on Indian housing demand will need close monitoring. While affordability challenges persist, price growth has moderated from the double-digit trends of recent years,” added Puri.

Overall, the market in 2025 remains reasonably steady, with expectations of a festive boost as developers prepare new project launches.

India’s residential real estate market showed mixed trends in Q3 2025. Despite global economic uncertainties and affordability challenges, housing demand remained resilient, supported by rising incomes, urbanisation, and aspirational homeownership.According to ANAROCK Research, housing sales across the top 7 cities stood at approx. 97,080 units in Q3 2025, a 9 per cent decline from 1,07,060 units in Q3 2024. However, the total sales value grew 14 per cent annually – from approx. Rs 1.33 trillion in Q3 2024 to approx. Rs 1.52 trillion in Q3 2025 – largely driven by higher traction in the luxury and ultra-luxury segments.“While sales volumes dipped, they still outstripped new supply in the quarter, reflecting continued market health,” said Anuj Puri, Chairman – ANAROCK Group.City-wise PerformanceMMR led sales with approx. 30,260 units, followed by Pune with approx. 16,620 units. Together, they accounted for 48 per cent of total sales in the top 7 cities.All cities saw annual dips in sales except Chennai (up 33 per cent) and Kolkata (up 4 per cent).New launches rose marginally by 3 per cent YoY to approx. 96,690 units, with MMR (29,565 units) and Pune (19,375 units) leading supply. Pune, Kolkata, and Chennai posted the sharpest yearly rise in new supply.Segment & Price TrendsThe luxury housing segment (>Rs 10.5 Mn) dominated new supply with a 38% share, followed by the premium segment (Rs 8 million–10.5 Mn) at 24%.The mid-segment (Rs 40–80 lakh) contributed 23%, while affordable housing had the lowest share at 16 per cent.Available inventory dipped marginally from approx. 5,64,415 units in Q3 2024 to approx. 5,61,756 units in Q3 2025.Average prices across the top 7 cities rose 9 per cent YoY, led by NCR (24 per cent %) and Bengaluru (10 per cent).Despite the monsoon season and the traditionally slow ‘shraad’ period, sales rose 1 per cent quarterly, indicating steady momentum ahead of the festive season.“The impact of the recently announced US H1-B visa norms on Indian housing demand will need close monitoring. While affordability challenges persist, price growth has moderated from the double-digit trends of recent years,” added Puri.Overall, the market in 2025 remains reasonably steady, with expectations of a festive boost as developers prepare new project launches.

Related Stories

Gold Stories
Next Story
Infrastructure Urban

KONE Opens India's First Digital Experience Centre in Pune

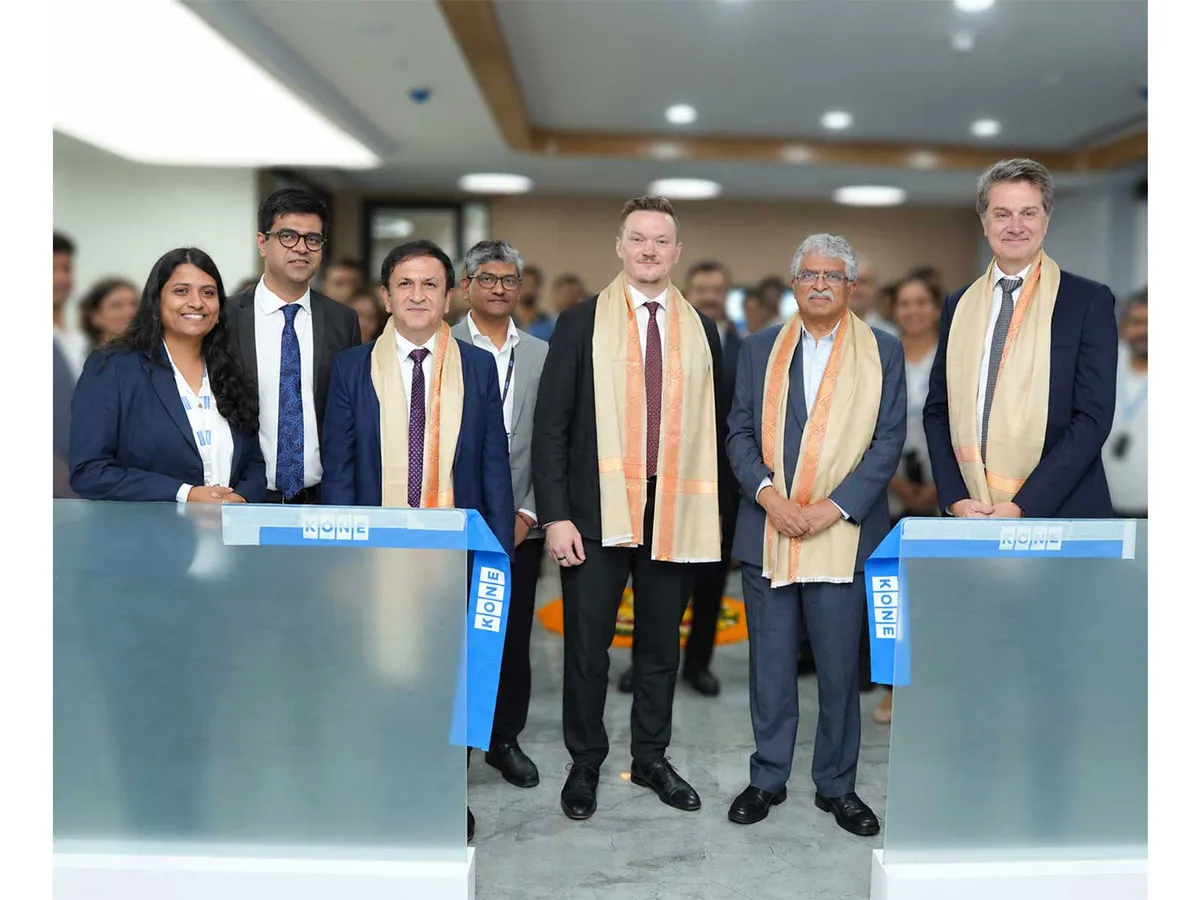
KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

CII GreenCo Launches Circularity Guidelines for Indian Industry

The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

Global Electronics Association Launches IPC-1783-CO2E Standard

The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code