Real estate biggies recovering much faster: ICRA
Real Estate

Real estate biggies recovering much faster: ICRA

According to a report by the Investment Information and Credit Rating Agency (ICRA), the residential real estate sector is witnessing a K shaped recovery, with large listed players recovering at a much better pace than smaller unorganised players.

While the broader market remained 24% below pre Covid levels on a year-on-year (y-o-y) basis in quarter three (Q3) of the financial year (FY) 2021 and 39% below pre Covid levels in nine months (9M) of FY21, the top 10 listed realty players witnessed a 61% y-o-y growth in Q3 FY21 and 13% growth in 9M FY21.

This gap in sales growth rates led to accelerated consolidation in the aftermath of Covid-19, and the market share of the top 10 listed realty players has nearly doubled in the current year, increasing from 11% of sales in FY20 to 19% in 9M FY21.


4th Indian Cement Review Conference 2021

17-18 March 

Click for event info


While the de-growth was limited to 24% by Q3 FY21, larger players recorded a much better recovery, registering y-o-y sales growth of 61% in Q3 FY21. Before the onset of the pandemic, homebuyers had been leaning towards developers with an established track record of on-time and quality project completion, which had resulted in large, listed players reporting healthy sales and collections in recent years, despite the prevailing liquidity crisis and unfavourable supply demand dynamics.

The implementation of GST and RERA further supported the market position of these larger players, with their market share increasing from 6% of sales in FY2017 to over 10% in FY2019 and FY2020.

In the aftermath of Covid-19, these players have further strengthened their market share to 19% of sales. In terms of launches as well, their market share has increased to a five year high of 22%. Post pandemic, better demand prospects, strong balance sheets, and adequate liquidity have enabled larger developers to handle the unstable market situation better than smaller players who have been finding it difficult to cope with prevailing market conditions.

Attractive discounts and payment schemes have provided further fillip. With the onset of the pandemic, home and holiday home ownership has also become more important.

To read the detailed ICRA report click here.

Image: With the onset of Covid-19, collections against committed sales receivables have slowed down due to deferment of mile-stone based payment demands, given the lower pace of execution, and delay in payments by some buyers on account of economic uncertainties, the report says.


Also read: 57% people now prefer homes over other investments: Survey

Also read: Lower GST on unfinished homes would add to affordability: Keki Mistry

According to a report by the Investment Information and Credit Rating Agency (ICRA), the residential real estate sector is witnessing a K shaped recovery, with large listed players recovering at a much better pace than smaller unorganised players. While the broader market remained 24% below pre Covid levels on a year-on-year (y-o-y) basis in quarter three (Q3) of the financial year (FY) 2021 and 39% below pre Covid levels in nine months (9M) of FY21, the top 10 listed realty players witnessed a 61% y-o-y growth in Q3 FY21 and 13% growth in 9M FY21. This gap in sales growth rates led to accelerated consolidation in the aftermath of Covid-19, and the market share of the top 10 listed realty players has nearly doubled in the current year, increasing from 11% of sales in FY20 to 19% in 9M FY21.4th Indian Cement Review Conference 202117-18 March Click for event info While the de-growth was limited to 24% by Q3 FY21, larger players recorded a much better recovery, registering y-o-y sales growth of 61% in Q3 FY21. Before the onset of the pandemic, homebuyers had been leaning towards developers with an established track record of on-time and quality project completion, which had resulted in large, listed players reporting healthy sales and collections in recent years, despite the prevailing liquidity crisis and unfavourable supply demand dynamics. The implementation of GST and RERA further supported the market position of these larger players, with their market share increasing from 6% of sales in FY2017 to over 10% in FY2019 and FY2020. In the aftermath of Covid-19, these players have further strengthened their market share to 19% of sales. In terms of launches as well, their market share has increased to a five year high of 22%. Post pandemic, better demand prospects, strong balance sheets, and adequate liquidity have enabled larger developers to handle the unstable market situation better than smaller players who have been finding it difficult to cope with prevailing market conditions. Attractive discounts and payment schemes have provided further fillip. With the onset of the pandemic, home and holiday home ownership has also become more important. To read the detailed ICRA report click here.Image: With the onset of Covid-19, collections against committed sales receivables have slowed down due to deferment of mile-stone based payment demands, given the lower pace of execution, and delay in payments by some buyers on account of economic uncertainties, the report says. Also read: 57% people now prefer homes over other investments: Survey Also read: Lower GST on unfinished homes would add to affordability: Keki Mistry

Related Stories

Gold Stories
Next Story
Infrastructure Urban

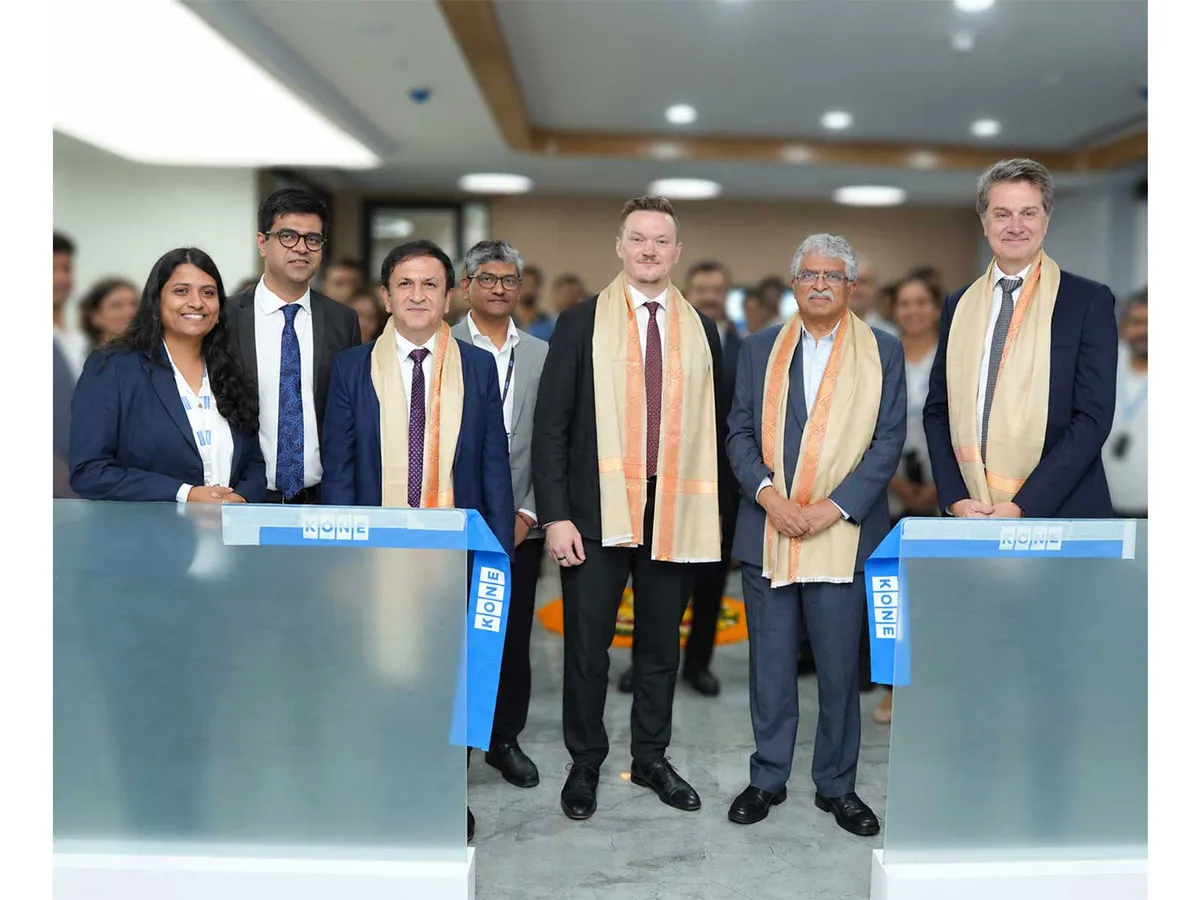
KONE Opens India's First Digital Experience Centre in Pune

KONE, a global elevator and escalator manufacturer, has inaugurated its first Digital Experience Centre (DEC) in India, located in Pune. The facility aims to showcase how artificial intelligence (AI), connectivity and data-driven technologies can enhance customer experiences and improve building operations.The centre was inaugurated by Jussi Herlin, Executive Vice Chair, KONE Corporation; Philippe Delorme, President and CEO, KONE; and Nandan Nilekani, Co-founder and Chairman of the Board, Infosys.Designed as an interactive customer environment, the facility demonstrates digital solutions cover..
Next Story
Infrastructure Urban

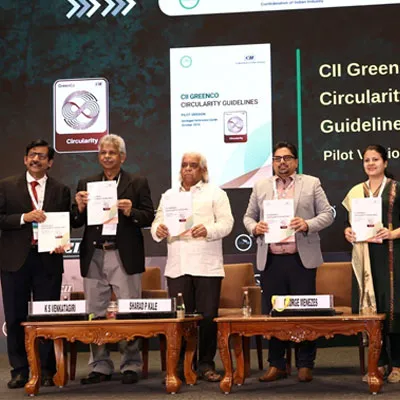
CII GreenCo Launches Circularity Guidelines for Indian Industry

The Confederation of Indian Industry (CII) GreenCo Council has launched the CII GreenCo Circularity Guidelines – Pilot Version at the 17th CII GreenCo Waste & Resource Management Summit 2026 in Chennai. The initiative aims to strengthen resource efficiency, waste reduction and circular economy practices across Indian manufacturing and process industries.The guidelines introduce a structured framework with circularity indices covering raw materials, consumables, packaging and other resource inputs. These indicators will help industries assess existing practices, identify opportunities to ..
Next Story
Infrastructure Energy

Global Electronics Association Launches IPC-1783-CO2E Standard

The Global Electronics Association has introduced IPC-1783-CO2E, a new international standard aimed at improving consistency, transparency and comparability in product carbon footprint reporting across the electronics manufacturing industry.The standard, titled International Standard for Data Collection and Reporting of CO2 Equivalent (CO2e) Emissions for the Electronics Manufacturing Supply Chain, provides industry-specific guidance for collecting, estimating and reporting carbon emissions data.With increasing regulatory requirements and customer expectations, electronics manufacturers face c..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code