+
ICRA says domestic commercial vehicle sales will dip by 4'7%
ECONOMY & POLICY

ICRA says domestic commercial vehicle sales will dip by 4'7%

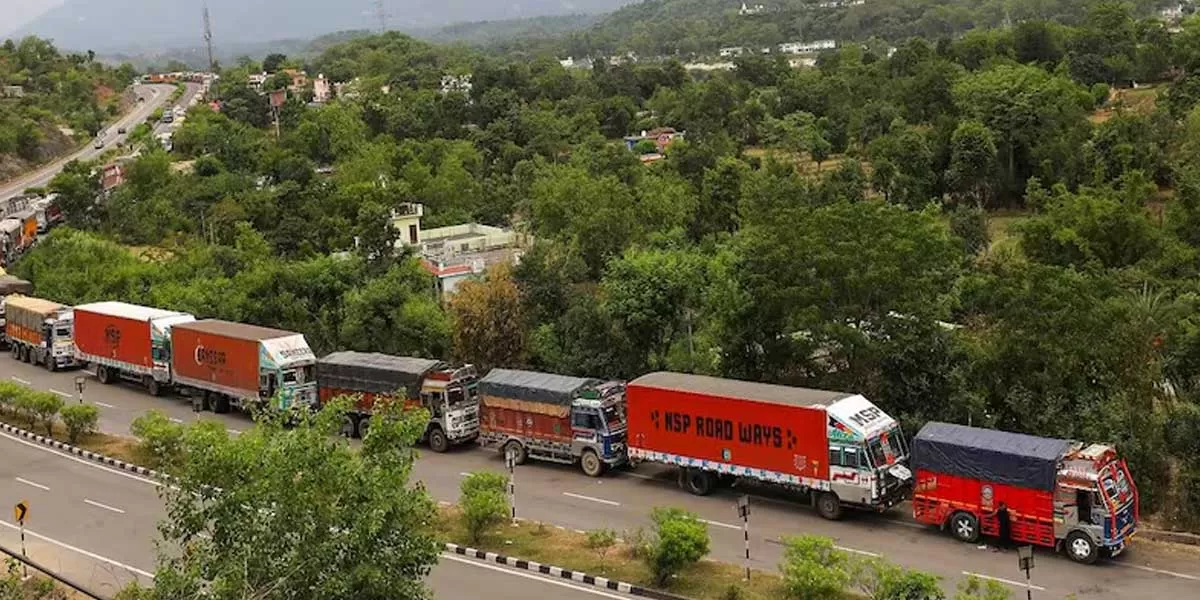
The rating agency ICRA projects a 4'7% drop in wholesale volumes for the Indian commercial vehicle (CV) market in FY25. The predicted recession comes after a period of restrained growth and a number of contributing variables, including the large base effect from prior fiscal years and a slowdown in economic activity because of the 2024 general elections. The first few months of FY25 are probably going to be impacted by infrastructure projects, which will further impair CV demand.
The industry suffered a modest 0.7% year-over-year fall in wholesale volumes in February 2024, although it managed a 5.1% sequential rise. This inconsistent performance was ascribed to larger base effects and decreased building activity prior to the General Elections Model Code of Conduct's introduction. On the other hand, retail volumes decreased sequentially by 0.9% but increased by 4.8% year over year.
Kinjal Shah, Vice President and Co-Group Head of Corporate Ratings at ICRA, stated that the significant growth in volumes and tonnage during FY22 and FY23 established a high base. This, combined with the economic slowdown preceding the general elections, is anticipated to contribute to the projected decline in FY25. Despite a 2.1% year-on-year growth in domestic CV wholesale volumes during the first 11 months of FY24, a slowdown in construction activities towards the end of the financial year counteracted initial gains.
The medium and heavy commercial vehicles (M&HCV) segment is forecast to experience a decline of 4?7% in FY25. This segment concluded FY24 with 4% year-on-year growth, primarily influenced by an improved macroeconomic environment and increased freight availability earlier in the financial year. However, subdued demand in subsequent months led to an overall decline.
Similarly, the light commercial vehicles (LCV) segment is expected to undergo a downturn, with an estimated decline of 5-8% in FY25. Factors contributing to this decline include the high base effect, a sustained slowdown in e-commerce, and competition from electric three-wheelers (e3Ws). The LCV segment witnessed a 3% year-on-year decline in FY24 due to these challenges, compounded by a deficiency in rainfall impacting the rural economy.
Conversely, the bus segment is predicted to grow by 2-5% in FY25, driven by replacement demand from state road transport undertakings (SRTUs) and the scrappage of older government vehicles. This segment surpassed pre-COVID levels in FY24, recording a notable 27% year-on-year growth, supported by low base effects and increasing adoption of electric buses.
According to the Federation of Automobile Dealers Association (FADA), commercial vehicle original equipment manufacturer (OEM) sales in April 2024 totaled 90,707 units, compared to 88,663 units in April 2023, reflecting a 2.3% increase.
Additionally, ICRA projects a slight drop in domestic CV manufacturers' operating profit margins (OPM) to 8.5?9.5% in FY25. Lower volumes and more pricing pressure from competitors are to blame for this. Thanks to favourable commodity prices and record-high industrial volumes, the OPM increased by 250?300 basis points in FY24.
The sector is expected to have more investment in the future; capital expenditures are expected to climb from Rs 37 billion in FY24 to around Rs 59 billion in FY25. Product development, technological advancements, and capital expenses linked to maintenance will be the key targets of these investments.
Although the domestic CV industry's near-term outlook seems difficult, the long-term growth drivers are still strong. These include ongoing infrastructure development, a rise in mining operations, and enhanced connections between roads and highways. The replacement demand, especially because of an ageing fleet, is likely to underpin CV volumes in the medium term, although the predicted fall is in FY25.    

The rating agency ICRA projects a 4'7% drop in wholesale volumes for the Indian commercial vehicle (CV) market in FY25. The predicted recession comes after a period of restrained growth and a number of contributing variables, including the large base effect from prior fiscal years and a slowdown in economic activity because of the 2024 general elections. The first few months of FY25 are probably going to be impacted by infrastructure projects, which will further impair CV demand.The industry suffered a modest 0.7% year-over-year fall in wholesale volumes in February 2024, although it managed a 5.1% sequential rise. This inconsistent performance was ascribed to larger base effects and decreased building activity prior to the General Elections Model Code of Conduct's introduction. On the other hand, retail volumes decreased sequentially by 0.9% but increased by 4.8% year over year.Kinjal Shah, Vice President and Co-Group Head of Corporate Ratings at ICRA, stated that the significant growth in volumes and tonnage during FY22 and FY23 established a high base. This, combined with the economic slowdown preceding the general elections, is anticipated to contribute to the projected decline in FY25. Despite a 2.1% year-on-year growth in domestic CV wholesale volumes during the first 11 months of FY24, a slowdown in construction activities towards the end of the financial year counteracted initial gains.The medium and heavy commercial vehicles (M&HCV) segment is forecast to experience a decline of 4?7% in FY25. This segment concluded FY24 with 4% year-on-year growth, primarily influenced by an improved macroeconomic environment and increased freight availability earlier in the financial year. However, subdued demand in subsequent months led to an overall decline.Similarly, the light commercial vehicles (LCV) segment is expected to undergo a downturn, with an estimated decline of 5-8% in FY25. Factors contributing to this decline include the high base effect, a sustained slowdown in e-commerce, and competition from electric three-wheelers (e3Ws). The LCV segment witnessed a 3% year-on-year decline in FY24 due to these challenges, compounded by a deficiency in rainfall impacting the rural economy.Conversely, the bus segment is predicted to grow by 2-5% in FY25, driven by replacement demand from state road transport undertakings (SRTUs) and the scrappage of older government vehicles. This segment surpassed pre-COVID levels in FY24, recording a notable 27% year-on-year growth, supported by low base effects and increasing adoption of electric buses.According to the Federation of Automobile Dealers Association (FADA), commercial vehicle original equipment manufacturer (OEM) sales in April 2024 totaled 90,707 units, compared to 88,663 units in April 2023, reflecting a 2.3% increase.Additionally, ICRA projects a slight drop in domestic CV manufacturers' operating profit margins (OPM) to 8.5?9.5% in FY25. Lower volumes and more pricing pressure from competitors are to blame for this. Thanks to favourable commodity prices and record-high industrial volumes, the OPM increased by 250?300 basis points in FY24.The sector is expected to have more investment in the future; capital expenditures are expected to climb from Rs 37 billion in FY24 to around Rs 59 billion in FY25. Product development, technological advancements, and capital expenses linked to maintenance will be the key targets of these investments.Although the domestic CV industry's near-term outlook seems difficult, the long-term growth drivers are still strong. These include ongoing infrastructure development, a rise in mining operations, and enhanced connections between roads and highways. The replacement demand, especially because of an ageing fleet, is likely to underpin CV volumes in the medium term, although the predicted fall is in FY25.    

Related Stories

Gold Stories
Next Story
Real Estate

Peninsula Land launches 19 luxury villas in Pune

Pune’s residential landscape is witnessing a shift as premium homebuyers increasingly seek larger spaces, privacy and independent living options beyond high-rise apartments. Addressing this demand, Peninsula Land Limited, part of the Ashok Piramal Group, has launched AshokVillas, an exclusive collection of 19 premium furnished villas in Gahunje, Pune.The development combines the independence of a standalone home with the convenience and security of a managed residential community. Designed around low-density horizontal living, AshokVillas offers residents private spaces while providing acces..
Next Story
Infrastructure Urban

MyBranch Expands South India Network with 16 Workspace Centres

MyBranch has expanded its South India presence with a 50,000 sq ft flexible workspace network comprising 16 centres across 14 cities in Andhra Pradesh, Karnataka, Tamil Nadu and Telangana.The expansion reflects growing demand for flexible office infrastructure as businesses establish regional teams, satellite offices and operations beyond traditional metropolitan markets. MyBranch’s network spans Bengaluru, Coimbatore, Guntur, Hanamkonda, Hubballi, Hyderabad, Madurai, Mangaluru, Rajahmundry, Salem, Tirupati, Vellore, Vijayawada and Visakhapatnam, with a large office space in Chennai also und..
Next Story
Building Material

Walplast Launches Moisture-Resistant Gypsum Plaster Solutions

Walplast Products Pvt. Ltd. has expanded its HomeSure GypEx portfolio with the launch of GypEx MoistShield and GypEx Gold, two gypsum plaster solutions designed to address moisture-prone applications and improve plastering efficiency.The new products have been developed in response to the growing demand for faster construction processes, improved material performance and consistent surface quality. The solutions aim to simplify interior plastering while addressing specific application requirements across construction environments.“Through HomeSure GypEx MoistShield and GypEx Gold, we are exp..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code