+
China's Steel Sector Is Softening, but With Resilience
Steel

China's Steel Sector Is Softening, but With Resilience

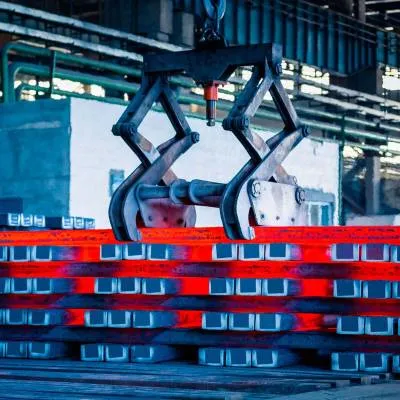
There are two ways of looking at the 1.7% decline in China's steel output last year.The first is that it confirms that the world's largest producer of the key industrial metal is now in an established downtrend, and further weakness is likely this year. The second is that the steel industry is actually remarkably resilient in the face of major economic challenges, and that output has been essentially flat at extremely strong levels for the past five years. Both are essentially factual, and reflect the classic glass half-full or half-empty dilemma. On the half-empty side of the ledger is the fact that China's steel production peaked at 1.065 billion metric tons in 2020, and has trended lower since then, with 2024 output coming in at 1.005 billion tons. But another way to look at China's steel output is that it has been within a 70 million ton range between 2019 and 2024, which is actually quite a stable performance. Perhaps the best way to characterise China's steel production is that it likely has peaked, but the decline so far has been gentle, and output remains relatively high despite the well-publicised struggles of the world's second-biggest economy since the COVID-19 pandemic. Similar to other markets, the answer remains unclear and subject to factors yet to come into play, chief among them what trade tariffs are put in place by the new administration of U.S. President Donald Trump, who resumed the office . It's also uncertain as to whether 2025 is the year China's struggling residential property sector gets back on its feet, or whether it remains hostage to weak developer balance sheets and consumer wariness. A third factor is what will happen to China's steel exports in 2025, after they hit a nine-year high of 110.72 million tons in 2024. This was up 22.7%, or just over 20 million tons, from the previous year, with the increase helping to offset some loss of domestic consumption for steel mills. The volume of Chinese steel hitting global markets has led to some consternation among countries such as India, which is trying to boost the pace of expansion of its own steel sector. This raises the possibility that China may find it harder to increase steel exports in 2025.But it is worth noting that not all importing countries are opposed to buying more steel from China, especially those without a domestic steel sector. The best-case scenario for China's steel sector this year is one where trade tariffs aren't too punitive, the domestic economy continues to regain momentum and construction activity stabilises, or perhaps even increases. Under such a scenario, the best outcome for China's steel production would be steady output around 1 billion tons. This also means that China's demand for iron ore is likely to remain steady as well, although it may ease from the record high of 1.24 billion tons in 2024.

There are two ways of looking at the 1.7% decline in China's steel output last year.The first is that it confirms that the world's largest producer of the key industrial metal is now in an established downtrend, and further weakness is likely this year. The second is that the steel industry is actually remarkably resilient in the face of major economic challenges, and that output has been essentially flat at extremely strong levels for the past five years. Both are essentially factual, and reflect the classic glass half-full or half-empty dilemma. On the half-empty side of the ledger is the fact that China's steel production peaked at 1.065 billion metric tons in 2020, and has trended lower since then, with 2024 output coming in at 1.005 billion tons. But another way to look at China's steel output is that it has been within a 70 million ton range between 2019 and 2024, which is actually quite a stable performance. Perhaps the best way to characterise China's steel production is that it likely has peaked, but the decline so far has been gentle, and output remains relatively high despite the well-publicised struggles of the world's second-biggest economy since the COVID-19 pandemic. Similar to other markets, the answer remains unclear and subject to factors yet to come into play, chief among them what trade tariffs are put in place by the new administration of U.S. President Donald Trump, who resumed the office . It's also uncertain as to whether 2025 is the year China's struggling residential property sector gets back on its feet, or whether it remains hostage to weak developer balance sheets and consumer wariness. A third factor is what will happen to China's steel exports in 2025, after they hit a nine-year high of 110.72 million tons in 2024. This was up 22.7%, or just over 20 million tons, from the previous year, with the increase helping to offset some loss of domestic consumption for steel mills. The volume of Chinese steel hitting global markets has led to some consternation among countries such as India, which is trying to boost the pace of expansion of its own steel sector. This raises the possibility that China may find it harder to increase steel exports in 2025.But it is worth noting that not all importing countries are opposed to buying more steel from China, especially those without a domestic steel sector. The best-case scenario for China's steel sector this year is one where trade tariffs aren't too punitive, the domestic economy continues to regain momentum and construction activity stabilises, or perhaps even increases. Under such a scenario, the best outcome for China's steel production would be steady output around 1 billion tons. This also means that China's demand for iron ore is likely to remain steady as well, although it may ease from the record high of 1.24 billion tons in 2024.

Related Stories

Gold Stories
Next Story
Real Estate

We engineer the way architecture gets built

DALBIR SINGH, Founder, HAACE, on the company’s bespoke approach to translating ambitious architecture into precisely engineered and executed structures.What does bespoke construction mean to HAACE, and how is it different from conventional contracting?For HAACE, bespoke construction means choosing the construction methodology around the design rather than forcing the design into a standard template. Every project is studied around its architectural intent, structural requirements and execution challenges. We deliberately take on a limited number of projects because this approach demands atte..
Next Story
Real Estate

Kamdhenu Realities acquires 4-acre Navi Mumbai land parcel

Kamdhenu Realities has acquired a 4-acre land parcel from RPG Life Sciences on Thane-Belapur Road for approximately Rs 1.5 billion, expanding its commercial real estate portfolio in Navi Mumbai.The parcel has a total developable potential of 1.8 million sq ft, on which Kamdhenu plans to develop a destination-scale commercial and lifestyle ecosystem. The proposed development will combine corporate office suites with high-street retail, F&B outlets, double-height lobbies, business infrastructure and lifestyle amenities.Located close to IKEA and opposite the upcoming Pawane Railway Station, t..
Next Story
Infrastructure Transport

97 Per Cent Of Rongjeng-Mangsang-Adokgre Road Nears Completion

Deputy Chief Minister in-charge of public works Prestone Tynsong said in Shillong on 26 August that 97 per cent physical progress had been achieved on the ongoing Rongjeng-Mangsang-Adokgre road being constructed under the Non-Lapsable Central Pool of Resources (NLCPR). He noted the project was sanctioned in 2017 and that the stipulated time for completion had been 24 months from issue of the final work order. The deputy chief minister informed the assembly that the government had decided to include the remaining work under a World Bank project. In reply to a query from Rongjeng MLA Jim M Sangm..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code