Seshaasai Reports Q4FY26 Revenue Growth And Strong Margins
ECONOMY & POLICY

Seshaasai Reports Q4FY26 Revenue Growth And Strong Margins

Seshaasai Technologies Limited (BSE: 544533) reported consolidated results for the fourth quarter and year ended 31 March 2026. Revenue from operations was Rs 4,041.76 million (mn), representing quarter-on-quarter growth of eight point one per cent and year-on-year growth of nine point six per cent. The company attributed the momentum to its focused verticals of payment solutions, communication, fulfilment, and IoT. Payment solutions accounted for around forty eight per cent of revenues, communication and fulfilment forty per cent and IoT approximately twelve per cent.

EBITDA for the quarter was Rs 1,244.95 million, up 22.8 per cent year-on-year, with an EBITDA margin of 30.8 per cent, an improvement of 330 basis points year-on-year. Profit after tax for the quarter was Rs 817.87 million, up 29.9 per cent, with a PAT margin of 20.2 per cent. Top 10 customers contributed 62.8 per cent of revenues, underscoring concentration in the client base. The company cited operating leverage, improved business mix and procurement efficiencies as drivers of margin expansion.

For the full year FY26, revenue from operations was Rs 14,411.35 million, a marginal decline of 1.5 per cent year-on-year, attributed to softer demand in parts of the year, especially payment card issuance and renewals in the BFSI sector. Annual EBITDA was Rs 3,940.89 mn with an EBITDA margin of 27.4 per cent, an increase of 204 basis points year-on-year. Profit after tax for FY26 was Rs 2,400.1 mn, delivering a PAT margin of 16.7 per cent. Management noted benefits from recurring enterprise-grade contracts and diversification into non-payments segments.

The board has proposed a final dividend of Rs two point five per share for FY26 and management indicated continued focus on sustaining margin discipline, strengthening cash flows and scaling solutions. Executives said investments in capabilities and customer engagement are translating into stronger operating leverage and a more balanced revenue mix. The consolidated results were accompanied by an auditor report and the company included standard forward-looking disclaimers regarding risks and uncertainties. The announcement is available on the company website and BSE filings.

Seshaasai Technologies Limited (BSE: 544533) reported consolidated results for the fourth quarter and year ended 31 March 2026. Revenue from operations was Rs 4,041.76 million (mn), representing quarter-on-quarter growth of eight point one per cent and year-on-year growth of nine point six per cent. The company attributed the momentum to its focused verticals of payment solutions, communication, fulfilment, and IoT. Payment solutions accounted for around forty eight per cent of revenues, communication and fulfilment forty per cent and IoT approximately twelve per cent. EBITDA for the quarter was Rs 1,244.95 million, up 22.8 per cent year-on-year, with an EBITDA margin of 30.8 per cent, an improvement of 330 basis points year-on-year. Profit after tax for the quarter was Rs 817.87 million, up 29.9 per cent, with a PAT margin of 20.2 per cent. Top 10 customers contributed 62.8 per cent of revenues, underscoring concentration in the client base. The company cited operating leverage, improved business mix and procurement efficiencies as drivers of margin expansion. For the full year FY26, revenue from operations was Rs 14,411.35 million, a marginal decline of 1.5 per cent year-on-year, attributed to softer demand in parts of the year, especially payment card issuance and renewals in the BFSI sector. Annual EBITDA was Rs 3,940.89 mn with an EBITDA margin of 27.4 per cent, an increase of 204 basis points year-on-year. Profit after tax for FY26 was Rs 2,400.1 mn, delivering a PAT margin of 16.7 per cent. Management noted benefits from recurring enterprise-grade contracts and diversification into non-payments segments. The board has proposed a final dividend of Rs two point five per share for FY26 and management indicated continued focus on sustaining margin discipline, strengthening cash flows and scaling solutions. Executives said investments in capabilities and customer engagement are translating into stronger operating leverage and a more balanced revenue mix. The consolidated results were accompanied by an auditor report and the company included standard forward-looking disclaimers regarding risks and uncertainties. The announcement is available on the company website and BSE filings.

Related Stories

Gold Stories

Next Story
Resources

Schindler named among Forbes’ World’s Best Employers 2026

Schindler has been named among Forbes’ World’s Best Employers 2026, a global ranking recognising companies for their workplace environments.Compiled by Forbes in partnership with Statista, the ranking is based on independent employee feedback, including whether employees would recommend their organisation to friends and family.The company said the recognition reflected its focus on creating a workplace where employees can develop their expertise and build careers. ..
Next Story
Infrastructure Urban

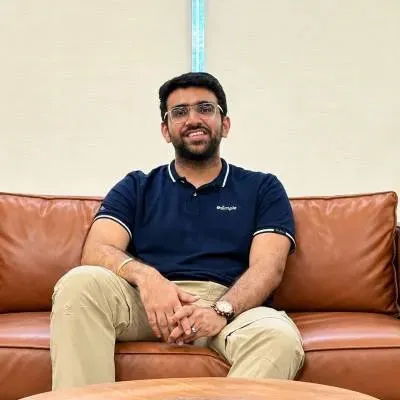
India needs an export-execution mindset: Vishesh Jain

Interview with Vishesh Jain, Founder & CEO, EximpleWhat gaps in India’s global trade ecosystem led you to build Eximple, and what problem did you see businesses struggling with most?Eximple came out of a problem that all three founders had seen from different choke points in the trade ecosystem. India has millions of MSMEs and manufacturers, and many of them can make products that are genuinely competitive on quality. Yet only a small fraction is able to build meaningful international businesses. In our experience, the gap is usually not manufacturing capability; it is the ability to exe..
Next Story
Building Material

Nuvoco reports 13.5% revenue growth in Q2 FY27

Nuvoco Vistas Corp. Ltd. reported consolidated revenue of Rs 27.9 billion for Q2 FY27, up 13.5% year on year. Cement sales volume rose 9% to 4.7 million tonnes (MMT), while EBITDA increased 11% to Rs 4.11 billion.The company said it began its cement operations in 2014 with a 2.3 MMT per annum (MMTPA) operation at Nimbol. It now aims to reach 35 MMTPA of cement capacity by FY28, nearly 15 times its initial capacity. Its portfolio spans cement, ready-mix concrete and modern building materials.On sustainability and cost efficiency, Nuvoco partnered with CleanMax for a 46.4 MW wind-solar hybrid re..

Advertisement

Subscribe to Our Newsletter

Get daily newsletters around different themes from Construction world.

STAY CONNECTED

Advertisement

SPECIAL OFFER
QR Code